3D Motion Capture Market Size, Share & Trends Analysis Report By Component (Hardware, Software, Services), By System Type (Optical, Inertial, Electromagnetic, Markerless), By Application (Media & Entertainment, Sports & Performance Analytics, Healthcare & Rehabilitation, Industrial & Robotics, Defense & Aerospace, Education & Research), By End User (Film & Television Studios, Game Developers, Sports Organizations, Healthcare Institutions, Industrial Enterprises, Research Institutions) Forecasts,
USD 3950
3D Motion Capture Market Size
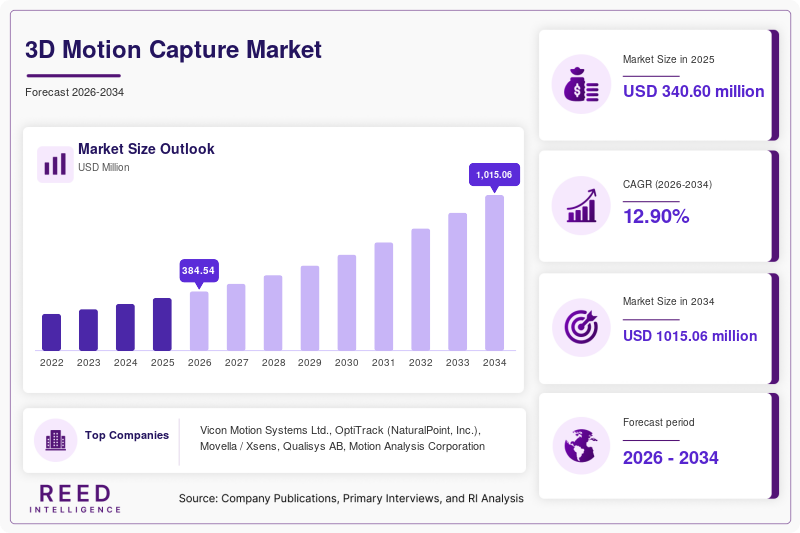
The global 3D Motion Capture Market size was valued at USD 340.60 million in 2025 and is projected to grow from USD 387.20 million in 2026 to USD 1,015.06 million by 2034, registering a CAGR of 12.90% during the forecast period from 2026 to 2034.
3D motion capture is shifting from a specialist production technology toward a broader movement-data platform used across entertainment, sports, healthcare, robotics, research and virtual production. Vicon describes applications spanning films, games and live events as well as sports performance, clinical gait analysis, engineering, military training, ergonomics and robotics.
The most important technology change is the combination of optical, inertial and markerless systems rather than the replacement of one technology by another. Markerless capture is reducing setup requirements because performers do not need suits or physical markers, while optical tracking continues to provide advantages when highly accurate tracking of props and complex interactions is required. Vicon's GDC 2026 demonstrations highlighted hybrid workflows combining markerless body capture with optical tracking for physical objects.
AI-based computer vision is also lowering the operational barrier. Move AI's Genesis uses multiple cameras and deep-learning models to reconstruct human motion in 3D and operates locally using NVIDIA GPUs. Qualisys has similarly expanded into markerless biomechanics with Prisma Pose, integrating skeletal tracking directly into its Track Manager software.
3D Motion Capture Market Drivers
Markerless capture is reducing the operational cost of motion capture
Traditional optical motion capture requires cameras, calibration, markers, specialized operators and performer preparation. Markerless systems remove several of these steps by extracting skeletal movement from video. Vicon's markerless solution is designed for game studios, film productions and television creatives, while its GDC 2026 demonstrations showed performers entering a capture volume and beginning recording without suits or markers. Move AI similarly positions markerless technology around lower costs, faster shooting and scalable capture volumes. The commercial mechanism is lower setup friction: studios and organizations can capture more iterations without treating motion capture as a highly specialized production stage. This particularly affects smaller production teams and organizations that previously found conventional systems difficult to justify.
Real-time virtual production and game development are increasing capture requirements
Motion capture is becoming more closely integrated with real-time engines and virtual production rather than being limited to post-production animation. Vicon's 2026 GDC work highlights real-time retargeting and Unreal Engine integration for virtual production, game development and cinematics. Epic Games' Unreal Engine 5.8, released in June 2026, also expanded MetaHuman capabilities, including easier full-body performance capture and large-scale digital-human workflows. These developments increase the value of motion data because creators can evaluate performances while scenes are being developed. The result is a stronger connection between capture hardware, processing software and game-engine pipelines.
Motion capture is expanding into sports, healthcare and robotics
The addressable customer base is expanding beyond entertainment. In July 2026, Carnegie Mellon University selected OptiTrack as a motion-capture technology partner for its Robotics Innovation Center, deploying 92 cameras across indoor and outdoor research facilities. Qualisys launched OnTraq for elite sports and Prisma Pose for biomechanics laboratories in 2026, extending markerless capture into athlete assessment, clinical work and research. These applications create demand for different system characteristics: sports customers prioritize repeatable movement analysis, healthcare users require biomechanical accuracy and robotics researchers need precise ground-truth movement data. This diversification reduces reliance on film and game production cycles.
3D Motion Capture Market Restraints
High Hardware and Infrastructure Requirements
Professional optical motion capture remains capital-intensive because high-quality cameras, tracking systems, calibration infrastructure, computing equipment and dedicated capture spaces can be required. OptiTrack's 2026 Prime X 260 system, for example, targets large-volume environments with 26-megapixel sensors and long tracking ranges. While these capabilities improve precision and capture volume, they can increase the investment required from customers. Smaller studios and institutions may therefore choose inertial or markerless alternatives even when optical systems provide stronger tracking performance. The market consequently remains segmented between premium high-precision installations and more accessible systems.
Accuracy and Data-Quality Trade-Offs
Markerless capture improves convenience but does not eliminate technical limitations. Vicon notes that props remain more difficult for generalized markerless systems because their shapes, surfaces and movements vary substantially; optical markers can therefore retain an advantage for rigid objects and complex interactions. Markerless systems also depend on camera positioning, lighting, occlusion handling and AI reconstruction. Customers working on high-value productions or clinical applications may therefore continue using optical or hybrid systems where data reliability is more important than setup speed.
3D Motion Capture Market Opportunities
AI-Powered Markerless Motion Capture
AI-based markerless capture provides one of the clearest expansion opportunities because it reduces the physical infrastructure needed to generate usable movement data. Move AI's Genesis is designed as an enterprise markerless system capable of local processing, while Vicon and Qualisys are integrating markerless capture directly into established optical and biomechanics workflows. The opportunity is not limited to replacing optical cameras. Hybrid systems can combine markerless human tracking with optical tracking for props, equipment and difficult objects, allowing customers to select the appropriate technology for each part of a production.
Sports, Healthcare and Biomechanics
Sports and healthcare provide additional growth paths because motion capture can convert movement into measurable biomechanical data. Qualisys launched OnTraq for elite sports assessment and Prisma Pose for biomechanics laboratories in 2026. These applications create recurring demand for software, analytics and data-management services in addition to capture hardware. The commercial model therefore shifts from one-time equipment purchases toward integrated hardware, software and analytical workflows.
Segmental Analysis
Component
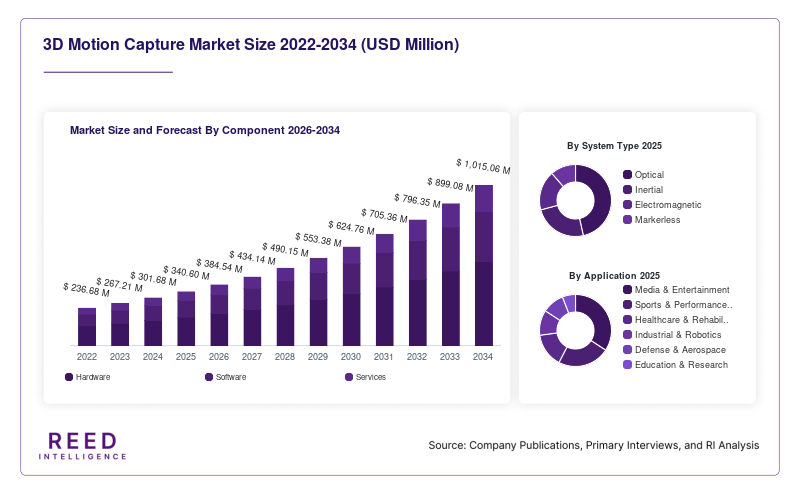
Hardware represents approximately 44% of the global market in 2025, supported by demand for optical cameras, inertial sensors, tracking markers, capture infrastructure and related equipment. Professional entertainment, sports laboratories and research institutions continue to require dedicated capture hardware where accuracy and repeatability are critical.
Software accounts for approximately 34%, reflecting the increasing importance of real-time tracking, skeletal solving, retargeting, data processing and integration with production platforms.
Software is the fastest-growing component, with a CAGR of approximately 15.1%, as AI-based processing and markerless workflows shift more of the value proposition toward algorithms and motion-data management. Qualisys' Prisma Pose integration and Move AI's local AI-based Genesis platform illustrate this transition.
System Type
Optical systems account for approximately 49% of the global market in 2025, reflecting their established use in professional film, games, biomechanics and research environments. Vicon and OptiTrack continue to develop high-precision optical platforms for large capture volumes and complex tracking requirements.
Inertial systems represent approximately 27%, while Markerless systems account for 19% and Electromagnetic systems approximately 5%.
Markerless systems are the fastest-growing system type, with a CAGR of approximately 19.2%, supported by lower setup requirements, AI-based tracking and integration with existing production workflows. Vicon, Qualisys and Move AI have all expanded their markerless offerings.
Application
Media & Entertainment represents approximately 42% of the global market in 2025, supported by film, television, video games, virtual production, animation and immersive experiences. Vicon identifies film, episodic television, games and live events as established motion-capture applications.
Sports & Performance Analytics accounts for approximately 21%, while Healthcare & Rehabilitation represents 16%, Industrial & Robotics 11%, Defense & Aerospace 6%, and Education & Research 4%.
Healthcare & Rehabilitation is the fastest-growing application, with a CAGR of approximately 16.8%, supported by gait analysis, rehabilitation, biomechanics and clinical movement assessment. The expansion of Qualisys' markerless products into biomechanics and elite sports illustrates this broader use case.
End User
Film & Television Studios account for approximately 31% of the global market, reflecting the continued use of performance capture for digital characters, visual effects and virtual production.
Game Developers represent approximately 27%, supported by real-time character animation and increasing integration between motion capture and game engines.
Sports Organizations account for 17%, followed by Healthcare Institutions at 13%, Industrial Enterprises at 7%, and Research Institutions at 5%.
Sports Organizations are the fastest-growing end-user segment, with a CAGR of approximately 15.8%, supported by athlete biomechanics, injury-prevention programs and performance analysis. OptiTrack's 2026 Carnegie Mellon partnership also demonstrates the expansion of advanced capture technology into robotics research.
Regional Analysis
North America 3D Motion Capture Market
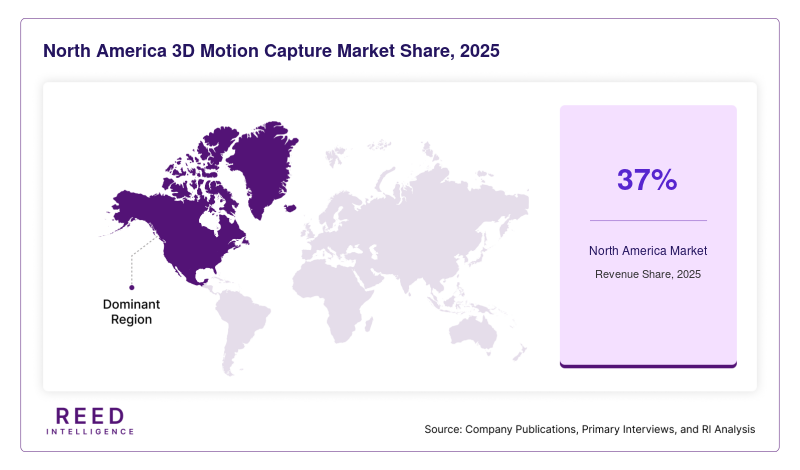
North America represents approximately 37% of the global market in 2025, supported by a large concentration of entertainment studios, game developers, sports organizations, research institutions and technology companies. Independent market research also identifies North America as the leading regional market, with a 37% share in 2025. The U.S. has particularly strong demand from Hollywood, AAA game development, virtual production, sports science and robotics research. OptiTrack's 2026 partnership with Carnegie Mellon University's Robotics Innovation Center, involving 92 cameras across two facilities, demonstrates the depth of institutional demand. Vicon also continues to expand applications across entertainment, sports, healthcare and engineering. North America is projected to grow at approximately 11.7% CAGR.
Europe 3D Motion Capture Market
Europe accounts for approximately 26% of the global market in 2025, supported by established motion-capture manufacturers, film production, sports science, medical research and engineering applications. The region is home to Vicon in the UK and Qualisys in Sweden, giving it a strong technology-development base. Vicon's 2026 activity includes virtual-production installations, game-development workflows and its acquisition of Captive Devices, while Qualisys expanded its markerless portfolio through Prisma Pose and OnTraq. Europe is projected to grow at approximately 12.3% CAGR, supported by continued adoption in entertainment, sports and biomechanics.
APAC 3D Motion Capture Market
APAC represents approximately 25% of the global market and is the fastest-growing region, with a CAGR of approximately 16.1%. The region benefits from expanding game development, animation, virtual production, sports technology, robotics research and healthcare applications. Japan, China, South Korea, India and Australia represent important technology and end-user markets. The expansion of markerless capture is particularly relevant because it can reduce the infrastructure barrier for new customers. Qualisys also opened an India subsidiary in 2025 to support regional growth and customer service. Increasing robotics and AI research further expands the requirement for high-quality movement data, while regional entertainment industries create additional demand for character animation and virtual production.
Middle East and Africa 3D Motion Capture Market
Middle East and Africa accounts for approximately 5% of the global market and is projected to grow at approximately 14.0% CAGR. Demand is developing around sports performance, immersive entertainment, education, healthcare and large-scale digital experiences. Sports organizations and new entertainment infrastructure provide potential adoption points because motion capture can support athlete assessment as well as digital content production. Markerless solutions may be particularly relevant where customers want to reduce dedicated studio infrastructure and technical staffing. The primary constraint remains the smaller installed base of specialized capture facilities compared with North America and Europe.
Latin America 3D Motion Capture Market
Latin America represents approximately 7% of the global market and is projected to grow at approximately 13.6% CAGR. Brazil and Mexico provide the region's principal commercial and technology hubs, with opportunities across sports, advertising, gaming, healthcare and academic research. More accessible inertial and markerless technologies can reduce the capital requirements associated with traditional optical installations. This creates an adoption path for universities, sports facilities and smaller creative studios that may not require the full infrastructure of high-end film-production stages. Continued development of gaming, digital media and sports analytics should support regional demand.
Competitive Landscape
The competitive landscape is increasingly divided between high-precision optical providers, wearable/inertial systems and AI-driven markerless platforms. Vicon, OptiTrack and Qualisys continue to strengthen optical capabilities, while Xsens remains associated with wearable inertial capture and companies such as Move AI and other technology developers are expanding markerless systems.
Vicon is broadening its technology stack rather than relying exclusively on optical capture. In September 2026, Vicon acquired Captive Devices, adding head-mounted camera technology for markerless facial performance capture to its existing body and hand-motion ecosystem. This gives Vicon a wider performance-capture offering spanning body, hand and facial data.
OptiTrack is simultaneously pushing precision and system flexibility. Its Prime X 260 and Slim X 260 cameras introduced 26-megapixel sensors and high-accuracy tracking for large capture environments in January 2026. In July 2026, the company introduced ActiveIO, combining active tracking, RF communication and IMU sensor fusion for virtual production, live events, location-based VR and tactical training.
Key Market Players
- Vicon Motion Systems Ltd.
- OptiTrack (NaturalPoint, Inc.)
- Movella / Xsens
- Qualisys AB
- Motion Analysis Corporation
- Move AI
- Rokoko
- Noitom
- Noraxon USA
- PhaseSpace
- Codamotion
- BTS Bioengineering
- Northern Digital Inc. (NDI)
Recent Market Developments
- September 2026 – Vicon acquired Captive Devices, adding head-mounted camera and markerless facial performance capture to its motion-capture portfolio for visual effects, games and virtual production.
- July 2026 – OptiTrack launched ActiveIO, combining active markers, two-way RF communication and IMU sensor fusion for virtual production, location-based VR, live events and tactical training.
3D Motion Capture Market Segments
By Component
- Hardware
- Software
- Services
By System Type
- Optical
- Inertial
- Electromagnetic
- Markerless
By Application
- Media & Entertainment
- Sports & Performance Analytics
- Healthcare & Rehabilitation
- Industrial & Robotics
- Defense & Aerospace
- Education & Research
By End User
- Film & Television Studios
- Game Developers
- Sports Organizations
- Healthcare Institutions
- Industrial Enterprises
- Research Institutions
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM