Anemia Drugs Market Size, Share & Trends Analysis Report By Drug Type (Medicines and Dietary Supplements), By Therapy Type (Oral Iron Therapy, Parenteral Iron Therapy, Red Blood Cell Transfusion and Other Therapy Types), By Anemia Type (Iron Deficiency Anemia, Sickle Cell Anemia, Aplastic Anemia, Hemolytic Anemia, Pernicious Anemia and Others), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies and Online Pharmacies) and By Region (North America, Europe, Asia-Pacific, Latin America,
USD 3950
Anemia Drugs Market Size
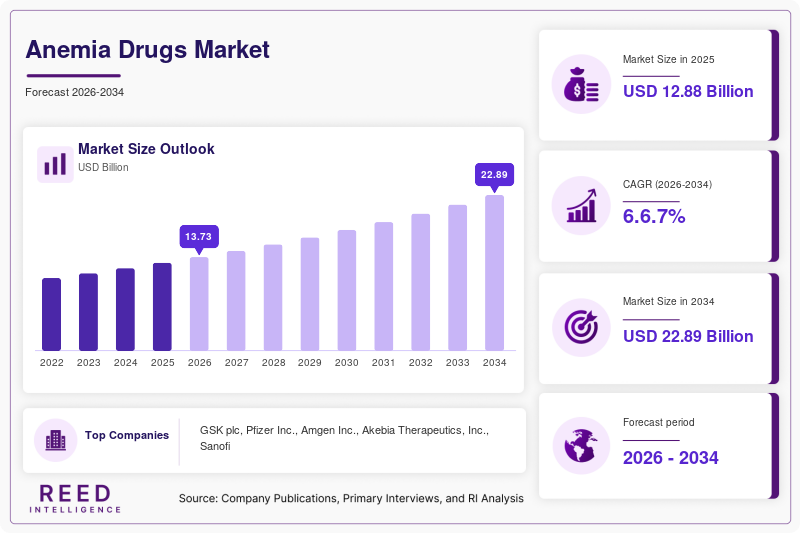
The global anemia drugs market was valued at USD 12.88 billion in 2025 and is projected to grow from USD 13.71 billion in 2026 to USD 22.98 billion by 2034, registering a CAGR of 6.67% during the forecast period from 2026 to 2034.
Anemia drugs are pharmaceutical products used to prevent or treat anemia caused by inadequate iron availability, chronic kidney disease, inherited blood disorders, nutritional deficiencies, chronic diseases and other underlying conditions. Treatment approaches include oral and injectable iron therapies, erythropoiesis-stimulating agents, red blood cell transfusion support and newer targeted therapies.
The market is supported by the substantial global burden of anemia and increasing diagnosis and treatment of iron-deficiency anemia, chronic kidney disease-associated anemia and inherited disorders such as thalassemia and sickle cell disease.
Anemia Drugs Market Drivers
Rising Burden of Iron Deficiency
Iron deficiency remains a major cause of anemia worldwide. Increasing diagnosis of iron-deficiency anemia is supporting demand for oral and intravenous iron therapies.
The availability of multiple administration options allows treatment to be adapted to disease severity, patient tolerance and underlying conditions.
Growing Chronic Kidney Disease Population
Chronic kidney disease is an important source of anemia because impaired kidney function can reduce erythropoietin production and disrupt iron metabolism.
This is supporting demand for iron replacement therapies, erythropoiesis-stimulating agents and newer HIF-PHIs.
Increasing Focus on Oral Treatments
Oral anemia therapies can provide advantages in administration and patient convenience compared with injectable treatments.
The approval of oral mitapivat for thalassemia in the United States in January 2026 demonstrates continued development of oral treatment options for specific anemia populations.
Growing Development of Targeted Therapies
Drug developers are increasingly targeting pathways involved in iron metabolism, hepcidin regulation and red blood cell production.
HIF-PHIs are one example of this development, while emerging hepcidin-targeting approaches are being evaluated for anemia associated with inflammatory and hematologic conditions.
Anemia Drugs Market Restraints
Treatment-Related Safety Concerns
Anemia therapies can involve safety considerations that require appropriate patient selection and monitoring.
For example, the FDA added a boxed warning in September 2026 to ferric carboxymaltose injection labeling concerning symptomatic hypophosphatemia and recommended phosphate monitoring for patients at risk.
Generic Competition
Several established anemia therapies have generic alternatives.
The availability of generic iron products can increase price competition and place pressure on manufacturers of branded therapies.
Complex Disease Etiology
Anemia can result from multiple underlying conditions, meaning treatment often requires identification and management of the underlying cause rather than relying on a single therapeutic approach.
This complexity can affect treatment selection, diagnosis and patient management.
Anemia Drugs Market Opportunities
Expansion of Oral Anemia Therapies
The development of oral therapies provides opportunities to address patients who prefer alternatives to injectable treatment.
Recent approval of mitapivat for thalassemia illustrates the expansion of oral treatment approaches into inherited anemia.
HIF-PHI Development
HIF-PHIs represent an important area of pharmaceutical development, particularly for anemia associated with chronic kidney disease and other conditions involving impaired erythropoiesis and iron utilization.
Their oral administration and mechanism targeting the body's response to low oxygen provide opportunities for differentiated therapies.
Increasing Pediatric Treatment Options
Regulatory expansion of anemia therapies into pediatric populations is creating additional market opportunities. The FDA approved Accrufer (ferric maltol) for iron deficiency in pediatric patients aged 10 years and older in December 2025.
Emerging Therapies for Rare Anemias
Rare and inherited anemias represent opportunities for specialized pharmaceutical development.
Therapies addressing thalassemia, sickle cell disease, autoimmune hemolytic anemia and other less common conditions can provide differentiated treatment options and expand the addressable market.
Drug Type Segment Analysis
Medicines Hold the Largest Share
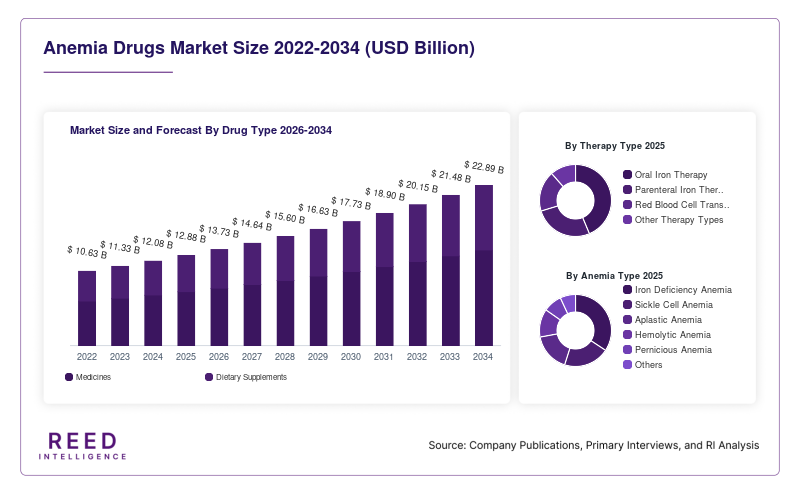
Medicines accounted for approximately 82% of the anemia drugs market in 2025, making them the dominant drug-type segment. Prescription and over-the-counter medicines remain central to the management of clinically diagnosed anemia, particularly iron-deficiency anemia and anemia associated with chronic disease.
The medicines segment includes oral and parenteral iron products, erythropoiesis-stimulating agents and newer targeted therapies.
Dietary supplements accounted for approximately 18% and are projected to grow at approximately 5.8% CAGR, supported by preventive nutrition, increased awareness of iron deficiency and consumer demand for nutritional products.
Therapy Type Segment Analysis
Oral Iron Therapy Holds the Largest Share
Oral iron therapy accounted for approximately 38% of the market in 2025, making it the largest therapy segment. Oral iron is widely used because of its accessibility, established clinical use and comparatively convenient administration.
Parenteral iron therapy accounted for approximately 30% and is projected to grow at approximately 7.2% CAGR, making it the fastest-growing major therapy segment. Intravenous iron is increasingly used when oral iron is poorly tolerated, ineffective or insufficient for the patient's needs.
Red blood cell transfusion represented approximately 18%, while other therapy types accounted for approximately 14%.
Anemia Type Segment Analysis
Iron Deficiency Anemia Holds the Largest Share
Iron deficiency anemia accounted for approximately 52% of the market in 2025, making it the dominant anemia-type segment. The widespread prevalence of iron deficiency and availability of oral and injectable iron treatments support its leading position.
Sickle cell anemia accounted for approximately 17% and is projected to grow at approximately 7.4% CAGR, making it the fastest-growing major anemia-type segment. Continued development of disease-modifying therapies and increasing attention to specialized treatment are supporting market expansion.
Aplastic anemia represented approximately 10%, hemolytic anemia 9%, pernicious anemia 5%, and other anemia types approximately 7%.
Distribution Channel Segment Analysis
Hospital Pharmacies Hold the Largest Share
Hospital pharmacies accounted for approximately 48% of the market in 2025, making them the largest distribution channel. Injectable therapies, transfusion-related treatments and therapies for complex or severe anemia are frequently administered or managed in hospital settings.
Online pharmacies accounted for approximately 15% and are projected to grow at approximately 9.1% CAGR, making them the fastest-growing distribution channel. Increasing digital healthcare adoption and improved access to prescription and non-prescription medicines are supporting online pharmaceutical purchasing.
Retail pharmacies represented approximately 37%.
Anemia Drugs Market Regional Analysis
North America Holds the Largest Share
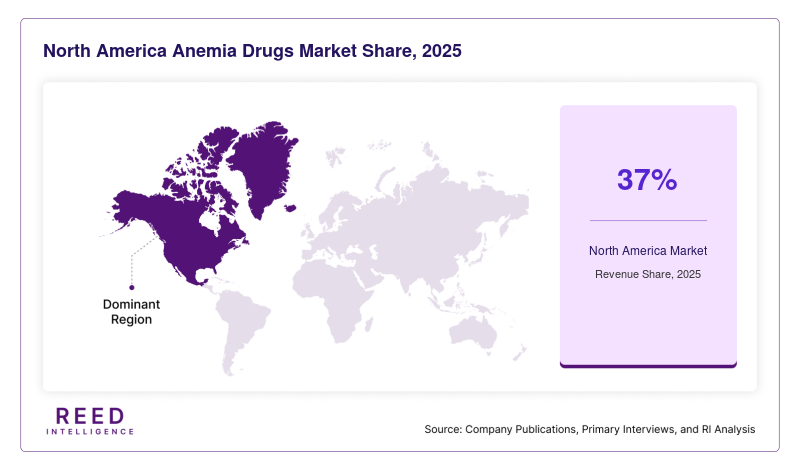
North America accounted for approximately 37% of the global anemia drugs market in 2025, making it the dominant regional market. The region benefits from advanced healthcare infrastructure, high pharmaceutical expenditure, established diagnosis and treatment pathways and significant development of novel anemia therapies.
The United States is an important market for therapies addressing iron deficiency, chronic kidney disease-associated anemia and inherited blood disorders.
Asia-Pacific accounted for approximately 29% and is projected to grow at approximately 7.8% CAGR, making it the fastest-growing major region. Population size, improving healthcare access, increasing diagnosis of anemia and expanding pharmaceutical markets are supporting regional growth.
Europe Maintains Strong Demand
Europe accounted for approximately 25% of the market in 2025 and is projected to grow at approximately 5.8% CAGR.
Demand is supported by established healthcare systems, anemia screening and treatment programs, chronic disease management and pharmaceutical innovation.
Asia-Pacific Is the Fastest-Growing Region
Asia-Pacific is projected to grow at approximately 7.8% CAGR through 2034. Increasing healthcare expenditure, improved diagnostic capabilities and rising awareness of nutritional deficiencies are expanding the treated patient population.
Large populations in China and India provide substantial demand potential, while Japan, South Korea and Australia have mature healthcare systems supporting advanced anemia therapies.
Latin America Shows Steady Expansion
Latin America accounted for approximately 5% of the market in 2025 and is projected to grow at approximately 5.9% CAGR.
Increasing healthcare access, anemia screening and demand for iron therapies are supporting regional expansion.
Middle East & Africa Represents an Emerging Market
Middle East & Africa accounted for approximately 4% of the market in 2025 and is projected to grow at approximately 6.2% CAGR.
Improving healthcare infrastructure, greater awareness of anemia and increasing access to pharmaceutical treatments are supporting market development.
Anemia Drugs Market Competitive Landscape
Competition in the anemia drugs market is based on clinical efficacy, safety profile, route of administration, treatment convenience, therapeutic indications, product availability, pricing, regulatory approvals and pipeline strength.
Pharmaceutical companies are increasingly focusing on oral therapies, novel mechanisms of action, pediatric indications and treatments for specific inherited or chronic-disease-associated anemias.
Key Market Players
- GSK plc
- Pfizer Inc.
- Amgen Inc.
- Akebia Therapeutics, Inc.
- Sanofi
- Takeda Pharmaceutical Company Limited
- Bayer AG
- Pharmacosmos A/S
- Shield Therapeutics plc
- Biocon Limited
Anemia Drugs Market Recent Developments
- In January 2026, the U.S. FDA approved Aqvesme (mitapivat) as the first oral treatment for anemia in adults with alpha- or beta-thalassemia. The approval expands the role of oral therapies in inherited anemia treatment.
- In June 2026, the FDA approved generic ferric carboxymaltose injections from multiple manufacturers for iron-deficiency anemia, including use in patients who cannot tolerate or do not adequately respond to oral iron and certain patients with chronic kidney disease.
Anemia Drugs Market Segments
By Drug Type
- Medicines
- Dietary Supplements
By Therapy Type
- Oral Iron Therapy
- Parenteral Iron Therapy
- Red Blood Cell Transfusion
- Other Therapy Types
By Anemia Type
- Iron Deficiency Anemia
- Sickle Cell Anemia
- Aplastic Anemia
- Hemolytic Anemia
- Pernicious Anemia
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM