Door to Door Delivery Services Market Size, Share & Trends Analysis Report By Service Type (Standard Delivery, Same-Day Delivery, Express Delivery and Scheduled Delivery), By Delivery Mode (Road, Air and Rail), By End User (E-commerce, Retail, Food & Beverage, Healthcare, Manufacturing and Others), By Business Model (B2B, B2C and C2C) and By Region (North America, Europe, Asia-Pacific, Latin America, Middle East & Africa) Forecasts, 2026–2034
USD 3950
Door to Door Delivery Services Market Size
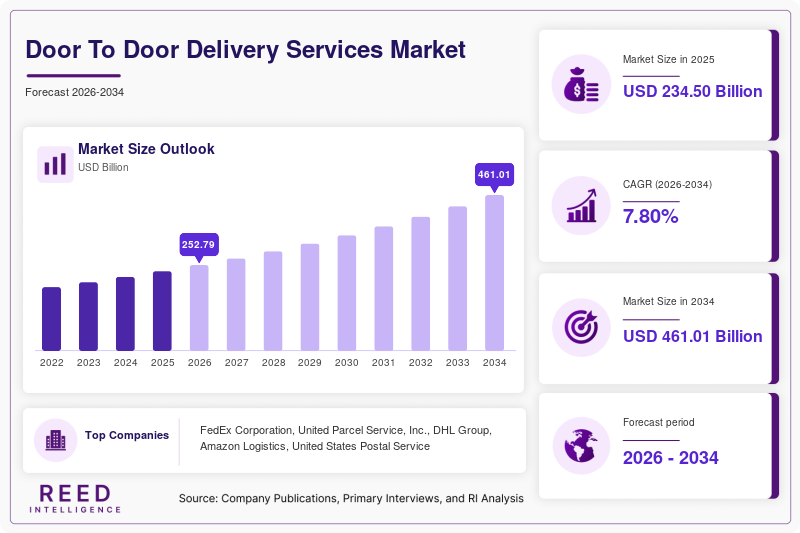
The global door to door delivery services market was valued at USD 234.50 billion in 2025 and is projected to grow from USD 252.78 billion in 2026 to USD 453.70 billion by 2034, registering a CAGR of 7.80% during the forecast period from 2026 to 2034.
Door-to-door delivery services encompass the transportation of parcels, merchandise, food, documents and other goods directly from the sender's location to the recipient's specified address. The service can include pickup, transportation, sorting, last-mile delivery, tracking and proof of delivery.
The market is being reshaped by the continued expansion of e-commerce, increasing consumer expectations for rapid delivery, urbanization and the digitalization of logistics operations. Businesses are increasingly outsourcing delivery activities to specialized logistics providers to improve geographic reach and reduce the complexity of managing their own delivery networks.
Door to Door Delivery Services Market Drivers
Rapid Growth of E-commerce
The continued expansion of online retail is one of the primary drivers of door-to-door delivery demand.
Online purchases require reliable parcel delivery from fulfillment centers, stores or third-party sellers to residential and business addresses. The increasing penetration of mobile commerce is further expanding delivery volumes.
Increasing Consumer Demand for Faster Delivery
Consumers increasingly expect flexible delivery windows and faster fulfillment.
Same-day, next-day and scheduled delivery options are becoming important differentiators for online retailers and logistics providers, particularly in densely populated urban markets.
Urbanization and Changing Consumer Lifestyles
Urban populations are increasingly relying on online shopping, food delivery, subscription services and home delivery for everyday purchases.
These behavioral changes are increasing the frequency and diversity of door-to-door deliveries.
Growth of Third-Party Logistics
Businesses are increasingly using third-party logistics providers instead of maintaining entirely internal delivery networks.
Outsourcing allows companies to access established transportation infrastructure, delivery personnel, technology platforms and regional distribution capabilities.
Increasing Digitalization of Logistics
Digital platforms are improving delivery visibility and operational coordination.
GPS tracking, mobile delivery applications, automated dispatch, electronic proof of delivery and route optimization are helping providers manage increasingly complex delivery networks.
Door to Door Delivery Services Market Restraints
High Last-Mile Delivery Costs
The final stage of delivery can represent a significant portion of total logistics costs.
Traffic congestion, failed deliveries, low drop density and increasing labor expenses can reduce provider margins.
Driver and Labor Shortages
Delivery networks depend heavily on drivers, couriers and warehouse personnel.
Labor shortages and wage inflation can increase operating costs and make it more difficult for providers to expand delivery capacity.
Traffic Congestion and Urban Restrictions
Congested urban areas can increase delivery times and fuel consumption.
Restrictions on commercial vehicles, limited parking and low-emission requirements can further complicate last-mile operations.
Fuel Price Volatility
Road-based delivery networks are exposed to changes in fuel prices.
Higher fuel costs can increase transportation expenses and place pressure on delivery-service providers and merchants.
Door to Door Delivery Services Market Opportunities
Expansion of Same-Day Delivery
Same-day delivery represents an important opportunity as consumers increasingly value speed and convenience.
Retailers are establishing local fulfillment centers and micro-fulfillment facilities to position inventory closer to customers and shorten delivery distances.
Automated Delivery Solutions
Autonomous delivery robots, drones and automated sorting systems are being developed to address delivery efficiency and labor constraints.
Although adoption varies by market and regulatory environment, these technologies can create new operating models for selected delivery applications.
Sustainable Last-Mile Delivery
Growing environmental requirements are encouraging logistics companies to deploy electric vans, electric two-wheelers, cargo bikes and route-optimization systems.
Sustainable delivery fleets can help reduce fuel consumption and emissions in urban environments.
Growth of Cross-Border E-commerce
Cross-border online shopping is increasing the need for integrated international delivery services.
Providers that combine customs management, international transportation, tracking and final-mile delivery can benefit from the expansion of global e-commerce.
Service Type Segment Analysis
Standard Delivery Holds the Largest Share
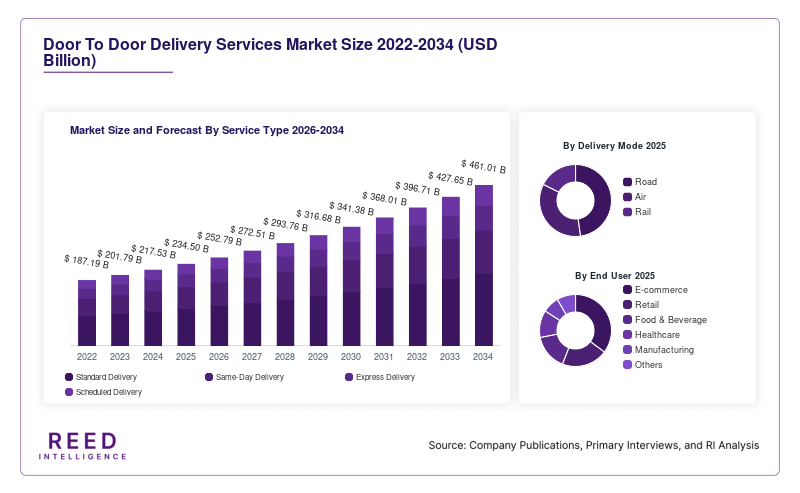
Standard delivery accounted for approximately 43% of the market in 2025, making it the largest service-type segment. Standard services remain widely used for routine e-commerce shipments, retail deliveries and business-to-business parcel transportation.
Same-day delivery accounted for approximately 21% and is projected to grow at approximately 10.2% CAGR, making it the fastest-growing major service segment. Increasing consumer expectations for rapid fulfillment and the expansion of urban fulfillment networks are supporting growth.
Express delivery represented approximately 24%, while scheduled delivery accounted for approximately 12%.
Delivery Mode Segment Analysis
Road Delivery Holds the Largest Share
Road delivery accounted for approximately 72% of the market in 2025, making it the dominant delivery mode. Road transportation provides flexibility for pickup and final-mile delivery and is particularly important for domestic parcel distribution.
Air delivery accounted for approximately 19% and is projected to grow at approximately 8.4% CAGR, making it the fastest-growing major delivery mode. Increasing demand for express, time-sensitive and cross-border shipments is supporting air-based delivery.
Rail accounted for approximately 9% of the market.
End-User Segment Analysis
E-commerce Holds the Largest Share
E-commerce accounted for approximately 39% of the door to door delivery services market in 2025, making it the largest end-user segment. Online retail depends heavily on residential and business delivery networks to complete purchases.
Healthcare accounted for approximately 11% and is projected to grow at approximately 9.0% CAGR, making it the fastest-growing major end-user segment. Demand for home-delivered medicines, medical supplies, diagnostic samples and other healthcare products is supporting expansion.
Retail represented approximately 24%, food & beverage 13%, manufacturing 8%, and other end users approximately 5%.
Business Model Segment Analysis
B2C Holds the Largest Share
B2C delivery accounted for approximately 55% of the market in 2025, making it the largest business-model segment. Residential e-commerce deliveries represent a major component of B2C activity.
C2C accounted for approximately 13% and is projected to grow at approximately 8.6% CAGR, making it the fastest-growing major business-model segment. Peer-to-peer marketplaces, resale platforms and consumer-to-consumer commerce are increasing parcel activity.
Door to Door Delivery Services Market Regional Analysis
Asia-Pacific Holds the Largest Share
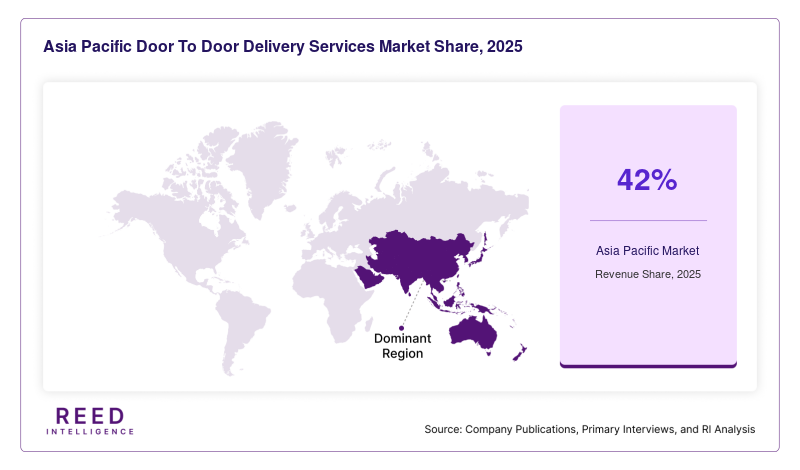
Asia-Pacific accounted for approximately 42% of the global door to door delivery services market in 2025, making it the largest regional market. The region benefits from its large consumer population, extensive e-commerce ecosystem, rapidly expanding urban centers and increasing adoption of digital commerce.
China, India, Japan, South Korea and Southeast Asian economies represent important delivery markets.
Asia-Pacific is also the fastest-growing major region, with approximately 9.1% CAGR through 2034, supported by e-commerce penetration, expanding middle-class consumption, urbanization and logistics infrastructure development.
North America Maintains Strong Demand
North America accounted for approximately 27% of the market in 2025 and is projected to grow at approximately 6.7% CAGR.
The region has a mature e-commerce market and established parcel-delivery infrastructure. Demand is increasingly focused on same-day fulfillment, delivery visibility and flexible delivery options.
Europe Focuses on Efficient and Sustainable Delivery
Europe accounted for approximately 20% of the market in 2025 and is projected to grow at approximately 6.5% CAGR.
E-commerce growth, cross-border commerce and increasing adoption of electric delivery fleets are supporting the regional market.
Latin America Shows Expanding Demand
Latin America accounted for approximately 7% of the market in 2025 and is projected to grow at approximately 8.0% CAGR.
Growing online retail penetration and improving logistics infrastructure are expanding demand for door-to-door delivery.
Middle East & Africa Represents an Emerging Market
Middle East & Africa accounted for approximately 4% of the market in 2025 and is projected to grow at approximately 8.2% CAGR.
Digital commerce adoption, urban development and investments in logistics infrastructure are creating opportunities for delivery-service providers.
B2B represented approximately 32% of the market.
Door to Door Delivery Services Market Competitive Landscape
Competition in the door to door delivery services market is based on delivery speed, geographic coverage, pricing, tracking capabilities, fleet capacity, technology infrastructure, service reliability and fulfillment capabilities.
Providers are increasingly investing in automated sorting, route optimization, digital tracking, electric fleets and localized fulfillment networks.
Key Market Players
- FedEx Corporation
- United Parcel Service, Inc.
- DHL Group
- Amazon Logistics
- United States Postal Service
- SF Express
- DPDgroup
- Royal Mail
- Aramex
- Blue Dart Express
Door to Door Delivery Services Market Recent Developments
- DHL has continued investing in autonomous and technology-enabled delivery solutions, including robotics and automated logistics systems, as part of its broader strategy to improve operational efficiency and address labor requirements.
- UPS has continued expanding alternative-fuel and electric vehicles across its delivery network as part of its efforts to reduce emissions and improve fleet efficiency.
Door To Door Delivery Services Market Segments
By Service Type
- Standard Delivery
- Same-Day Delivery
- Express Delivery
- Scheduled Delivery
By Delivery Mode
- Road
- Air
- Rail
By End User
- E-commerce
- Retail
- Food & Beverage
- Healthcare
- Manufacturing
- Others
By Business Model
- B2B
- B2C
- C2C
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM