Footwear Manufacturing Machine Market Size, Share & Trends Analysis Report By Machine Type (Cutting Machines, Stitching Machines, Lasting Machines), By Automation (Manual, Semi-Automatic, Automatic), By End User (Designer, Commercial-Athletic, Casual), By Application (Leather Footwear, Non-Leather Footwear), By Service Type (Installation & Commissioning, Maintenance & Repair, Retrofitting & Upgrades) Forecasts, 2026–2034
USD 3950
Footwear Manufacturing Machine Market Size
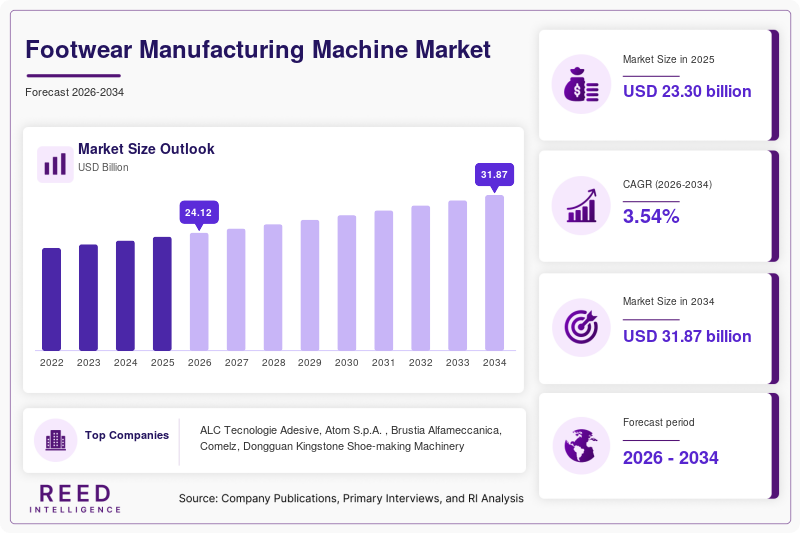
The Footwear Manufacturing Machine Market was valued at USD 23.30 billion in 2025 and is estimated at USD 24.12 billion in 2026. Based on the supplied forecast, the market is projected to reach USD 31.87 billion by 2034, with a stated CAGR of 3.54% during the forecast period.
Forecast validation: The supplied 2025 and 2034 market values imply a CAGR of approximately 3.67% over nine years. The 2026 and 2034 values also imply approximately 3.67% over eight years. The stated 3.54% CAGR would produce a lower 2034 value if applied to the 2026 base. This report retains all user-supplied figures and treats the CAGR as a reported assumption requiring reconciliation before publication.
Footwear manufacturing machines are industrial systems used to cut, prepare, stitch, shape, assemble and finish footwear components. The market encompasses machinery used by large footwear factories, contract manufacturers, specialist producers and smaller workshops. Equipment ranges from individual manual or semi-automatic machines to integrated automated production systems.
The industry's demand base is geographically concentrated. According to the World Footwear Yearbook 2026, global footwear production reached 24.6 billion pairs in 2025, with Asia accounting for approximately 88.7% of output. China produced 13.7 billion pairs, India 3.0 billion and Vietnam 1.7 billion. These production figures are evidence of the concentration of footwear manufacturing, not direct measures of machinery sales, but they help explain why Asian manufacturing hubs are important locations for equipment demand, installation, maintenance and upgrades.
The market's commercial direction depends on factory investment, production volumes, labor availability, product complexity, quality requirements and the economics of automation. Cutting precision, digital pattern preparation, programmable stitching and automated handling can improve material utilization and production consistency. However, the return on equipment investment varies by factory scale, product mix, labor costs and utilization rates.
Footwear Manufacturing Machine Market Drivers
Factory Productivity and Repeatability Support Investment in Automated Equipment
Footwear manufacturers operate under pressure to control unit costs while meeting quality and delivery requirements. Automated or programmable machines can standardize repeatable operations, reduce manual handling and help factories maintain consistent output across shifts.
The mechanism differs by process. Digital cutting systems can follow stored patterns; programmable stitching equipment can repeat defined operations; and automated handling can reduce the need to reposition components manually. These capabilities may lower rework and improve production planning, although actual benefits depend on machine utilization, operator skills and the quality of upstream materials.
For machinery suppliers, the commercial opportunity is strongest when equipment produces measurable improvements in throughput, material yield, defect rates or labor allocation. Buyers are less likely to justify higher-cost systems where production volumes are low or product variation requires frequent manual intervention.
Asia's Manufacturing Concentration Sustains a Large Equipment-Service Base
Asia's 88.7% share of global footwear production in 2025 indicates that a large proportion of manufacturing capacity is concentrated in the region. China, India and Vietnam are important production centers, while other Asian economies participate in export-oriented footwear supply chains.
This concentration creates a broad installed base for new machinery, replacement equipment, spare parts, repairs and process upgrades. Demand does not depend only on construction of new factories: existing producers may replace obsolete machines, add capacity for new product lines or upgrade specific bottleneck operations.
The limitation is that high production volume does not automatically translate into equivalent machinery-market growth. Factories may increase output by extending shifts, improving scheduling or using existing equipment more intensively. Equipment spending also varies with export orders, margins, financing conditions and manufacturers' confidence in future demand.
Shorter Product Cycles Increase the Value of Flexible Production Equipment
Footwear producers frequently need to accommodate changes in style, material, sizing and construction. A factory designed exclusively for long production runs may struggle when product ranges diversify or buyers require smaller batches and faster changes.
Digital pattern preparation, programmable machine settings and flexible cutting systems can shorten setup activities and reduce dependence on physical tooling for certain operations. Such equipment is useful when manufacturers must switch between designs without sacrificing accuracy or throughput.
However, flexibility comes with trade-offs. Digital systems may require software integration, operator training and higher initial investment. Not all construction methods can be automated economically, and highly customized or premium footwear may continue to require skilled manual work.
Quality Control and Material Utilization Encourage Precision Machinery
Footwear production uses materials with different thicknesses, stretch characteristics, surface finishes and cutting requirements. Poor cutting, stitching or assembly can lead to defects, wasted materials and inconsistent fit.
Precision machinery can help standardize dimensions, repeat stitching paths and control selected process parameters. Better cutting layouts can also reduce scrap where materials and pattern geometry allow optimization.
The commercial benefit is tied to avoided waste and rework, not simply to machine speed. Buyers need to evaluate whether the savings justify acquisition and operating costs. Results can vary according to material quality, maintenance, operator practices and the complexity of the product.
New Footwear Production Capacity Creates Demand for Equipment and Commissioning
Investment in additional factories, production lines or new product categories can require cutting, stitching, lasting, bottoming, molding and finishing equipment. New installations may also require layout design, utilities, operator training, spare-parts planning and commissioning.
India's footwear industry provides an example of a manufacturing ecosystem with potential equipment requirements. A July 2025 government release reported approximately 15,000 footwear manufacturing units in the country as of 2024, including leather and non-leather producers, and identified major clusters such as Agra, Kanpur, Chennai, Ranipet, Ambur and Kolkata. This establishes a substantial production base, but does not quantify the amount spent on footwear machinery.
Footwear Manufacturing Machine Market Restraints
Capital Costs and Uncertain Utilization Can Delay Automation Projects
Automatic cutting, handling and assembly systems generally require more upfront investment than basic manual equipment. A buyer must also consider installation, training, software, tooling, maintenance and possible production disruption during commissioning.
The payback period depends on utilization, labor savings, defect reduction and product mix. A factory with stable, high-volume production may justify automation more readily than a smaller producer handling irregular orders. When demand is volatile, manufacturers may delay investment or choose semi-automatic equipment that requires less capital.
Product Diversity Limits End-to-End Automation
Footwear includes products with different materials, shapes, construction techniques and quality expectations. A machine optimized for one process may not handle every design efficiently, while automation across several stages may require customized tooling and complex integration.
This limits the economics of universal production lines. Equipment suppliers must often offer configurable systems or specialized machines rather than assume that a single solution can automate the entire factory. Highly variable products may still rely on skilled operators at particular stages.
Maintenance, Downtime and Skills Affect Total Ownership Costs
Machinery downtime can interrupt production schedules and delay delivery commitments. Factories may depend on specialized technicians, proprietary parts or supplier support to repair advanced systems. Software faults and calibration issues can create additional challenges for digitally controlled equipment.
These costs can reduce the advantage of automation if local service coverage is weak. Suppliers with accessible spare parts, responsive technicians, preventive-maintenance programs and practical operator training may be better positioned than competitors that focus only on equipment sales.
Competition from Lower-Cost Equipment Constrains Premium Pricing
Footwear machinery buyers can compare equipment from established European and Asian manufacturers, local producers and suppliers of refurbished machines. Some buyers prioritize precision, service and long-term reliability; others focus on acquisition price and immediate production needs.
This creates pressure on suppliers to justify premium prices through measurable productivity, lower operating costs, reliability or specialized capabilities. Manufacturers that cannot demonstrate a clear economic advantage may lose orders to lower-cost alternatives.
Factory Investment Is Sensitive to Footwear Demand and Trade Conditions
Machinery is a capital good, and orders can be postponed when footwear manufacturers face weaker consumer demand, excess capacity, uncertain export orders or tighter credit. Trade policy changes and shifts in sourcing can also influence where production is expanded or reduced.
The effect is not uniform across the market. Some factories may pause new installations while investing in maintenance or retrofits; others may add equipment when customers shift orders toward their production locations. Machinery demand therefore depends on the geographic distribution and economics of footwear production, not solely on global footwear consumption.
Footwear Manufacturing Machine Market Opportunities
Retrofitting and Modernization of Existing Production Lines
Factories do not always need to replace an entire line to improve performance. Upgrades to cutting systems, programmable controls, sensors, drives, handling equipment or selected process stages can improve productivity while preserving usable equipment.
Retrofitting may be attractive where factory space is limited or capital budgets do not support full automation. Suppliers can develop recurring revenue through installation, spare parts, software updates, calibration and maintenance. The commercial challenge is ensuring that new components integrate safely and reliably with older equipment.
Flexible Automation for Small and Medium-Sized Manufacturers
Smaller producers often need a balance between labor productivity, machine flexibility and investment cost. Semi-automatic machines, modular workstations and entry-level digital cutting systems may offer a practical route to modernization without requiring a fully automated factory.
Suppliers can differentiate through simpler installation, financing options, training, local service and equipment that can be expanded in stages. This opportunity depends on whether the customer has sufficient production volume and skilled staff to use the equipment effectively.
Digital Cutting, Pattern Preparation and Production Data
Digital workflows can connect pattern design, cutting instructions and production planning. Where implemented well, this can reduce repeated manual setup, improve traceability and help managers identify bottlenecks or material waste.
The opportunity extends beyond hardware sales to software, integration, training and ongoing support. However, digitalization requires compatible file formats, reliable data, operator adoption and process discipline. Equipment vendors must avoid promising savings that cannot be demonstrated for the customer's materials and production mix.
Machinery for Non-Leather and Performance Footwear
Footwear manufacturers increasingly produce varied combinations of textiles, synthetic materials, foams, polymers and other components. Different materials can require different cutting, joining, molding and finishing methods.
Suppliers that can handle varied material properties and construction techniques may serve manufacturers diversifying beyond conventional leather footwear. The opportunity is process-specific: a machine that works well on one material may need different tooling or operating parameters for another.
After-Sales Services and Production Optimization
Installed machinery creates a continuing requirement for preventive maintenance, repair, calibration, replacement parts, operator training and process optimization. Service contracts can provide more recurring revenue than one-time equipment sales and help suppliers maintain relationships with factories.
Remote diagnostics and connected equipment may allow earlier identification of selected faults, but the benefits depend on sensor availability, connectivity, data quality and technician response. Service models should be designed around actual uptime and maintenance outcomes.
Segmental Analysis
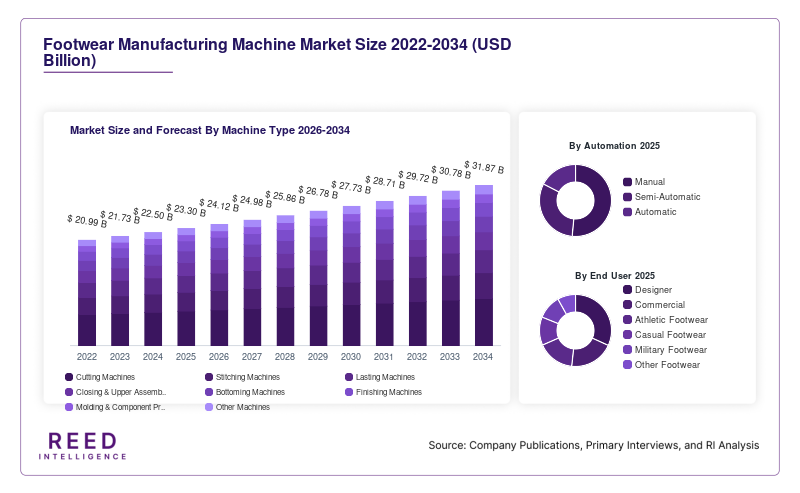
The segment shares, market values, CAGRs and 2034 estimates in this section are internal analytical allocations, not independently published segment forecasts. Shares are modeled against the supplied 2025 market value of USD 23.30 billion. The 2034 values are allocations of the supplied USD 31.87 billion forecast, with modeled shares summing to 100% within each segmentation. The indicative CAGRs describe the modeled movement between each allocated 2025 and 2034 value; they should not be presented as observed or externally verified market estimates.
By Machine Type
Cutting Machines represent approximately 22% of the 2025 market, equivalent to about USD 5.13 billion under the internal allocation. The segment is modeled at an indicative CAGR of approximately 3.7%, reaching about USD 7.10 billion by 2034. Cutting equipment is important because material preparation affects throughput, dimensional accuracy and waste. Digitally controlled systems may be especially useful for factories managing multiple sizes, patterns and materials, although the economics depend on utilization and the value of material saved.
Stitching Machines represent approximately 18% of the 2025 market, equivalent to about USD 4.19 billion. The segment is modeled to reach approximately USD 5.79 billion by 2034, implying an indicative CAGR of about 3.7%. Stitching machinery serves a broad range of upper-assembly operations. Demand depends on production volumes, construction methods, seam quality and the need to handle varied materials. Programmable systems can improve repeatability, while specialist and manual equipment remains relevant for complex or low-volume work.
Lasting Machines account for an estimated 14% of the 2025 market, or about USD 3.26 billion. The allocation reaches approximately USD 4.51 billion by 2034, corresponding to an indicative CAGR of about 3.7%. Lasting equipment shapes uppers around lasts and influences fit, form and consistency. Investment depends on footwear construction, factory throughput and the degree to which a manufacturer can standardize production across styles and sizes.
Closing & Upper Assembly Machines represent approximately 12% of the 2025 market, equivalent to about USD 2.80 billion. The segment is modeled to reach USD 3.86 billion by 2034, at an indicative CAGR of about 3.7%. These machines support joining and assembly operations before final shoe construction. Product complexity and material compatibility influence equipment choice, making specialized configuration and operator skills important purchase considerations.
By Automation
Manual Machines represent approximately 25% of the 2025 market, equivalent to about USD 5.83 billion. The segment is modeled to reach approximately USD 7.73 billion by 2034, implying an indicative CAGR of about 3.2%. Manual equipment remains relevant where capital budgets are constrained, volumes are modest or operators need direct control over specialized tasks. Its competitive position depends on acquisition cost, ease of maintenance and the value of skilled labor.
Semi-Automatic Machines represent approximately 40% of the 2025 market, equivalent to about USD 9.32 billion. The segment is modeled to reach approximately USD 12.88 billion by 2034, corresponding to an indicative CAGR of about 3.7%. Semi-automatic systems offer a middle ground between manual production and full automation. They can improve repeatability while retaining operator flexibility, making them attractive to factories modernizing selected production stages.
Automatic Machines represent approximately 35% of the 2025 market, equivalent to about USD 8.16 billion. The segment is modeled to reach approximately USD 11.59 billion by 2034, implying an indicative CAGR of about 4.0%. Automatic equipment may gain share where production volumes, labor costs and process standardization justify higher investment. Its adoption remains constrained by integration costs, product diversity, maintenance requirements and the need for trained technical personnel.
By End User
Designer Manufacturers represent approximately 15% of the 2025 market, equivalent to about USD 3.50 billion. The segment is modeled to reach approximately USD 4.83 billion by 2034, at an indicative CAGR of about 3.7%. Designer-led manufacturers may prioritize flexibility, precision, sampling speed and specialized construction rather than maximum output alone. Equipment suppliers can serve this segment with configurable machinery, short-run production solutions and strong technical support.
Commercial Manufacturers represent approximately 85% of the 2025 market, equivalent to about USD 19.81 billion. The segment is modeled to reach approximately USD 27.37 billion by 2034, implying an indicative CAGR of about 3.7%. Commercial producers require machinery for larger-scale production of athletic, casual, military and other footwear. Their investment decisions typically emphasize throughput, unit costs, repeatability, delivery schedules and total cost of ownership.
Within commercial manufacturing, athletic footwear is an important application because complex constructions and varied materials can require specialized cutting, stitching, molding and assembly operations. Casual footwear spans a broad range of price points and production methods, supporting demand for both standard and flexible equipment. Military footwear may require durable construction and controlled quality, while other commercial categories include occupational, fashion and specialist footwear. These subcategories are included within the commercial allocation above and are not separately additive market shares.
By Application
Leather Footwear represents approximately 35% of the 2025 market, equivalent to about USD 8.16 billion. The segment is modeled to reach approximately USD 11.27 billion by 2034, corresponding to an indicative CAGR of about 3.7%. Leather footwear production requires equipment suited to cutting, stitching, shaping and finishing materials with varying thickness and surface characteristics. Product quality and material yield influence equipment requirements, although the processes differ across formal, casual and specialist footwear.
Non-Leather Footwear represents approximately 30% of the 2025 market, equivalent to about USD 6.99 billion. It is modeled to reach approximately USD 9.66 billion by 2034, at an indicative CAGR of about 3.7%. This category includes footwear made from synthetic materials, textiles and other non-leather inputs. Machinery requirements vary by material behavior, bonding method and product design, creating opportunities for configurable cutting, stitching and assembly systems.
Sports & Performance Footwear represents approximately 25% of the 2025 market, equivalent to about USD 5.83 billion. The segment is modeled to reach approximately USD 8.37 billion by 2034, implying an indicative CAGR of about 4.1%. Performance footwear can involve layered textiles, foam components, molded parts and specialized sole structures. Equipment suppliers may benefit from demand for precision, repeatability and integration across component-preparation and assembly operations. This is an analytical growth assumption rather than a separately reported forecast.
By Service Type
Installation & Commissioning represents approximately 20% of the 2025 market, equivalent to about USD 4.66 billion under the internal allocation. It is modeled to reach approximately USD 6.44 billion by 2034, at an indicative CAGR of about 3.7%. These services cover equipment setup, integration, testing and readiness for production. Their value is particularly important for automated systems and factories introducing new process configurations.
Maintenance & Repair represents approximately 50% of the 2025 market, equivalent to about USD 11.65 billion. It is modeled to reach approximately USD 16.10 billion by 2034, corresponding to an indicative CAGR of about 3.7%. Maintenance and repair support machine uptime and production continuity. The segment's commercial importance increases with installed equipment, although the reported market allocation depends on whether services are included within the overall market definition.
Retrofitting & Upgrades represents approximately 30% of the 2025 market, equivalent to about USD 6.99 billion. The segment is modeled to reach approximately USD 9.66 billion by 2034, at an indicative CAGR of about 3.7%. Upgrades can extend equipment life and improve selected operations without replacing an entire line. Demand depends on the age of the installed base, compatibility with new controls and the expected savings from modernization.
Regional Analysis
The regional shares and values below are internal analytical allocations, not independently reported regional market estimates. They are modeled to sum to the supplied global market totals. The distribution is informed by the geography of footwear manufacturing, but machine-market revenue also depends on equipment production, imports, machine prices, local supplier presence and service revenues.
North America Footwear Manufacturing Machine Market
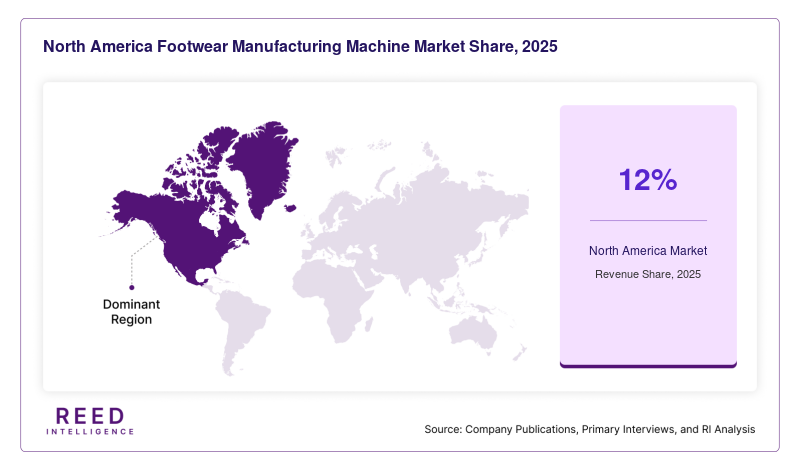
North America is modeled to represent approximately 12% of the 2025 market, equivalent to about USD 2.80 billion. It is modeled to reach approximately USD 3.86 billion by 2034, implying an indicative CAGR of about 3.7%.
The regional market includes equipment used by domestic footwear manufacturers, specialist producers, design-led operations and factories serving particular commercial or performance categories. Investment can focus on productivity, precision, specialized production, prototyping and replacement of older equipment rather than only on large-scale expansion.
The business case for automation depends on labor costs, production volume, product specialization and the ability to compete with imported footwear. Suppliers with strong technical support and equipment suited to specialized or flexible production can be relevant even when regional footwear output is much smaller than Asia's.
Europe Footwear Manufacturing Machine Market
Europe is modeled to represent approximately 18% of the 2025 market, equivalent to about USD 4.19 billion. The allocation reaches approximately USD 5.79 billion by 2034, at an indicative CAGR of about 3.7%.
European machinery demand is associated with equipment manufacturing, high-value footwear production, specialist applications, technology development and modernization of existing production lines. Some buyers may prioritize precision, process control, energy efficiency and integration with established factory systems.
European equipment suppliers also compete internationally. Their commercial position depends on engineering quality, service reach, innovation and the ability to justify equipment prices through productivity or quality improvements. The region's share of machinery demand should not be inferred directly from its share of footwear output, since equipment sales and production locations are different measures.
APAC Footwear Manufacturing Machine Market
APAC is modeled to represent approximately 52% of the 2025 market, equivalent to about USD 12.12 billion. It is modeled to reach approximately USD 17.70 billion by 2034, the largest regional value in this allocation, with an indicative CAGR of about 4.3%.
The region's importance is supported by its concentration of footwear manufacturing. The World Footwear Yearbook 2026 reports that Asia produced 88.7% of global footwear in 2025, with China, India and Vietnam among the leading producers. This installed production base supports demand for new machines, replacement equipment, maintenance and upgrades.
Demand varies by market. Large export-oriented factories may invest in high-throughput equipment and process integration, while smaller producers may adopt individual machines or semi-automatic systems. India's broad footwear manufacturing base and regional production clusters also provide a potential customer base for machinery suppliers, though public sector-level unit counts do not directly measure machinery expenditure.
APAC's modeled growth reflects its production scale and potential for factory modernization. Actual market growth will depend on export demand, labor and capital costs, equipment replacement cycles and the ability of manufacturers to fund upgrades.
Middle East and Africa Footwear Manufacturing Machine Market
Middle East and Africa are modeled to account for approximately 6% of the 2025 market, equivalent to about USD 1.40 billion. The allocation reaches approximately USD 1.93 billion by 2034, implying an indicative CAGR of about 3.7%.
The regional market includes equipment used by local footwear manufacturers, specialist producers and businesses serving domestic or regional demand. Potential demand may arise from factory investment, modernization and efforts to build or expand local production capabilities.
Market development is likely to vary significantly across countries. The availability of skilled technicians, financing, spare parts and dependable service networks affects machinery adoption. Suppliers that offer practical training and maintainable equipment may be better positioned in markets where advanced technical support is less accessible.
LATAM Footwear Manufacturing Machine Market
LATAM is modeled to represent approximately 12% of the 2025 market, equivalent to about USD 2.80 billion. It is modeled to reach approximately USD 3.86 billion by 2034, corresponding to an indicative CAGR of about 3.7%.
Regional demand is linked to domestic footwear manufacturing, replacement of older machines, production efficiency and the requirements of manufacturers serving local and export markets. Brazil and Mexico are relevant footwear-producing countries, while market conditions differ across the region.
Equipment purchasing may be influenced by currency movements, financing costs, import prices and the availability of local maintenance. Modular upgrades and semi-automatic equipment can be practical where manufacturers need to improve productivity but cannot justify complete production-line automation.
Competitive Landscape
The Footwear Manufacturing Machine Market includes specialist machinery manufacturers, suppliers of cutting and stitching systems, providers of integrated production equipment and companies offering maintenance, retrofits and related technical services. Competition is based on machine reliability, production precision, throughput, automation capability, compatibility with materials and construction methods, and after-sales support.
European manufacturers are represented by companies with expertise in specialized machinery and industrial process engineering. Asian manufacturers compete across a broad range of equipment, including products aimed at high-volume factories and price-sensitive customers. Local distributors and service providers can influence purchase decisions because downtime and spare-parts availability are important to footwear production.
Key Market Players
- ALC Tecnologie Adesive
- Atom S.p.A.
- Brustia Alfameccanica
- Comelz
- Dongguan Kingstone Shoe-making Machinery
- Gusbi
- Orisol
- True Ten Industrial
- Kou Yi Iron Works
- Desma
- MACHINERY SYSTEMS
- Shoe Systems Plus
Recent Market Developments
- In July 2026, World Footwear reported that global footwear production remained broadly stable in 2025 at 24.6 billion pairs. Asia accounted for 88.7% of production, with China, India and Vietnam among the leading producers. Stable global output suggests that machinery demand may depend more on factory modernization, equipment replacement and productivity improvements than on broad-based increases in footwear volumes alone. Asia's production concentration continues to make the region a priority for equipment suppliers and service networks.
- In June 2026, India's Press Information Bureau reported that leather and footwear exports reached USD 4.75 billion in fiscal year 2025–26, with Tamil Nadu accounting for USD 1.59 billion, or nearly 37% of sector exports. Export-oriented manufacturing activity can support demand for production equipment, replacement machines and process improvements. However, export growth alone does not establish how much machinery will be purchased; equipment demand depends on capacity utilization, new investment and the degree of local value addition.
Footwear Manufacturing Machine Market Segments
By Machine Type
- Cutting Machines
- Stitching Machines
- Lasting Machines
- Closing & Upper Assembly Machines
- Bottoming Machines
- Finishing Machines
- Molding & Component Preparation Machines
- Other Machines
By Automation
- Manual
- Semi-Automatic
- Automatic
By End User
- Designer
- Commercial
- Athletic Footwear
- Casual Footwear
- Military Footwear
- Other Footwear
By Application
- Leather Footwear
- Non-Leather Footwear
- Sports & Performance Footwear
- Other Applications
By Service Type
- Installation & Commissioning
- Maintenance & Repair
- Retrofitting & Upgrades
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM