Agricultural Bio Fungicide Market Size, Share Demand Report By Type (Microbial Bio Fungicides, Botanical Bio Fungicides, Biochemical Bio Fungicides), By Application (Foliar Spray, Seed Treatment, Soil Treatment) By Region & Segment Forecasts, 2026–2034
USD 3950
Agricultural Bio Fungicide Market Size
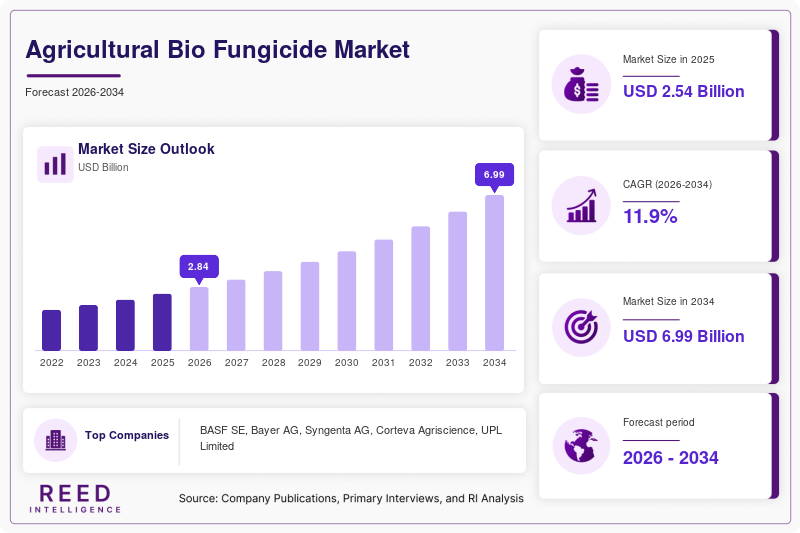
Agricultural Bio Fungicide market size is projected at USD 2.84 billion in 2026 and is expected to hit USD 6.97 billion by 2034 with a CAGR of 11.90%. The market is witnessing increasing investments in sustainable crop protection solutions, supported by rising demand for residue-free agricultural products across more than 190 countries. The report evaluates market segmentation, production capacity, consumption volume, pricing trends, and competitive landscape across major agricultural economies.
The Agricultural Bio Fungicide market refers to biologically derived fungal disease control products developed from microorganisms, plant extracts, and naturally occurring biochemical compounds. Global production exceeded 425 thousand metric tons in 2025, while adoption across commercial farming operations surpassed 34% in high-value crop cultivation. Cereals and grains accounted for nearly 38% of total consumption, while fruits and vegetables contributed approximately 42% of market demand. Growing restrictions on synthetic fungicides and increasing organic farming acreage continue to strengthen Agricultural Bio Fungicide market adoption worldwide.
Agricultural Bio Fungicide Market Trends
Rising Adoption of Microbial-Based Crop Protection Technologies
The use of microbial strains such as Bacillus subtilis, Trichoderma harzianum, and Pseudomonas fluorescens continues to expand across global agriculture. In 2025, microbial bio fungicide production exceeded 210 thousand metric tons, representing nearly 49% of total market volume. Adoption rates among commercial greenhouse growers increased from 26% in 2022 to 39% in 2025. Precision agriculture integration and biological compatibility with integrated pest management systems continue to support Agricultural Bio Fungicide market trends.
Growing investments in biological crop protection research are accelerating innovation. More than USD 650 million was invested globally in biological crop protection R&D during 2025, while over 180 new formulations were under regulatory review. Demand from fruit, vegetable, and specialty crop producers increased by 14.7% year-over-year, supporting stronger Agricultural Bio Fungicide market trends.
Agricultural Bio Fungicide Market Drivers
Growing Demand for Sustainable and Organic Farming Practices
Global organic farmland surpassed 98 million hectares in 2025, increasing by 8.2% compared with the previous year. More than 72% of organic crop producers utilize biological disease management solutions, while synthetic fungicide restrictions expanded across over 45 countries. Demand for residue-free produce increased by 12.4%, encouraging greater adoption of bio-based alternatives. These factors continue to accelerate Agricultural Bio Fungicide market growth.
Agricultural Bio Fungicide Market Restraints
Limited Shelf Life and Performance Variability
Many biological formulations have shelf lives ranging from 12 to 24 months compared with over 36 months for synthetic alternatives. Performance fluctuations of 10%–20% may occur due to environmental conditions such as temperature, humidity, and soil composition. Additionally, regulatory approval timelines often exceed 18–24 months in several regions, slowing commercialization and limiting Agricultural Bio Fungicide market expansion.
Agricultural Bio Fungicide Market Opportunities
Expansion of High-Value Crop Cultivation
Global fruit and vegetable cultivation exceeded 2.1 billion metric tons in 2025, creating substantial opportunities for biological disease management products. Protected cultivation areas expanded by 6.8%, while greenhouse farming increased by 7.5% annually. Specialty crop producers report up to 30% reduction in disease incidence through integrated biological solutions, creating favorable Agricultural Bio Fungicide market opportunities.
Challenges in Agricultural Bio Fungicide Market
Farmer Awareness and Distribution Network Limitations
Despite increasing demand, awareness levels remain below 50% among small-scale farmers in developing economies. Distribution coverage for biological crop protection products remains nearly 35% lower than synthetic alternatives in several agricultural regions. Inadequate storage infrastructure and technical training continue to create barriers, resulting in ongoing challenges for Agricultural Bio Fungicide market development.
Agricultural Bio Fungicide Market Segmentation
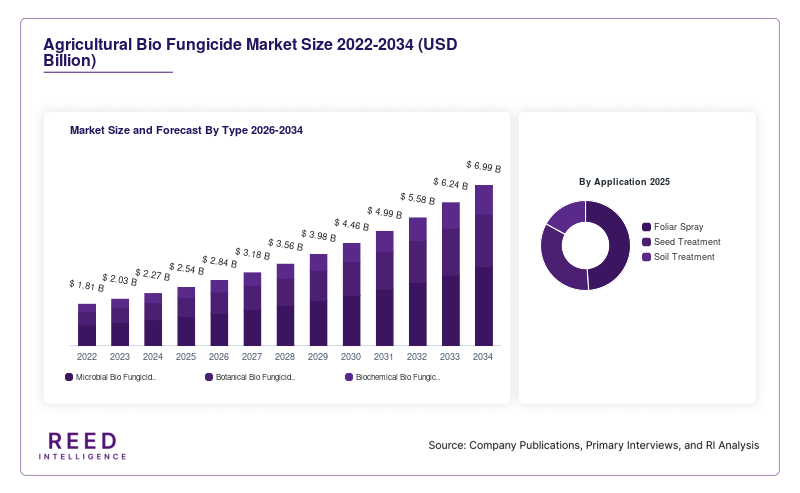
The market is segmented by type and application, with microbial products accounting for approximately 49% of global revenue and foliar spray applications contributing nearly 44% of overall demand. Increasing biological disease control adoption across cereals, fruits, vegetables, and plantation crops continues to strengthen segment growth.
By Type
Microbial products represent approximately 49% market share and generated more than 210 thousand metric tons of production volume during 2025. These products utilize beneficial microorganisms and offer disease suppression rates ranging from 70% to 92% under optimized conditions.
Botanical formulations account for nearly 29% of global demand. Production exceeded 125 thousand metric tons in 2025, driven by increased utilization of neem extracts, essential oils, and plant-derived antifungal compounds. Adoption rates among organic farms exceeded 41%.
Biochemical products contribute approximately 22% of market volume. Production surpassed 90 thousand metric tons in 2025, supported by advancements in fermentation technology and improved formulation stability. Disease control efficacy ranges between 65% and 88% depending on crop type.
By Application
Foliar spray applications dominate with nearly 44% market share. More than 185 thousand metric tons of formulations were applied through foliar methods in 2025. Adoption rates exceed 50% in high-value fruit and vegetable cultivation due to rapid disease control and broad crop compatibility.
Seed treatment accounts for approximately 31% of market demand. More than 900 million hectares of cultivated land utilized treated seeds during 2025. Biological seed coatings improve germination rates by 8%–15% while reducing fungal disease incidence during early growth stages.
Soil treatment represents nearly 25% of market consumption. Applications exceeded 105 thousand metric tons globally in 2025. These products enhance root health, improve microbial diversity, and reduce soil-borne pathogen populations by up to 60% in intensive farming systems.
Agricultural Bio Fungicide Market Regional Outlook
North America Agricultural Bio Fungicide Market
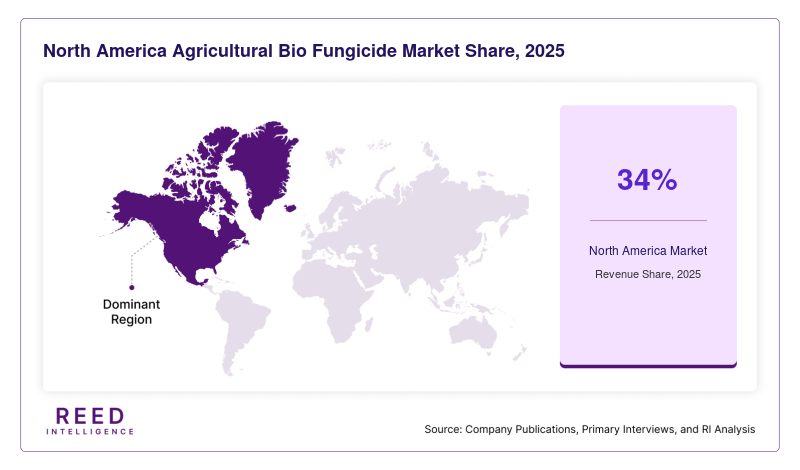
North America accounted for approximately 34% of global market revenue in 2025. The United States contributed nearly 78% of regional demand, supported by more than 2.3 million hectares of organic farmland. Canada represented approximately 15% of regional consumption, while biological fungicide adoption increased by 11.2% annually.
Europe Agricultural Bio Fungicide Market
Europe held nearly 29% market share. Germany, France, Italy, and Spain collectively contributed over 68% of regional demand. Organic farming acreage exceeded 19 million hectares, while biological crop protection product registrations increased by 9.4% during 2025.
Asia-Pacific Agricultural Bio Fungicide Market
Asia-Pacific represented approximately 27% of global consumption. China accounted for 36% of regional demand, followed by India at 24% and Japan at 11%. Agricultural production exceeding 4.8 billion metric tons annually and rising food security concerns continue to support market expansion.
Latin America Agricultural Bio Fungicide Market
Latin America contributed around 7% of global demand. Brazil represented nearly 52% of regional consumption, supported by large-scale soybean, sugarcane, and fruit cultivation. Organic crop acreage expanded by 6.3% in 2025.
Middle East & Africa Agricultural Bio Fungicide Market
The region accounted for approximately 3% market share. South Africa, Saudi Arabia, and the UAE remain key adopters. Protected agriculture investments increased by 8.7%, supporting demand for biological disease management products.
Top players in Agricultural Bio Fungicide Market
- BASF SE
- Bayer AG
- Syngenta AG
- Corteva Agriscience
- UPL Limited
- Certis Biologicals
- Koppert Biological Systems
- Novonesis
- Marrone Bio Innovations
- Valent BioSciences
- Andermatt Biocontrol
- Bioworks Inc.
- FMC Corporation
- Nufarm Limited
- Isagro S.p.A.
BASF SE
- Estimated market share: approximately 11%–13%.
- BASF maintains a strong position through extensive biological crop protection portfolios and global distribution networks.
- The company operates across more than 90 countries and invests significantly in sustainable agriculture technologies.
- Strong integration with digital farming platforms and broad crop protection offerings enhances competitive positioning.
- Continuous investments in microbial formulation technologies support long-term expansion across specialty crops and row crop applications.
Bayer AG
- Estimated market share: approximately 9%–11%.
- Bayer possesses a diversified agricultural solutions portfolio combining biological and conventional crop protection products.
- The company benefits from extensive research infrastructure and advanced formulation capabilities.
- Strategic partnerships with biotechnology firms support innovation in microbial and botanical fungicide development.
- Strong presence across North America, Europe, and Asia-Pacific contributes to sustained market leadership and customer reach.
Recent Developments in Agricultural Bio Fungicide Market
- 2025: BASF expanded biological crop protection production capacity to support increasing global demand.
- 2025: Bayer introduced new microbial fungicide formulations targeting fruit and vegetable diseases.
Agricultural Bio Fungicide Market Segments
By Type
- Microbial Bio Fungicides
- Botanical Bio Fungicides
- Biochemical Bio Fungicides
By Application
- Foliar Spray
- Seed Treatment
- Soil Treatment
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM