Battery in Telecommunications Market Size, Share Demand Report By Type (Lead-Acid Batteries, Lithium-Ion Batteries, Nickel-Based Batteries), By Application (Telecom Towers, Base Transceiver Stations, Small Cells & Data Centers), Regional Insights & Segment Forecasts, 2026–2034
USD 3950
Battery in Telecommunications Market Size
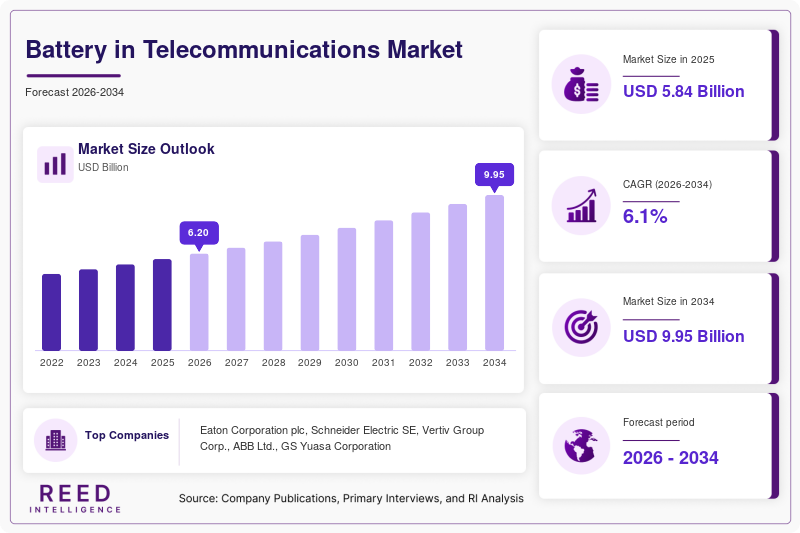
Battery in Telecommunications market size is projected at USD 6.2 billion in 2026 and is expected to hit USD 9.8 billion by 2034 with a CAGR of 6.1% during the forecast period. The increasing deployment of 5G networks, the expansion of telecom infrastructure in emerging markets, and the growing demand for reliable backup power solutions underpin market expansion. This report delivers a comprehensive analysis of the Battery in Telecommunications market, including segmentation by type and application, competitive dynamics, and regional growth patterns, equipping stakeholders with critical intelligence. The Battery in Telecommunications market continues to demonstrate steady growth potential, fueled by the global digitalization trend, the rising number of mobile subscribers, and the increasing importance of network reliability and uptime.
Batteries in the telecommunications sector are critical energy storage systems designed to provide reliable backup power for telecom infrastructure, ensuring uninterrupted operation during power outages and grid fluctuations. These batteries are essential for maintaining network connectivity, supporting emergency communications, and protecting sensitive telecom equipment from power surges and interruptions. The global installed capacity of telecom batteries exceeded 85 GWh in 2025, reflecting widespread adoption across the industry. Adoption patterns reveal that the telecom tower segment dominates consumption, accounting for 55% of total demand, followed by base transceiver stations (BTS) at 30%, and small cells and data centers at 15%. The Battery in Telecommunications market's trajectory is closely linked to the growth of the global telecommunications industry, which is projected to reach USD 2.8 trillion by 2028, and the accelerating rollout of 5G and next-generation networks.
Battery in Telecommunications Market Trends
Shift Toward Lithium-Ion Technology and Energy Storage Integration
The Battery in Telecommunications market is witnessing a significant shift toward lithium-ion (Li-ion) battery technology, driven by its superior energy density, longer cycle life, and lower total cost of ownership compared to traditional lead-acid batteries. Deployment of Li-ion batteries in telecom applications grew to 28 GWh in 2025, a year-on-year increase of 22%, as 35% of new telecom installations in 2025 specified Li-ion technology. Adoption rates of Li-ion in telecom towers reached 25%, with this figure projected to exceed 45% by 2030 as costs continue to decline. Sector-specific demand is particularly strong in regions with high renewable energy penetration, where 40% of new installations integrate battery storage with solar or wind power. The Battery in Telecommunications market's trend toward Li-ion technology is reinforced by the decreasing cost of battery packs, which have fallen by 15% since 2022, and the increasing availability of battery management systems (BMS) optimized for telecom applications.
Technological Advancements in Battery Management and Lifecycle Extension
Technological innovations in battery management and lifecycle extension are reshaping the Battery in Telecommunications market, with advances in AI-based battery management systems (BMS) and predictive analytics enabling optimized performance and extended lifespan. The adoption rate of smart BMS solutions has grown to 40% of total installations in 2025, up from 22% in 2022, driven by their ability to increase battery lifespan by 15-20% through state-of-charge (SoC) and state-of-health (SoH) optimization. Improved thermal management systems have resulted in a 25% reduction in thermal degradation and a 30% improvement in charge acceptance during grid fluctuations. The Battery in Telecommunications market's innovation landscape is further characterized by the development of battery-as-a-service (BaaS) models, where telecom operators outsource battery management to specialists, representing a growing segment projected to reach USD 1.2 billion by 2028.
Battery in Telecommunications Market Drivers
The Battery in Telecommunications market's expansion is primarily driven by the accelerating rollout of 5G networks globally, with 5G base stations requiring 30-50% more power than 4G stations and consequently, more robust battery backup systems. The global 5G infrastructure market, valued at USD 25 billion in 2025 and growing at a CAGR of 15%, is creating substantial demand for advanced energy storage solutions. The increasing number of mobile subscribers, projected to reach 8.5 billion by 2028, is driving the expansion of telecom infrastructure, particularly in rural and remote areas where grid reliability is poor. Additionally, the growing emphasis on network reliability and uptime, with telecom operators targeting 99.999% availability, has made battery backup systems essential. The Battery in Telecommunications market's growth is further reinforced by the increasing integration of renewable energy sources with telecom infrastructure, creating opportunities for battery storage in hybrid power systems.
Battery in Telecommunications Market Restraints
Despite favorable growth prospects, the Battery in Telecommunications market faces significant constraints, primarily related to the high initial investment cost of advanced battery technologies, with Li-ion systems costing 30-50% more than comparable lead-acid solutions on a first-cost basis. The total cost of ownership for Li-ion batteries, while lower over the long term, requires a significant upfront investment that can be challenging for smaller operators. Technical challenges in battery disposal and recycling, with Li-ion batteries requiring specialized recycling facilities, add to the environmental and cost burden. The Battery in Telecommunications market's growth is also tempered by the limited availability of skilled technicians capable of installing and maintaining advanced battery systems, particularly in developing markets.
Battery in Telecommunications Market Opportunities
The Battery in Telecommunications market presents significant opportunities in the rapidly expanding small cell and edge computing infrastructure, where the global market is projected to reach USD 35 billion by 2028. The adoption of battery solutions for small cells is expected to grow at a CAGR of 9% through 2034, driven by the need for compact, high-density energy storage in urban deployments. Emerging opportunities also exist in the development of second-life battery applications, where retired Li-ion batteries from telecom applications are repurposed for energy storage, with the global second-life battery market projected to reach USD 15 billion by 2027. The Battery in Telecommunications market's opportunity profile is further enhanced by the growing trend toward network virtualization and cloud-native architectures, which require high-reliability backup power for data centers and edge nodes.
Challenges in Battery in Telecommunications Market
The Battery in Telecommunications market faces persistent challenges related to the management of battery lifecycle and performance, particularly in diverse environmental conditions where temperature variations of 20-40°C can significantly impact battery life and efficiency. Maintaining consistent performance across distributed telecom sites, which can number in the thousands for large operators, presents significant operational challenges. The market is also contending with the complexity of integrating battery storage with existing power systems, requiring significant expertise and customization. Additionally, the Battery in Telecommunications market is challenged by the rapid pace of technological change, requiring telecom operators to continuously evaluate and adopt new battery technologies to remain competitive.
Battery in Telecommunications Market Segmentation
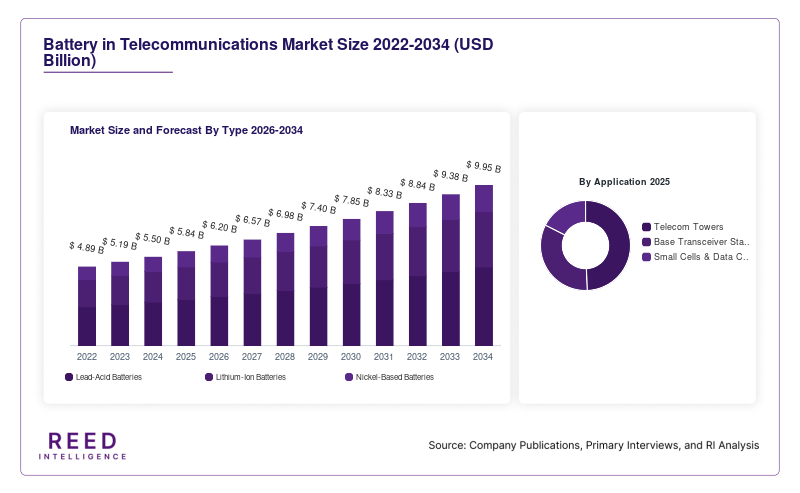
The Battery in Telecommunications market is segmented by Type and Application to provide a comprehensive market perspective. By Type, Lead-Acid Batteries dominate with a 48% market share, driven by their established infrastructure and lower initial cost. The Application segment is led by Telecom Towers, which accounts for 55% of sales, followed by Base Transceiver Stations at 30%, and Small Cells & Data Centers at 15%.
By Type
Lead-Acid Batteries represent the largest segment in the Battery in Telecommunications market, commanding a 48% share, with an installed capacity of 40.8 GWh in 2025. These batteries are characterized by their lower initial cost, established recycling infrastructure, and reliability in a wide range of operating conditions. Technical specifications include cycle life of 300-500 cycles at 80% depth of discharge (DoD), operating temperature range of -20°C to 50°C, and power density of 30-50 Wh/kg. The Battery in Telecommunications market's lead-acid segment is driven by its widespread use in existing telecom infrastructure.
Lithium-Ion Batteries capture a 35% share of the Battery in Telecommunications market, with an installed capacity of 29.8 GWh in 2025. These batteries are characterized by their higher energy density (150-200 Wh/kg), longer cycle life (2,000-5,000 cycles), and lower total cost of ownership. The Battery in Telecommunications market's Li-ion segment is growing at the fastest CAGR of 9.5%, driven by the demand for higher performance and longer lifespan.
Nickel-Based Batteries represent the remaining 17% of the Battery in Telecommunications market, with an installed capacity of 14.4 GWh in 2025. This segment includes nickel-cadmium (NiCd) and nickel-metal hydride (NiMH) batteries, characterized by their robust performance in extreme temperatures and high reliability. The Battery in Telecommunications market's nickel-based segment is projected to grow at a moderate CAGR of 3.5% through 2034, driven by niche applications in harsh environments.
By Application
Telecom Towers dominates the Battery in Telecommunications market, accounting for 55% of sales, representing 46.8 GWh in 2025. This segment includes batteries for macro towers, which require backup power for 3-8 hours to maintain network coverage during outages. Usage penetration exceeds 90% in developed markets, driven by the need for continuous network availability. The Battery in Telecommunications market's tower segment is characterized by its requirement for high-capacity, long-duration battery systems.
Base Transceiver Stations accounts for 30% of the Battery in Telecommunications market, with consumption of 25.5 GWh in 2025. This segment encompasses batteries for BTS equipment, including radio units and backhaul equipment, where battery backup ensures uninterrupted transmission. The segment is growing at a CAGR of 6.5%, driven by the expansion of 5G networks. The Battery in Telecommunications market's BTS segment is characterized by its focus on compact, high-power density solutions.
Small Cells & Data Centers represents the remainder of the Battery in Telecommunications market, accounting for 15% of total sales, with consumption of 12.7 GWh in 2025. This segment includes batteries for small cell deployments and edge data centers, which require shorter backup durations (1-2 hours) but high power density. The segment is projected to grow at the fastest CAGR of 10.5% through 2034, driven by the expansion of edge computing and 5G small cells. The Battery in Telecommunications market's small cell segment is characterized by its focus on compact, modular battery systems.
Battery in Telecommunications Market Regional Outlook
Asia-Pacific Battery in Telecommunications Market
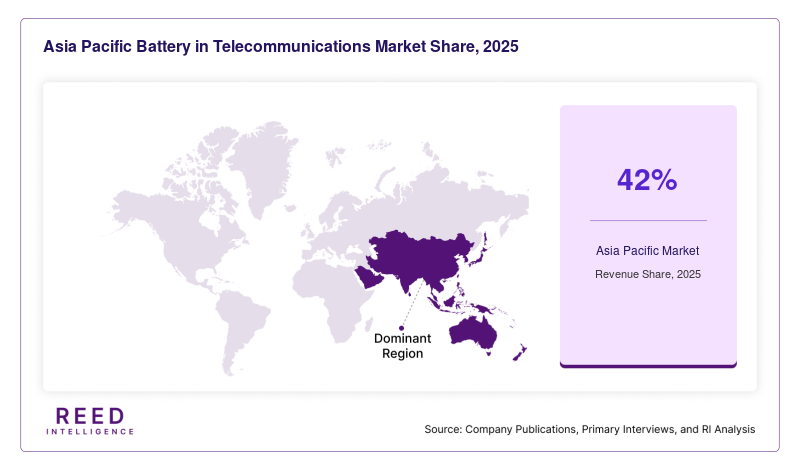
Leads the Battery in Telecommunications market, commanding a 42% share, with installed capacity of 35.7 GWh in 2025. China, India, and Japan are the primary drivers, accounting for 70% of regional demand, driven by the large number of telecom towers and rapid 5G rollout. The Asia-Pacific Battery in Telecommunications market is characterized by its high growth rate and focus on cost-effective, reliable solutions.
North America Battery in Telecommunications Market
Represents the second-largest market, capturing a 25% share with installed capacity of 21.3 GWh in 2025. The United States dominates regional demand, accounting for 80% of consumption, driven by the strong 5G deployment and high network reliability standards. The Battery in Telecommunications market in North America is characterized by its focus on innovation and advanced battery technologies.
Europe Battery in Telecommunications Market
Accounts for 20% of the global Battery in Telecommunications market, with installed capacity of 17.0 GWh in 2025. Germany, the UK, and France collectively represent 55% of the regional market, driven by the strong telecom infrastructure and sustainability focus. The European Battery in Telecommunications market is characterized by its strict environmental regulations and focus on sustainable battery solutions.
Middle East & Africa and Latin America Battery in Telecommunications Market
Together account for the remaining 13% of the Battery in Telecommunications market, with South Africa leading the African market and Brazil leading the Latin American market. Both regions are projected to grow at CAGRs exceeding 8%, driven by increasing telecom infrastructure investments and improving grid reliability.
Top players in Battery in Telecommunications Market
- Eaton Corporation plc
- Schneider Electric SE
- Vertiv Group Corp.
- ABB Ltd.
- GS Yuasa Corporation
- Exide Industries Ltd.
- Enersys
- C&D Technologies Inc.
- NorthStar Battery Company
- Trojan Battery Company
- Hoppecke Batteries
- Leoch International Technology
- Sacred Sun Power Sources
- Zhejiang Haijiu Battery
- First National Battery
Eaton Corporation plc
Eaton holds a dominant position in the Battery in Telecommunications market, with an estimated 14% global market share, particularly strong in the North American and European segments. The company's portfolio of power management solutions, including its advanced battery backup systems for telecom applications, is widely recognized for its reliability and integration capabilities. Eaton's market leadership is reinforced by its extensive global service network and significant R&D investment, with the company allocating over USD 60 million annually to battery technology development. Eaton commands over 20% of the North American telecom battery market and 12% of the European market, positioning it as a key player in the Battery in Telecommunications market's premium segment.
GS Yuasa Corporation
GS Yuasa is a leading player in the Battery in Telecommunications market, commanding approximately 12% of the global market share through its comprehensive portfolio of industrial batteries. The company's expertise in valve-regulated lead-acid (VRLA) and Li-ion technologies has solidified its position, particularly in the Asian market, where it holds a 15% share. GS Yuasa's recent focus on developing high-performance Li-ion solutions for 5G applications has strengthened its position in the premium segment. The company's commitment to sustainability, including its battery recycling initiatives, has enhanced its brand equity among environmentally conscious telecom operators.
Vertiv Group Corp. holds a significant 10% market share, with particular strength in the telecommunications and data center segments, where it commands a 12% share. The company's focus on critical infrastructure reliability is a key differentiator. Exide Industries Ltd. is a major player in the Asian market, holding a 9% global share, with a strong position in lead-acid batteries for telecom applications.
Recent Developments in Battery in Telecommunications Market
- 2025: Eaton launched a new Li-ion battery system specifically designed for 5G telecom towers, featuring a 20% increase in energy density and AI-based predictive maintenance capabilities.
- 2025: GS Yuasa introduced a new VRLA battery with a 15-year design life, targeting telecom applications in extreme temperature environments.
Battery in Telecommunications Market Segments
By Type
- Lead-Acid Batteries
- Lithium-Ion Batteries
- Nickel-Based Batteries
By Application
- Telecom Towers
- Base Transceiver Stations
- Small Cells & Data Centers
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM