Channel Magnets Market Size, Share, Demand Report By Type (Ferrite Channel Magnets, Neodymium Channel Magnets, Alnico Channel Magnets), By Application (Industrial Equipment, Retail & Display Systems, Automotive Components), By Region & Segment Forecasts, 2026–2034
USD 3950
Channel Magnets Market Size
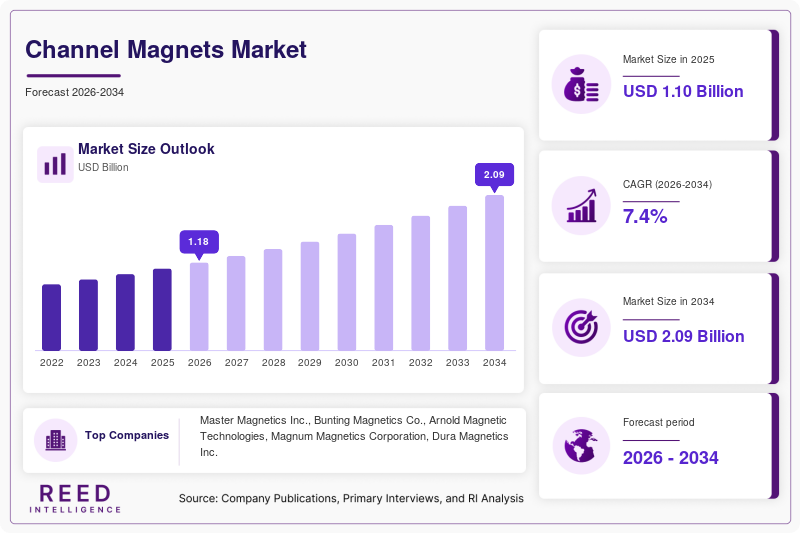
Channel Magnets market size is projected at USD 1.18 billion in 2026 and is expected to hit USD 2.09 billion by 2034 with a CAGR of 7.4%. The market is witnessing steady expansion due to increasing utilization of magnetic holding solutions across manufacturing, construction, logistics, retail displays, and automotive industries. Growing automation levels, industrial modernization, and demand for high-strength magnetic assemblies continue to influence purchasing patterns. Market participants are focusing on product innovation, material efficiency, and customized magnetic solutions to strengthen competitive positioning.
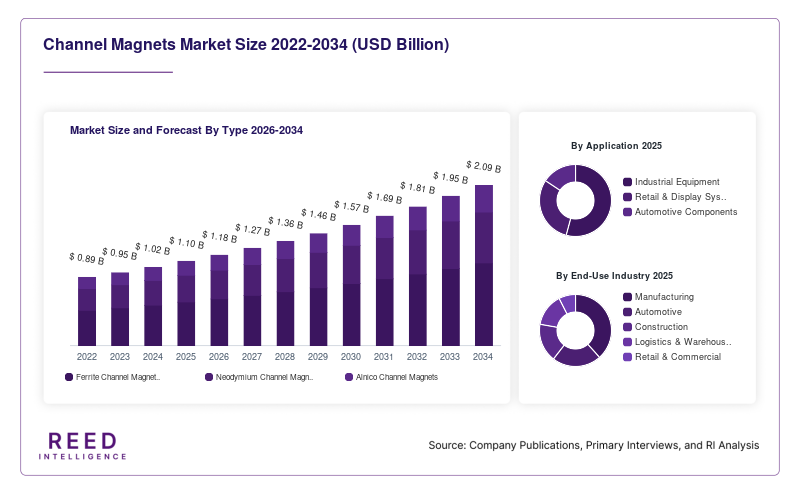
The channel magnets market consists of magnetic assemblies enclosed within steel channels to enhance magnetic strength and durability. Global production exceeded 1.6 billion units in 2025, with industrial applications accounting for approximately 46% of total demand. Retail and display systems contributed 28%, while automotive applications represented nearly 18%. More than 63% of manufacturing facilities utilize magnetic holding devices for assembly, positioning, and material handling operations, reinforcing Channel Magnets market insights.
Channel Magnets Market Trends
Rising Adoption of High-Strength Neodymium Magnetic Assemblies
Global production of neodymium-based channel magnets surpassed 620 million units in 2025, representing one of the fastest-growing product categories. Adoption rates increased by 14% across automated manufacturing facilities due to stronger magnetic force, compact size, and enhanced operational efficiency. Industrial automation investments exceeded USD 220 billion globally, supporting Channel Magnets market trends.
Manufacturers are increasingly integrating precision-engineered steel housings and corrosion-resistant coatings into channel magnet products. More than 41% of new channel magnet designs launched during 2025 featured improved holding capacities exceeding 150 kg. Demand from warehouse automation, robotics, and modular manufacturing systems increased by 16%, strengthening Channel Magnets market trends.
Channel Magnets Market Drivers
Expansion of Industrial Automation and Material Handling Systems
Industrial automation installations increased by 12% globally during 2025, while robotic deployments surpassed 620,000 units. More than 58% of automated assembly lines utilize magnetic positioning and holding systems. Demand for channel magnets in material handling applications exceeded 710 million units, accelerating Channel Magnets market growth.
Channel Magnets Market Restraints
Volatility in Rare Earth Material Prices
Neodymium and other rare earth material prices experienced fluctuations of 18% to 24% during 2025. Raw material costs account for nearly 45% of manufacturing expenses for premium channel magnets. Approximately 29% of suppliers reported procurement challenges associated with rare earth supply chains, impacting Channel Magnets market growth.
Channel Magnets Market Opportunities
Growth in Smart Manufacturing Facilities
Global investments in smart manufacturing exceeded USD 340 billion in 2025. More than 38% of newly established production facilities integrated magnetic holding and positioning technologies. Demand for precision magnetic assemblies increased by 17%, creating significant opportunities within the Channel Magnets market.
Challenges in Channel Magnets Market
Competition from Alternative Fastening Technologies
Mechanical fastening systems, vacuum holding technologies, and advanced adhesive solutions continue to compete with magnetic assemblies. Nearly 31% of industrial users evaluate alternative holding methods based on application requirements. Maintaining cost competitiveness while improving magnetic performance remains a key challenge affecting Channel Magnets market demand.
Channel Magnets Market Segmentation
The market is segmented by type and application. Neodymium channel magnets accounted for approximately 48% of total revenue in 2025, followed by ferrite channel magnets at 34% and alnico channel magnets at 18%. Industrial equipment applications dominated with 46% share, while retail and display systems and automotive components accounted for 28% and 18%, respectively.
By Type
Ferrite channel magnets represented approximately 34% of market revenue. Production exceeded 540 million units in 2025. These products offer magnetic strengths ranging from 20 kg to 80 kg and are widely utilized in cost-sensitive industrial and commercial applications. Their corrosion resistance and affordability continue to support demand.
Neodymium channel magnets accounted for nearly 48% of total revenue. Production exceeded 770 million units globally. These magnets provide holding forces above 150 kg and magnetic energy products exceeding 35 MGOe. Their use continues to expand across automation, robotics, and precision manufacturing systems.
Alnico channel magnets held approximately 18% market share with production exceeding 290 million units annually. These products offer superior temperature resistance up to 500°C and are frequently used in specialized industrial environments requiring thermal stability.
By Application
Industrial equipment accounted for approximately 46% of market revenue. Consumption exceeded 730 million units during 2025. Adoption penetration surpassed 61% across assembly operations, machine tooling, material handling systems, and manufacturing fixtures due to high reliability and ease of integration.
Retail and display systems represented nearly 28% of total demand. More than 450 million units were utilized in merchandising displays, signage systems, and exhibition structures. Adoption rates increased by 11% due to flexible installation requirements and reusable magnetic mounting solutions.
Automotive applications accounted for approximately 18% of market revenue. Consumption exceeded 290 million units globally. Channel magnets are used in sensors, assembly fixtures, manufacturing tooling, and vehicle component positioning systems, supporting efficiency improvements across automotive production lines.
Channel Magnets Market Regional Outlook
North America Channel Magnets Market
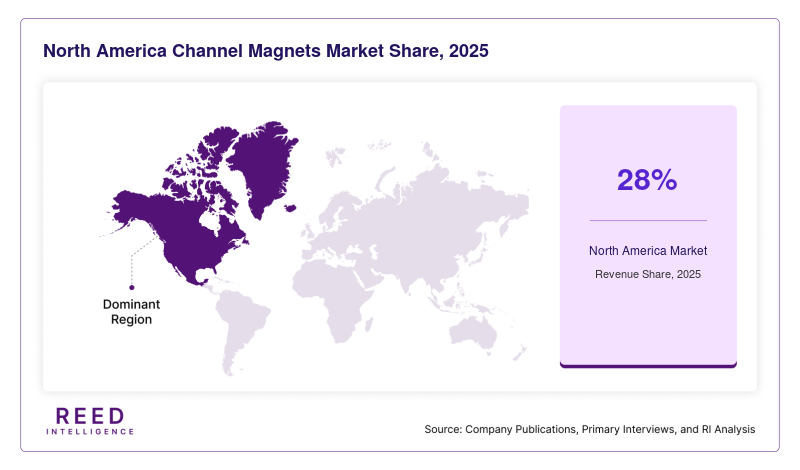
North America accounted for approximately 28% of global revenue in 2025. The United States represented nearly 80% of regional demand. Production and consumption exceeded 450 million units, supported by industrial automation investments and manufacturing modernization initiatives.
Europe Channel Magnets Market
Europe held approximately 25% market share. Germany, France, Italy, and the United Kingdom collectively contributed over 66% of regional demand. More than 400 million channel magnets were consumed across manufacturing, automotive, and commercial sectors during 2025.
Asia-Pacific Channel Magnets Market
Asia-Pacific dominated the market with approximately 40% share. China accounted for nearly 51% of regional demand, followed by Japan at 15% and India at 13%. Regional production exceeded 760 million units due to extensive manufacturing activity and rare earth material availability.
Latin America Channel Magnets Market
Latin America represented approximately 4% of global revenue. Brazil contributed nearly 48% of regional demand, while Mexico accounted for 31%. Consumption exceeded 65 million units during 2025, supported by industrial expansion and logistics infrastructure development.
Middle East & Africa Channel Magnets Market
The Middle East & Africa region accounted for approximately 3% of total market revenue. Saudi Arabia, the UAE, and South Africa collectively represented over 57% of regional demand. Industrial diversification projects continue to support channel magnet adoption.
Top players in Channel Magnets Market
- Master Magnetics Inc.
- Bunting Magnetics Co.
- Arnold Magnetic Technologies
- Magnum Magnetics Corporation
- Dura Magnetics Inc.
- Eclipse Magnetics Ltd.
- Stanford Magnets
- Adams Magnetic Products Co.
- Goudsmit Magnetics Group
- Ningbo Permanent Magnetics Co., Ltd.
- Electron Energy Corporation
- Dexter Magnetic Technologies
- Magnet Applications Inc.
- AIC Magnetics Ltd.
- Magswitch Technology Inc.
Master Magnetics Inc.
- Estimated market share: 13%–15%.
- Master Magnetics maintains a strong presence in industrial, commercial, and retail magnetic product segments.
- The company offers an extensive portfolio of channel magnets, magnetic assemblies, and custom-engineered solutions.
- Annual production capacity supports hundreds of millions of units across multiple end-use industries.
- Strong distribution networks and product innovation capabilities enhance competitive positioning.
- Continuous investments in manufacturing efficiency and product customization support long-term expansion.
Bunting Magnetics Co.
- Estimated market share: 10%–12%.
- Bunting Magnetics is a leading supplier of industrial magnetic products with a significant presence in material handling and automation applications.
- The company serves manufacturing, recycling, automotive, and processing industries globally.
- Advanced engineering expertise enables development of high-performance magnetic assemblies and customized channel magnets.
- Strategic investments in automation and product development strengthen market leadership.
- Broad geographic reach and strong customer relationships support sustained growth.
Recent Developments in Channel Magnets Market
- 2026: Manufacturers introduced high-strength neodymium channel magnets with enhanced corrosion-resistant coatings.
- 2025: Industrial automation suppliers expanded integration of magnetic holding solutions within robotic production systems.
- 2025: Several companies increased production capacities to address growing demand from manufacturing facilities.
Channel Magnets Market Segments
By Type
- Ferrite Channel Magnets
- Neodymium Channel Magnets
- Alnico Channel Magnets
By Application
- Industrial Equipment
- Retail & Display Systems
- Automotive Components
By End-Use Industry
- Manufacturing
- Automotive
- Construction
- Logistics & Warehousing
- Retail & Commercial
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM