Crawler Material Handler Market Size, Share Demand Report By Type (Small Crawler Material Handlers, Medium Crawler Material Handlers, Large Crawler Material Handlers), By Application (Construction, Mining, Waste Management), By End-User Industry (Infrastructure Development, Mining & Quarrying, Recycling & Waste Processing, Ports & Material Handling Facilities) By Region & Segment Forecasts, 2026–2034
USD 3950
Crawler Material Handler Market Size
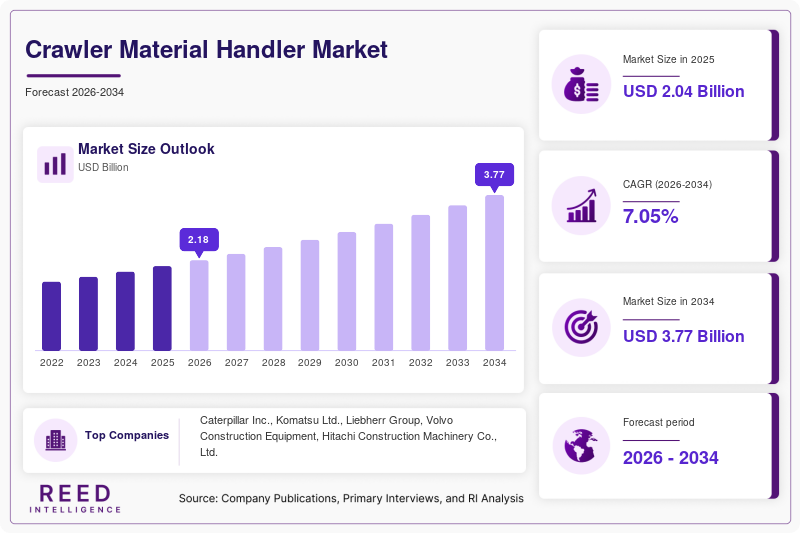
Crawler Material Handler market size is projected at USD 2.18 billion in 2026 and is expected to hit USD 3.76 billion by 2034 with a CAGR of 7.05%. Rising infrastructure development, expansion of mining operations, and increasing adoption of tracked equipment in challenging terrains are supporting industry expansion. The report provides detailed analysis of market segmentation, equipment demand, production capacity, technological advancements, and competitive landscape across global markets.
The Crawler Material Handler market includes specialized tracked machines designed for handling, sorting, loading, and transferring heavy materials across construction sites, ports, recycling facilities, and mining operations. Increasing demand for high-reach machines, improved fuel efficiency, and automated operating systems is accelerating adoption. The study evaluates production volumes, regional penetration, pricing trends, and strategic developments shaping the Crawler Material Handler market.
Crawler Material Handler Market Trends
Increasing Adoption of Electrification and Smart Equipment Technologies
The integration of telematics, automation, and hybrid power systems is transforming crawler material handling equipment. More than 38,000 crawler material handlers were produced globally in 2025, with advanced models accounting for approximately 32% of total shipments. Manufacturers are introducing remote monitoring systems, fuel optimization technologies, and AI-based operational controls to improve productivity by 15% to 25%. The demand for smart construction equipment continues to influence Crawler Material Handler trends.
Growing investments in sustainable construction and mining operations are increasing demand for low-emission machinery. Electric and hybrid crawler material handlers recorded adoption growth of nearly 18% annually, particularly in Europe and Asia-Pacific. Approximately 41% of large contractors are evaluating alternative power solutions to reduce operating costs and carbon emissions. These technology shifts are strengthening long-term opportunities in the Crawler Material Handler market.
Crawler Material Handler Market Drivers
Expansion of Construction and Mining Infrastructure Projects
Rapid infrastructure development across emerging economies is a major factor driving market expansion. Global construction equipment investments exceeded USD 230 billion in 2025, while mining equipment demand increased by approximately 9.6%. Asia-Pacific accounted for nearly 45% of new infrastructure-related machinery demand, with China and India contributing more than 60% of regional consumption. Increased requirement for heavy material handling solutions in large-scale projects continues to drive the Crawler Material Handler market.
Crawler Material Handler Market Restraints
High Initial Investment and Maintenance Costs
Crawler material handlers require significant capital investment compared with wheeled alternatives. Average equipment prices range between USD 180,000 and USD 750,000 depending on capacity, attachments, and technology features. Maintenance expenses contribute nearly 18% to 25% of total ownership costs over the machine lifecycle. Small contractors often face financing challenges, limiting adoption in price-sensitive markets and creating restraints for the Crawler Material Handler market.
Crawler Material Handler Market Opportunities
Growing Demand for Recycling and Waste Processing Equipment
Increasing global focus on waste recycling is creating new opportunities for crawler material handlers. Global waste processing activities generated demand for more than 12,000 specialized handling machines in 2025. Recycling facilities accounted for approximately 22% of new equipment purchases, supported by government sustainability initiatives. The development of automated sorting attachments and energy-efficient systems provides significant opportunities for the Crawler Material Handler market.
Challenges in Crawler Material Handler
Supply Chain Disruptions and Component Availability Issues
The market faces challenges due to fluctuations in raw material prices, semiconductor shortages, and supply chain interruptions. Steel and hydraulic component costs increased by approximately 8% during 2025, affecting equipment manufacturing expenses. Around 35% of manufacturers reported delays in component availability during recent years. These challenges impact production schedules, pricing strategies, and overall competitiveness of the Crawler Material Handler market.
Crawler Material Handler Market Segmentation
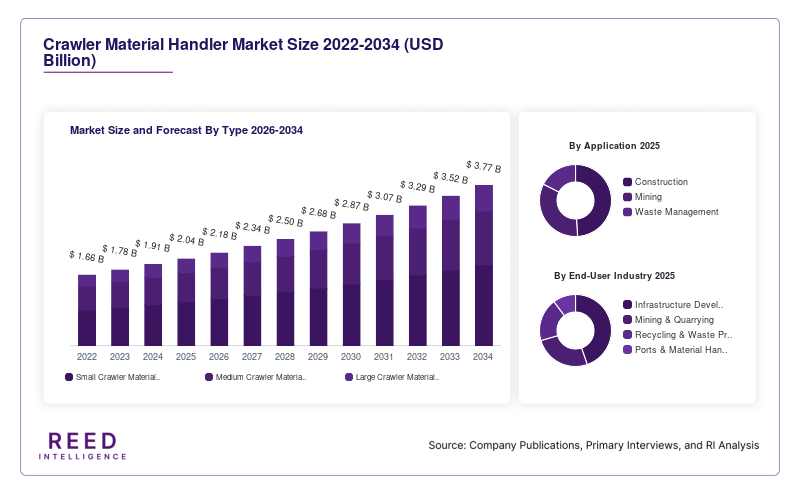
The Crawler Material Handler market is segmented by type and application. Large crawler material handlers dominated the market with nearly 42% revenue share in 2025 due to their extensive use in mining and heavy industrial applications. Construction remained the leading application segment, contributing approximately 48% of total demand.
By Type
Small crawler material handlers accounted for approximately 24% of market revenue in 2025. Global production exceeded 9,000 units annually. These machines typically feature operating capacities below 20 tons, compact dimensions, and enhanced mobility for urban construction projects, landscaping, and small recycling facilities.
Medium crawler material handlers represented nearly 34% market share. Production reached approximately 13,000 units in 2025. These machines generally operate within the 20–40 ton capacity range and provide balanced performance for construction, forestry, and material sorting applications.
Large crawler material handlers dominated with around 42% market share. Annual production exceeded 16,000 units globally. These machines offer lifting capacities above 40 tons, extended reach capabilities, and heavy-duty hydraulic systems designed for mining, ports, and large-scale industrial operations.
By Application
Construction applications accounted for approximately 48% of market demand. More than 18,000 crawler material handlers were deployed across global construction projects in 2025. Increasing urbanization, infrastructure development, and commercial building activities have increased adoption by nearly 11% annually. These machines support excavation, loading, demolition, and material transportation operations.
Mining represented nearly 32% of market revenue. Global mining operations utilized more than 12,000 crawler material handlers during 2025. High-capacity machines are preferred for handling minerals, ores, and bulk materials due to their stability and performance in challenging environments.
Waste management contributed approximately 20% of total market demand. More than 7,500 units were deployed in recycling centers, landfill operations, and waste processing facilities. Growing recycling targets and environmental regulations are increasing equipment adoption across developed and developing economies.
Crawler Material Handler Market Regional Outlook
North America Crawler Material Handler Market
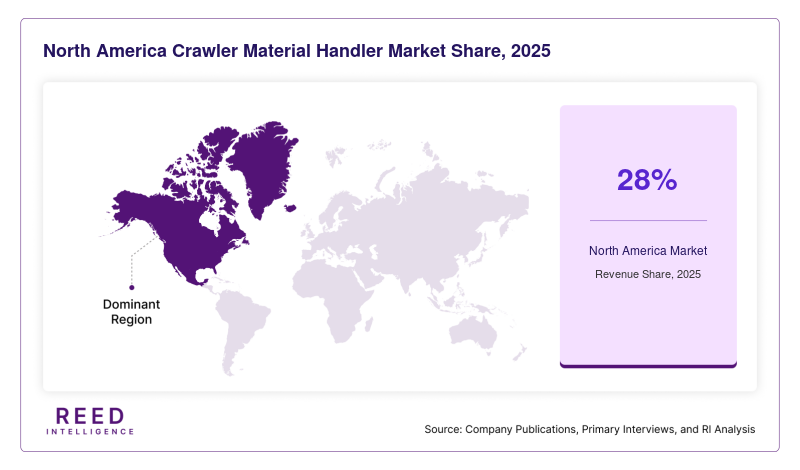
North America accounted for approximately 28% of global revenue in 2025. The United States contributed nearly 75% of regional demand due to strong construction activities, mining operations, and waste recycling investments. More than 10,000 crawler material handlers were sold across the region, with mining and recycling applications representing over 55% of consumption.
Europe Crawler Material Handler Market
Europe represented nearly 26% of global market share. Germany, the United Kingdom, France, and Italy were major contributors, collectively accounting for more than 65% of regional demand. Approximately 9,500 units were deployed in 2025, supported by environmental regulations and increasing adoption of energy-efficient machinery.
Asia-Pacific Crawler Material Handler Market
Asia-Pacific dominated with approximately 34% market share. China, Japan, India, and South Korea were key contributors. Regional production exceeded 20,000 units annually, driven by infrastructure expansion, mining investments, and industrial development. China alone accounted for nearly 48% of regional equipment demand.
Latin America Crawler Material Handler Market
Latin America held around 8% market share. Brazil, Chile, and Mexico generated more than 70% of regional demand. Mining operations contributed nearly 60% of crawler material handler usage, supported by mineral extraction activities.
Middle East & Africa Crawler Material Handler Market
The Middle East & Africa accounted for approximately 4% of global revenue. Infrastructure projects and mining activities supported demand growth, with Saudi Arabia, UAE, and South Africa representing major markets.
Top players in Crawler Material Handler Market
- Caterpillar Inc.
- Komatsu Ltd.
- Liebherr Group
- Volvo Construction Equipment
- Hitachi Construction Machinery Co., Ltd.
- Doosan Bobcat Inc.
- Sennebogen Maschinenfabrik GmbH
- Terex Corporation
- Hyundai Construction Equipment Co., Ltd.
- Kobelco Construction Machinery Co., Ltd.
- JCB
- Sumitomo Construction Machinery
Caterpillar Inc.
- Holds an estimated market share of approximately 15%–18%.
- Maintains a leading position through a broad portfolio of heavy construction and mining equipment.
- The company focuses on advanced hydraulic systems, fuel-efficient engines, and digital fleet management solutions.
- Strong dealer networks across North America, Europe, and Asia-Pacific support global penetration.
- Continuous investment in autonomous and sustainable machinery strengthens its competitive positioning in the Crawler Material Handler market.
Liebherr Group
- Holds an estimated market share of approximately 10%–13%.
- Recognized for high-performance material handling equipment used in ports, mining, and industrial applications.
- The company emphasizes precision engineering, extended-reach technology, and low-emission solutions.
- Strong European presence combined with global manufacturing capabilities supports market expansion.
- Innovation in automation and operator assistance systems enhances Liebherr’s position in the Crawler Material Handler market.
Recent Developments in Crawler Material Handler Market
- 2026: Manufacturers introduced upgraded crawler material handlers featuring enhanced telematics and remote monitoring capabilities.
- 2025: Major equipment companies expanded electric and hybrid crawler machinery portfolios for sustainable operations.
- 2025: New high-reach models were launched for recycling and port material handling applications.
Crawler Material Handler Market Segments
By Type
- Small Crawler Material Handlers
- Medium Crawler Material Handlers
- Large Crawler Material Handlers
By Application
- Construction
- Mining
- Waste Management
By End-User Industry
- Infrastructure Development
- Mining & Quarrying
- Recycling & Waste Processing
- Ports & Material Handling Facilities
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM