Power Station Fans Market Size, Share Demand Report By Type (Axial Flow Fans, Centrifugal Fans, Mixed Flow Fans), By Application (Coal-Fired Power Plants, Gas-Fired Power Plants, Nuclear Power Plants, Renewable Energy Plants), Regional Insights & Segment Forecasts, 2026–2034
USD 3950
Power Station Fans Market Size
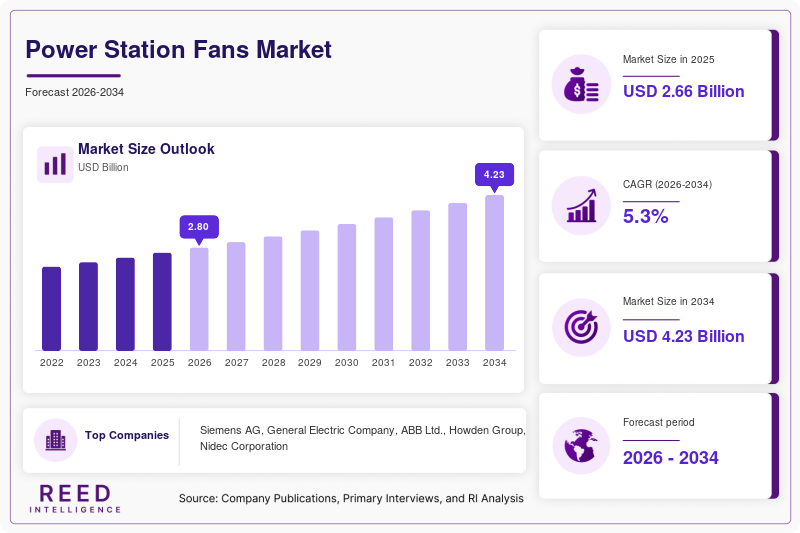
Power Station Fans market size is projected at USD 2.8 billion in 2026 and is expected to hit USD 4.2 billion by 2034 with a CAGR of 5.3% during the forecast period. The increasing global demand for electricity, the expansion of power generation infrastructure, and the need for efficient and reliable equipment in power plants underpin market expansion. This report delivers a comprehensive analysis of the Power Station Fans market, including segmentation by type and application, competitive dynamics, and regional growth patterns, equipping stakeholders with critical intelligence. The Power Station Fans market continues to demonstrate steady growth potential, fueled by the global energy transition, the modernization of aging power plants, and the increasing focus on operational efficiency and emission reduction.
Power station fans are critical industrial fans used in thermal power plants to handle large volumes of air and flue gases for various processes, including combustion air supply, flue gas desulfurization, and air pollution control. These fans are essential for the efficient and safe operation of power plants, ensuring proper airflow for combustion, cooling, and emission control systems. The global production volume of power station fans exceeded 125,000 units in 2025, reflecting a 3.5% increase from 2022. Adoption patterns reveal that the axial flow fan segment dominates the market, accounting for 42% of total demand, followed by centrifugal fans at 38%, and mixed flow fans at 20%. The Power Station Fans market's trajectory is closely linked to the global power generation industry, which is projected to grow at a CAGR of 3.5% through 2034, and the increasing emphasis on reducing emissions and improving plant efficiency.
Power Station Fans Market Trends
Growing Demand for High-Efficiency and Low-Emission Fans
The Power Station Fans market is witnessing a significant trend toward the adoption of high-efficiency fan technologies that reduce energy consumption and support lower emission targets. The adoption rate of high-efficiency fans with advanced aerodynamic designs has grown to 35% of new installations in 2025, up from 20% in 2022, driven by the need to meet stringent environmental regulations and reduce operating costs. The use of variable speed drives (VSD) and advanced control systems has also gained traction, with 25% of new installations incorporating these technologies to optimize fan performance and reduce energy consumption by 15-20%. The Power Station Fans market's trend toward efficiency is reinforced by the increasing focus on reducing the carbon footprint of power generation and the global push for cleaner energy production.
Increasing Focus on Fan Reliability and Predictive Maintenance
The increasing focus on operational reliability and the adoption of predictive maintenance technologies is a major trend shaping the Power Station Fans market, as operators seek to minimize downtime and extend the life of critical equipment. The market has seen a 30% increase in the adoption of condition monitoring systems and predictive maintenance tools since 2022, with 20% of new fan installations in 2025 incorporating such technologies. Sector-specific demand is particularly strong in mature markets like Europe and North America, where 30% of power plant operators have implemented condition-based monitoring for their fans. The Power Station Fans market's trend toward reliability is reinforced by the decreasing cost of sensor technology, the increasing availability of cloud-based analytics, and the growing recognition of the financial benefits of predictive maintenance in reducing unscheduled downtime.
Power Station Fans Market Drivers
The Power Station Fans market's expansion is primarily driven by the increasing global demand for electricity, which is projected to grow by 3.5% annually through 2034, creating a need for new power generation capacity and associated equipment. The global power generation market, valued at USD 1.5 trillion in 2025 and growing at a CAGR of 4.5%, is the primary engine for fan demand. The need to modernize aging power plants, particularly in developed markets, has also been a major driver, with significant investment in retrofitting and upgrading existing fan systems to improve efficiency and reliability. Additionally, the growing focus on reducing emissions and meeting stringent environmental regulations has driven the adoption of advanced fan systems for pollution control. The Power Station Fans market's growth is further reinforced by the increasing investment in renewable energy plants, which also require specialized fan systems for cooling and ventilation.
Power Station Fans Market Restraints
Despite favorable growth prospects, the Power Station Fans market faces significant constraints, primarily related to the high capital cost of large-scale, high-performance fan systems and the long lead times for custom-engineered solutions. The cost of a large axial fan can range from USD 500,000 to over USD 2 million, representing a significant investment for power plant operators. The complexity of integrating new fan systems with existing power plant control and balance-of-plant systems can also be a constraint. The Power Station Fans market's growth is also tempered by the competition from alternative technologies and the increasing focus on demand-side management and energy efficiency.
Power Station Fans Market Opportunities
The Power Station Fans market presents significant opportunities in the rapidly expanding renewable energy sector, particularly in large-scale solar and wind power plants, where the global market is projected to reach USD 500 billion by 2028. The adoption of specialized fan systems for cooling and ventilation in these plants is expected to grow at a CAGR of 8% through 2034. Emerging opportunities also exist in the development of fans for carbon capture and storage (CCS) systems and other emission control technologies. The Power Station Fans market's opportunity profile is further enhanced by the growing trend toward digitalization and Industry 4.0, creating demand for smart fans with integrated sensors and connectivity.
Challenges in Power Station Fans Market
The Power Station Fans market faces persistent challenges related to the management of fan performance in harsh operating conditions, including high temperatures, corrosive gases, and abrasive fly ash, which can lead to erosion and reduced service life. Maintaining consistent fan performance over long operating cycles, with fans often running continuously for years, requires robust design and materials. The market is also contending with the complexity of meeting diverse power plant and regulatory requirements, with significant variation across regions and fuel types. Additionally, the Power Station Fans market is challenged by the need for skilled engineers and technicians for design, installation, and maintenance.
Power Station Fans Market Segmentation
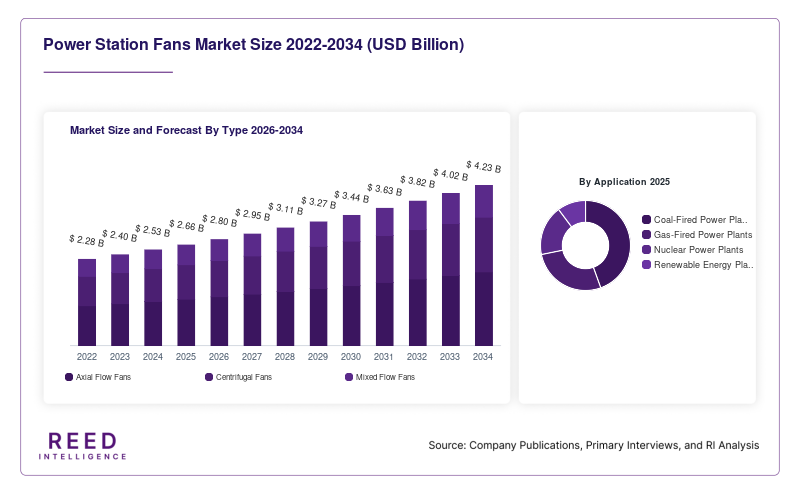
The Power Station Fans market is segmented by Type and Application to provide a comprehensive market perspective. By Type, Axial Flow Fans dominate with a 42% market share, driven by their high efficiency and suitability for large air volumes. The Application segment is led by Coal-Fired Power Plants, which accounts for 45% of the market, followed by Gas-Fired Power Plants at 28%, Nuclear Power Plants at 15%, and Renewable Energy Plants at 12%.
By Type
Axial Flow Fans represent the largest segment in the Power Station Fans market, commanding a 42% share, with production reaching 52,500 units in 2025. These fans are characterized by their high efficiency at low to medium pressure, ability to handle large air volumes, and suitability for forced draft and induced draft applications. Technical specifications include blade diameters of 1-6 meters, flow rates of 100-1,000 m³/s, and pressures of 1-5 kPa. The Power Station Fans market's axial segment is driven by its widespread use in combustion air supply and flue gas applications.
Centrifugal Fans capture a 38% share of the Power Station Fans market, with production of 47,500 units in 2025. These fans are characterized by their ability to generate higher pressures, making them suitable for applications such as flue gas desulfurization and material handling. Technical specifications include wheel diameters of 1-4 meters, flow rates of 50-500 m³/s, and pressures of 5-20 kPa. The Power Station Fans market's centrifugal segment is growing at a steady CAGR, driven by the demand for high-pressure applications.
Mixed Flow Fans represent the remaining 20% of the Power Station Fans market, with production of 25,000 units in 2025. These fans combine features of axial and centrifugal fans, offering a balance between flow rate and pressure. The Power Station Fans market's mixed flow segment is growing at a moderate CAGR, driven by their versatility and compact design.
By Application
Coal-Fired Power Plants dominate the Power Station Fans market, accounting for 45% of sales, representing 56,250 units in 2025. This segment includes fans for combustion air, flue gas handling, and pollution control, where fans are essential for plant operation and emission compliance. Usage penetration exceeds 95% in operating coal plants. The Power Station Fans market's coal segment is characterized by its requirement for high-capacity, durable fans.
Gas-Fired Power Plants accounts for 28% of the Power Station Fans market, with sales of 35,000 units in 2025. This segment encompasses fans for combustion air and flue gas, where gas plants benefit from more favorable flue gas conditions. The segment is growing at a CAGR of 5.5%, driven by the shift toward cleaner fossil fuels. The Power Station Fans market's gas segment is characterized by its focus on efficiency and low maintenance.
Nuclear Power Plants represents 15% of the Power Station Fans market, with sales of 18,750 units in 2025. This segment includes fans for containment cooling and ventilation, where nuclear-grade quality and reliability are paramount. The segment is projected to grow at a steady CAGR of 4.5% through 2034, driven by the expansion of nuclear power. The Power Station Fans market's nuclear segment is characterized by its requirement for high reliability and specialized safety systems.
Renewable Energy Plants comprises the remainder of the Power Station Fans market, accounting for 12% of total sales, with 15,000 units in 2025. This segment includes fans for solar thermal plants, biomass plants, and geothermal plants, where fans are used for process cooling and ventilation. The segment is projected to grow at the fastest CAGR of 7.5% through 2034, driven by the growth of renewable energy. The Power Station Fans market's renewable segment is characterized by its focus on sustainability and innovation.
Power Station Fans Market Regional Outlook
Asia-Pacific Power Station Fans Market
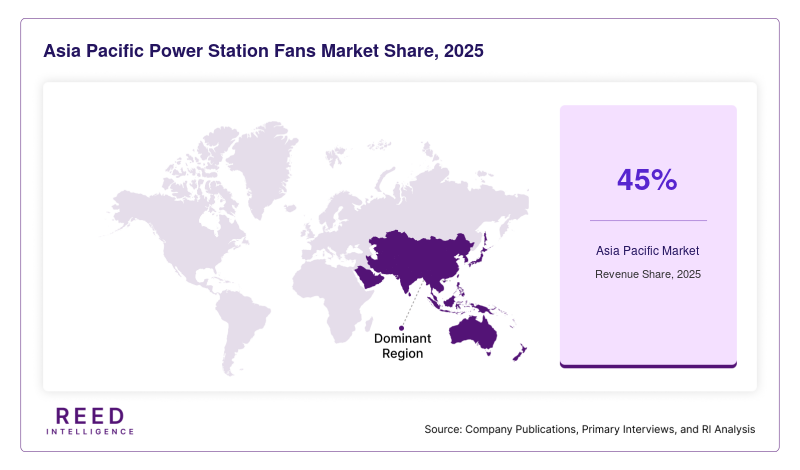
Leads the Power Station Fans market, commanding a 45% share, with a market value of USD 1.26 billion in 2025. China, India, and Japan are the primary drivers, accounting for 70% of regional demand, driven by the large coal-fired power fleet and the expansion of gas and renewable plants. The Asia-Pacific Power Station Fans market is characterized by its high growth rate and focus on cost-effective solutions.
North America Power Station Fans Market
Represents the second-largest market, capturing a 25% share with a value of USD 0.70 billion in 2025. The United States dominates regional demand, accounting for 80% of consumption, driven by the large gas-fired and nuclear power fleets. The Power Station Fans market in North America is characterized by its focus on innovation and efficiency.
Europe Power Station Fans Market
Accounts for 20% of the global Power Station Fans market, with a value of USD 0.56 billion in 2025. Germany, the UK, and France collectively represent 55% of the regional market, driven by the strong focus on energy transition and efficiency. The Power Station Fans market in Europe is characterized by its focus on sustainability and high-efficiency technologies.
Middle East & Africa and Latin America Power Station Fans Market
Together account for the remaining 10% of the Power Station Fans market, with Saudi Arabia leading the Middle East market and Brazil leading the Latin American market. Both regions are projected to grow at CAGRs exceeding 5%, driven by increasing power generation investments.
Top players in Power Station Fans Market
- Siemens AG
- General Electric Company
- ABB Ltd.
- Howden Group
- Nidec Corporation
- Gardner Denver Holdings, Inc.
- Ebm-papst Group
- Zhejiang Shanfeng Electric Equipment Co., Ltd.
- Shanghai Electric Fan Co., Ltd.
- Hudson Products Corporation
- Nova Fan (Wuxi) Co., Ltd.
- Robinson Fans, Inc.
- Fischbach + Möller (F+M) GmbH
- Kruger Ventilation Industries
- Greenheck Fan Corporation
Siemens AG
Siemens holds a dominant position in the Power Station Fans market, with an estimated 15% global market share, particularly strong in the European and North American segments. The company's portfolio of high-performance industrial fans, including advanced axial and centrifugal designs, is widely recognized for its quality, efficiency, and reliability. Siemens' market leadership is reinforced by its significant R&D investment in digitalization and efficiency, with the company allocating over EUR 50 million annually to fan technology development. Siemens commands over 20% of the European market and 12% of the North American market, positioning it as a key player in the Power Station Fans market's premium segment.
Howden Group
Howden is a leading player in the Power Station Fans market, commanding approximately 12% of the global market share through its comprehensive portfolio of heavy-duty industrial fans. The company's expertise in large-scale fan design and its strong presence in the power generation and industrial sectors have solidified its position, where it holds a 15% share. Howden's recent focus on developing high-efficiency fans with advanced materials for erosion resistance has strengthened its position in the premium segment. The company's commitment to innovation, evidenced by its investment in new aerodynamic designs, has enhanced its brand equity among power plant operators.
General Electric Company holds a significant 10% market share, with particular strength in the North American and Asian markets, where it commands a 12% share. The company's focus on integrated power plant solutions is a key differentiator. ABB Ltd. is a major player in the automation and control segment, holding a 9% global share, with a strong position in integrated fan systems.
Recent Developments in Power Station Fans Market
- 2025: Siemens AG launched a new line of high-efficiency axial fans for coal-fired power plants, featuring a 15% improvement in aerodynamic efficiency and a 20% reduction in noise levels.
- 2025: Howden Group announced a strategic partnership with a leading predictive maintenance software provider to develop a comprehensive condition monitoring system for power station fans.
Power Station Fans Market Segments
By Type
- Axial Flow Fans
- Centrifugal Fans
- Mixed Flow Fans
By Application
- Coal-Fired Power Plants
- Gas-Fired Power Plants
- Nuclear Power Plants
- Renewable Energy Plants
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM