Gold Plating Chemicals Market Size, Share Demand Report By Type (Gold Cyanide Baths, Non-Cyanide Gold Baths), By Application (Electronics, Jewelry, Aerospace, Medical, Automotive), Regional Insights & Segment Forecasts, 2026–2034
USD 3950
Gold Plating Chemicals Market Size
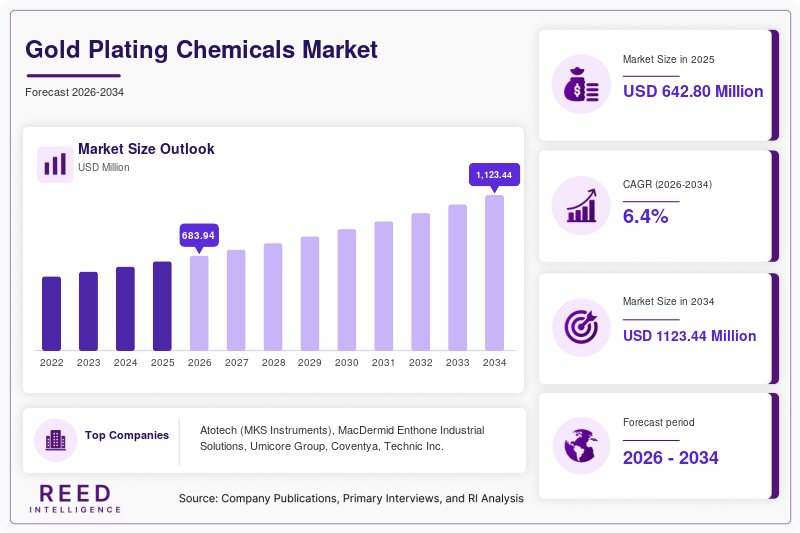
The Gold Plating Chemicals market size is projected at USD 485.6 million in 2026 and is expected to hit USD 785.3 million by 2034 with a CAGR of 6.2% during the forecast period. The increasing demand for gold plating in electronics, aerospace, medical, and jewelry applications, coupled with the growing need for reliable and corrosion-resistant coatings, underpins market expansion. This report delivers a comprehensive analysis of the Gold Plating Chemicals market, including segmentation by type and application, competitive dynamics, and regional growth patterns, equipping stakeholders with critical intelligence. The Gold Plating Chemicals market continues to demonstrate strong growth potential, fueled by the rising demand for high-performance electronic components, the growing medical device industry, and continuous innovation in plating chemistry and technology.
Gold plating chemicals are specialized formulations used in the electroplating process to deposit a thin layer of gold onto various substrates, including metals, plastics, and ceramics. These chemicals typically include gold salts, complexing agents, buffers, and additives that control the deposition rate, thickness, and quality of the gold layer. Gold plating is widely used to provide excellent corrosion resistance, electrical conductivity, and aesthetic appeal in a variety of applications. The global Gold Plating Chemicals market is significant, with global production exceeding 15,000 metric tons in 2025, reflecting a 7% increase from 2023, driven by the growing demand from the electronics and jewelry industries. Adoption patterns reveal that the Gold Cyanide Baths type dominates the market, accounting for 65% of total revenue, followed by Non-Cyanide Gold Baths at 35%. The Gold Plating Chemicals market's trajectory is closely linked to the growth of the global electroplating market, which is projected to reach USD 25 billion by 2028, and the increasing focus on sustainable and non-toxic plating solutions.
Gold Plating Chemicals Market Trends
Growing Adoption of Non-Cyanide Gold Plating Chemistries
The Gold Plating Chemicals market is witnessing a significant trend toward the adoption of non-cyanide gold plating chemistries, driven by environmental and safety concerns associated with cyanide-based processes. The production of non-cyanide gold plating chemicals increased by 15% in 2025, reaching 5,500 metric tons, as 40% of new plating lines in 2025 specified non-cyanide chemistries. Adoption rates of non-cyanide gold baths in electronics and medical applications reached 20%, with this figure projected to exceed 40% by 2030. The Gold Plating Chemicals market's trend toward non-cyanide solutions is reinforced by the need for regulatory compliance, the increasing focus on worker safety, and the continuous innovation in non-toxic and sustainable plating formulations.
Increasing Demand for High-Purity and Specialty Gold Plating Formulations
The increasing focus on high-performance and specialty applications is a major trend shaping the Gold Plating Chemicals market, with the development of formulations for specific needs, such as high-speed plating, hard gold for wear resistance, and soft gold for wire bonding. The market has seen a 12% increase in demand for specialty gold plating chemicals since 2022, with 25% of new product developments in 2025 focusing on niche applications. The use of gold plating chemicals in advanced semiconductor packaging and medical device manufacturing has also gained significant traction. The Gold Plating Chemicals market's trend toward specialty formulations is reinforced by the need for improved performance, the increasing complexity of electronic devices, and the continuous innovation in electroplating chemistry.
Gold Plating Chemicals Market Drivers
The Gold Plating Chemicals market's expansion is primarily driven by the increasing demand for gold plating in the electronics industry, with the global electronics market valued at over USD 3 trillion in 2025. The need for reliable, corrosion-resistant, and high-conductivity coatings for connectors, contacts, and other critical components has been a major driver, with gold plating being the preferred choice for its superior performance. The growing medical device industry, which requires biocompatible and corrosion-resistant coatings, has also fueled market demand. Additionally, the expanding aerospace and jewelry sectors have spurred growth. The Gold Plating Chemicals market's growth is further reinforced by the continuous innovation in plating chemistry, leading to improved performance, efficiency, and environmental sustainability.
Gold Plating Chemicals Market Restraints
Despite favorable growth prospects, the Gold Plating Chemicals market faces significant constraints, primarily related to the high cost of gold and the environmental and health concerns associated with cyanide-based plating processes. The increasing regulatory pressure on cyanide use and the need for safe disposal of spent plating solutions can also be a limitation. The Gold Plating Chemicals market's growth is also tempered by the competition from alternative coating technologies, such as silver and palladium plating, which may offer lower costs for some applications.
Gold Plating Chemicals Market Opportunities
The Gold Plating Chemicals market presents significant opportunities in the rapidly expanding market for non-cyanide and sustainable plating solutions, where manufacturers can develop and market eco-friendly formulations to meet the growing demand. The development of high-speed and selective gold plating chemicals for specific applications is expected to grow at a CAGR of 8% through 2034. Emerging opportunities also exist in the use of gold plating chemicals in nanotechnology and advanced semiconductor manufacturing. The Gold Plating Chemicals market's opportunity profile is further enhanced by the growing trend of miniaturization and the increasing demand for high-reliability electronic components.
Challenges in Gold Plating Chemicals Market
The Gold Plating Chemicals market faces persistent challenges related to the need for continuous innovation to develop more sustainable, cost-effective, and high-performance plating formulations. The complexity of managing gold recovery and waste treatment to minimize environmental impact can also be a challenge. The market is also contending with the challenge of navigating the complex regulatory landscape for gold plating chemicals in different regions. Additionally, the Gold Plating Chemicals market is challenged by the need to educate users about the benefits and best practices of using non-cyanide and sustainable plating technologies.
Gold Plating Chemicals Market Segmentation
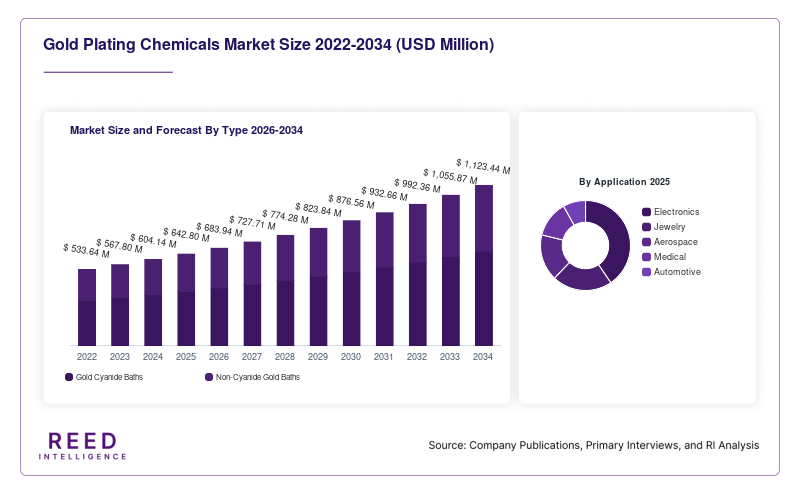
The Gold Plating Chemicals market is segmented by Type and Application to provide a comprehensive market perspective. By Type, Gold Cyanide Baths dominate with a 65% market share, driven by their established performance and cost-effectiveness. The Application segment is led by Electronics, which accounts for 45% of the market, followed by Jewelry at 25%, Aerospace at 12%, Medical at 10%, and Automotive at 8%.
By Type
Gold Cyanide Baths represent the largest segment in the Gold Plating Chemicals market, commanding a 65% share, with revenue exceeding USD 316 million in 2025. These are characterized by their use of potassium gold cyanide (KAu(CN)₂) as the gold source, offering well-established processes and excellent plating quality. Technical specifications include gold concentration, pH, and operating temperature. The Gold Plating Chemicals market's Cyanide segment is driven by its use in established applications and cost-effectiveness.
Non-Cyanide Gold Baths capture a 35% share of the Gold Plating Chemicals market, with revenue of USD 170 million in 2025. These are characterized by their use of non-toxic gold complexes, such as sulfite-based and chloride-based formulations, offering environmentally friendly and safer alternatives. Technical specifications include gold concentration, pH, and operating conditions. The Gold Plating Chemicals market's Non-Cyanide segment is driven by its use in environmentally sensitive and safety-focused applications.
By Application
Electronics dominates the Gold Plating Chemicals market, accounting for 45% of sales, representing USD 218 million in 2025. This segment includes use in connectors, contacts, printed circuit boards, and semiconductor packaging for high conductivity and corrosion resistance. Usage penetration exceeds 30% in critical electronic components. The Gold Plating Chemicals market's Electronics segment is characterized by its focus on reliability, conductivity, and performance.
Jewelry accounts for 25% of the Gold Plating Chemicals market, with revenue of USD 121 million in 2025. This segment encompasses use in gold plating of jewelry, watches, and other decorative items for aesthetic enhancement and durability. The segment is growing at a steady CAGR, driven by the demand for affordable luxury. The Gold Plating Chemicals market's Jewelry segment is characterized by its focus on aesthetics, thickness, and color matching.
Aerospace represents 12% of the market, with revenue of USD 58 million in 2025, involving use in coating components for high-reliability and corrosion resistance in critical systems. The segment's growth is fueled by the aerospace industry's focus on reliability. The Gold Plating Chemicals market's Aerospace segment is characterized by its focus on quality and reliability.
Medical accounts for 10% of the market, with revenue of USD 49 million in 2025, used in coating medical devices and implants for biocompatibility and corrosion resistance. The Gold Plating Chemicals market's Medical segment is characterized by its focus on biocompatibility and safety.
Automotive accounts for the remaining 8% of the market, with revenue of USD 39 million in 2025, used in coating electronic and connector components in automotive applications. The Gold Plating Chemicals market's Automotive segment is characterized by its focus on durability and reliability.
Gold Plating Chemicals Market Regional Outlook
Asia-Pacific Gold Plating Chemicals Market
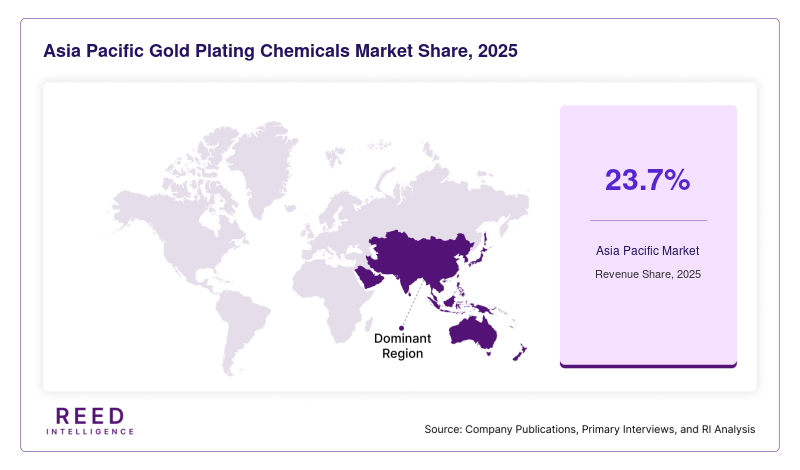
Leads the Gold Plating Chemicals market, commanding a 40% share, with a revenue of USD 194 million in 2025. China is the primary driver, accounting for 55% of regional demand, followed by Japan, South Korea, and Taiwan, driven by the massive electronics manufacturing base, growing jewelry industry, and expanding automotive sector. The Asia-Pacific Gold Plating Chemicals market is characterized by its focus on large-scale production and cost-competitive pricing.
North America Gold Plating Chemicals Market
Represents the second-largest market, capturing a 28% share with a revenue of USD 136 million in 2025. The United States is the primary driver, accounting for 85% of regional demand, driven by the well-established electronics, aerospace, and medical industries, and a focus on innovation and sustainability. The Gold Plating Chemicals market in North America is characterized by its focus on advanced formulations and environmental compliance.
Europe Gold Plating Chemicals Market
Accounts for 22% of the global Gold Plating Chemicals market, with a revenue of USD 107 million in 2025. Germany, the UK, and France are the primary drivers, together accounting for 55% of regional demand, driven by strong manufacturing sectors, stringent environmental regulations, and a focus on quality. The Europe Gold Plating Chemicals market is projected to grow at a steady CAGR of 5.5% through 2034.
Middle East & Africa and Latin America Gold Plating Chemicals Market
Together account for the remaining 10% of the Gold Plating Chemicals market, with the UAE and Brazil leading their respective regions. Both regions are projected to grow at CAGRs exceeding 6%, driven by increasing industrialization and growing jewelry sectors.
Top players in Gold Plating Chemicals Market
- Atotech (MKS Instruments)
- MacDermid Enthone Industrial Solutions
- Umicore Group
- Coventya
- Technic Inc.
- Gold Plating Services
- Metalor Technologies International SA
- Johnson Matthey Plc
- Tanaka Holdings Co., Ltd.
- Mitsubishi Materials Corporation
- Chemetall (BASF)
- JCU Corporation
- Nippon Hyomen Kagaku KK
- DOWA Holdings Co., Ltd.
- Kunshan Sanhui Chemical Co., Ltd.
Atotech (MKS Instruments)
Atotech holds a dominant position in the Gold Plating Chemicals market, with an estimated 14% global market share, particularly strong in the North American, European, and Asia-Pacific electronics and automotive segments. The company's portfolio of gold plating chemicals, including both cyanide and non-cyanide solutions, is widely recognized for its quality, innovation, and reliability. Atotech's market leadership is reinforced by its significant investment in R&D, its extensive global distribution network, and its strong relationships with leading electronics and automotive manufacturers. Atotech commands over 16% of the North American market and 12% of the European market for gold plating chemicals, positioning it as a key player in the global market.
MacDermid Enthone Industrial Solutions
MacDermid Enthone is a leading player in the Gold Plating Chemicals market, commanding approximately 12% of the global market share through its comprehensive portfolio of plating solutions and surface finishing technologies. The company's expertise in the development and application of advanced electroplating chemistries have solidified its position, particularly in the electronics and decorative plating sectors. MacDermid Enthone's gold plating chemicals are known for their high performance, reliability, and innovative formulations. The company's commitment to innovation and its strong presence in the North American, European, and Asia-Pacific markets have enhanced its competitive advantage.
Umicore Group holds a significant 10% market share, with particular strength in the precious metal chemistry and recycling segments. Coventya is a major player in the global specialty chemicals and plating market, holding a 8% share, known for its focus on sustainable and high-performance solutions.
Recent Developments in Gold Plating Chemicals Market
- 2025: Atotech launched a new line of non-cyanide gold plating chemicals with enhanced stability and performance, targeting the growing demand for sustainable and safer electroplating solutions.
- 2025: MacDermid Enthone introduced a new high-speed gold plating chemistry for semiconductor packaging, designed to improve productivity and reduce costs in advanced electronics manufacturing.
Gold Plating Chemicals Market Segments
By Type
- Gold Cyanide Baths
- Non-Cyanide Gold Baths
By Application
- Electronics
- Jewelry
- Aerospace
- Medical
- Automotive
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM