Mineral Wool Board Insulation Market Size, Share & Trends Analysis Report By Product Type (Thermal Insulation, Acoustic Insulation, Fire Protection) and By Application (Residential Buildings, Commercial Buildings) and By End User (Construction, Industrial) and By Distribution Channel (Direct Sales, Distributors, Online Retail) and By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa) Forecasts, 2026–2034
USD 3950
Mineral Wool Board Insulation Market Size
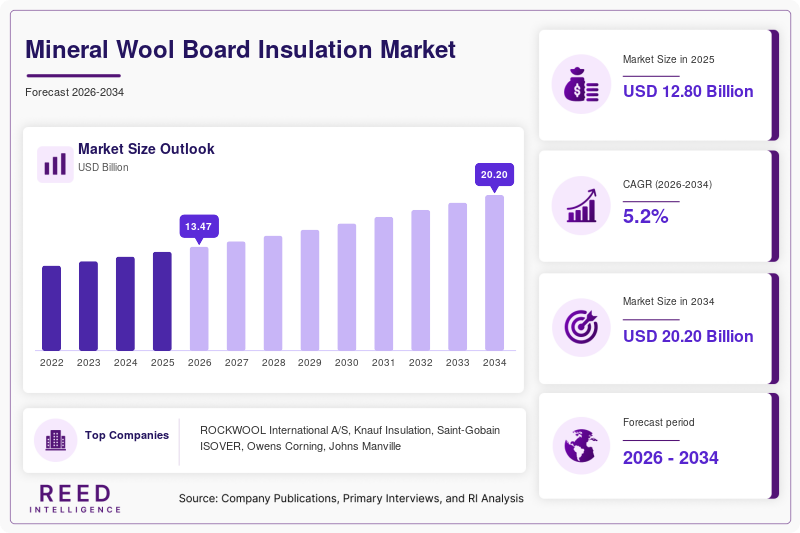
The global mineral wool board insulation market was valued at USD 12.80 Billion in 2025 and is projected to grow from USD 13.47 Billion in 2026 to USD 20.20 Billion by 2034, registering a CAGR of 5.2% during the forecast period from 2026 to 2034.
Mineral wool board insulation is a rigid or semi-rigid insulation material manufactured from mineral fibers, primarily stone, rock, slag, or other mineral feedstocks. The boards are engineered into different densities and thicknesses to provide thermal insulation, acoustic absorption, fire resistance, and mechanical performance. Stone wool and glass mineral wool are particularly important materials within the broader mineral-wool insulation industry.
The product is widely used in residential, commercial, and industrial construction. Exterior walls, roofs, interior partitions, ceilings, HVAC systems, mechanical rooms, industrial equipment, tanks, furnaces, and process facilities are major application areas. Mineral wool is particularly attractive where thermal performance must be combined with non-combustibility and acoustic protection. Owens Corning's Thermafiber portfolio, for example, serves commercial, industrial, and residential applications and emphasizes fire resistance, thermal performance, sound control, water resistance, and recycled content.
Mineral Wool Board Insulation Market Drivers
Increasing Energy-Efficiency Requirements
Government regulations and building-performance standards are encouraging developers to improve the thermal efficiency of buildings. Mineral wool boards help reduce heat transfer through walls, roofs, and other building-envelope components, making them increasingly relevant to energy-efficient construction and renovation programs.
Growing Demand for Fire-Resistant Construction Materials
Mineral wool is inherently non-combustible and can withstand very high temperatures. This characteristic is particularly valuable in commercial buildings, high-rise structures, industrial facilities, data centers, infrastructure projects, and buildings where fire safety is a critical design requirement. Owens Corning states that its Thermafiber mineral wool resists fire and temperatures exceeding 2,000°F.
Expansion of Green Building and Sustainable Construction
Green-building certifications and decarbonization targets are encouraging the use of insulation materials that improve building energy efficiency while supporting lower lifecycle environmental impacts. Mineral wool products containing recycled materials and manufactured through lower-carbon processes are increasingly aligned with these requirements.
Increasing Construction and Renovation Activity
Urbanization, infrastructure development, commercial construction, industrial expansion, and renovation of aging buildings are generating demand for insulation boards. Building renovation is particularly important in Europe and North America, where improving the energy performance of existing buildings is an important policy objective.
Mineral Wool Board Insulation Market Restraints
Energy-Intensive Manufacturing
Mineral wool manufacturing requires high-temperature melting and fiberization processes. Energy prices therefore have a direct influence on production economics. ROCKWOOL reported that rising energy and transportation costs affected its 2026 operations, highlighting the sensitivity of the industry to manufacturing-energy costs.
Higher Cost Compared With Some Alternative Insulation Materials
Mineral wool boards can have higher material and installation costs than certain polymer-based insulation products. In price-sensitive construction projects, expanded polystyrene, extruded polystyrene, polyurethane, and other alternatives can compete strongly.
Installation and Handling Requirements
Rigid mineral wool boards require appropriate cutting, fastening, joint treatment, and installation procedures to achieve their designed thermal and fire-performance characteristics. Incorrect installation can create gaps or thermal bridges and reduce overall system performance.
Mineral Wool Board Insulation Market Opportunities
Low-Carbon Mineral Wool Manufacturing
Electric melting technology is emerging as an important opportunity for reducing the carbon intensity of mineral-wool production. Knauf's new Croatian electric melting line can use up to 50% recycled raw material, while ROCKWOOL's new Washington facility incorporates electric melting technology.
Building Renovation and Retrofit
The renovation of older residential and commercial buildings creates substantial opportunities for mineral wool board suppliers. Energy-efficiency upgrades, facade renovation, roof insulation, fire-safety improvements, and acoustic modernization can increase demand for high-performance insulation boards.
Data Centers and High-Performance Buildings
Rapid expansion of data centers, healthcare facilities, logistics centers, industrial buildings, and high-performance commercial properties is creating demand for insulation that combines thermal control, fire protection, and acoustic performance. Mineral wool's non-combustibility gives it an advantage in several safety-critical building applications.
Mineral Wool Board Insulation Market Segmental Analysis
By Product Type
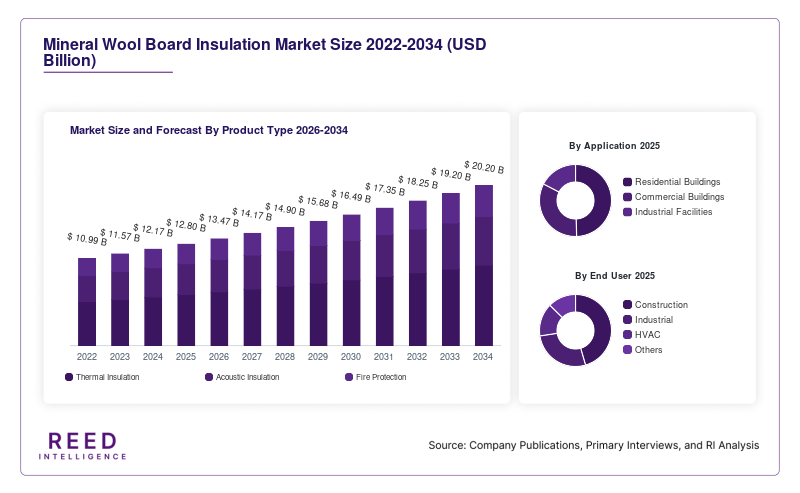
Thermal Insulation dominated the Mineral Wool Board Insulation Market in 2025, accounting for approximately 48.5% of global revenue, equivalent to about USD 6.20 Billion. The segment benefits from the fundamental requirement to reduce heat transfer in residential, commercial, and industrial buildings. Thermal mineral wool boards are extensively used in exterior walls, roofs, attics, basements, HVAC systems, and industrial equipment.
Acoustic Insulation is the fastest-growing product-type segment, with an estimated 6.2% CAGR during 2026–2034. Increasing demand for noise control in offices, commercial buildings, residential developments, transportation infrastructure, and industrial facilities is supporting its expansion. The segment also benefits from the ability of mineral wool to combine sound absorption with thermal and fire performance.
By Application
Residential Buildings represent the dominant application segment, supported by increasing requirements for thermal comfort, energy efficiency, fire safety, and building-envelope performance. Residential demand is particularly important in Asia Pacific, where urbanization and housing development continue to support insulation consumption. The broader thermal-insulation segment obtains approximately 52% of its consumption from residential construction.
Industrial Facilities represent an important high-value growth opportunity because mineral wool boards are used around industrial equipment, HVAC systems, process areas, furnaces, boilers, tanks, and other temperature-intensive environments. Industrial applications benefit from the material's combination of thermal stability, fire resistance, acoustic performance, and durability.
By End User
Construction is the dominant end-user segment because mineral wool boards are extensively incorporated into walls, roofs, floors, facades, ceilings, partitions, and building-envelope systems. Construction demand is supported by new residential and commercial development as well as energy-efficiency renovation programs.
HVAC represents a significant specialized opportunity as buildings and industrial facilities increasingly require efficient thermal management around ducts, mechanical rooms, equipment, and ventilation systems. Mineral wool products are particularly suitable where insulation must also provide fire and acoustic protection.
By Distribution Channel
Direct Sales represent the leading distribution channel because large construction projects and industrial facilities typically require technical specification, customized product selection, project-level supply, and manufacturer or authorized-distributor support.
Online Retail is the fastest-developing distribution opportunity, particularly for smaller contractors, renovation projects, and do-it-yourself applications. Digital procurement enables customers to compare technical specifications, product availability, installation requirements, and pricing before purchasing.
Mineral Wool Board Insulation Market Regional Analysis
North America Mineral Wool Board Insulation Market
North America represents a major market for mineral wool board insulation, supported by commercial construction, residential renovation, industrial facilities, data centers, and increasingly stringent requirements for energy efficiency and fire safety. The region also has a well-established manufacturing base, with ROCKWOOL, Owens Corning, Johns Manville, and other suppliers serving commercial and industrial customers.
Manufacturing investment is strengthening regional supply. In April 2026, ROCKWOOL broke ground on a $175 million stone-wool manufacturing facility in Washington State, its fifth North American plant and first in the western United States. The facility is expected to begin commercial production in 2028 and will incorporate electric melting technology.
Europe Mineral Wool Board Insulation Market
Europe remains an important mineral wool board insulation market because of stringent building-energy requirements, renovation policies, fire-safety regulations, and the region's emphasis on sustainable construction. Renovation of older building stock is particularly important as governments seek to improve building energy performance and reduce emissions.
Manufacturers are simultaneously investing in lower-carbon production. In July 2026, Knauf began operation of a new electric melting line for rock mineral wool at its Novi Marof facility in Croatia following an investment of more than €120 million. The technology can use up to 50% recycled raw material and reduces emissions from the melting process.
Asia Pacific Mineral Wool Board Insulation Market
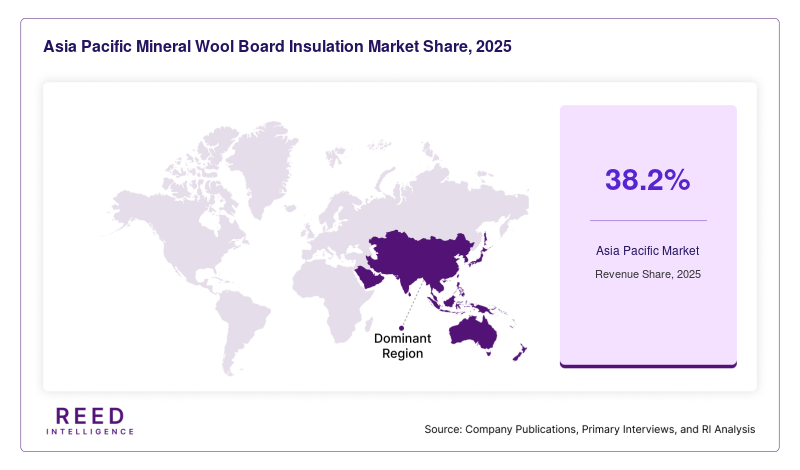
Asia Pacific was the dominant region in 2025, accounting for 38.2% of global revenue. Based on the supplied 2025 global market size of USD 12.80 Billion, the corresponding regional market value is approximately USD 4.89 Billion, which is consistent with the reported regional valuation. Rapid urbanization, construction activity, industrial expansion, energy-efficiency requirements, and infrastructure development in China, India, and Southeast Asia support the region's leading position.
The region also provides substantial long-term potential because governments and developers are increasingly incorporating energy-efficient materials into new buildings and renovation projects. China, India, Japan, South Korea, and Southeast Asian economies are expected to remain important demand centers. An exact comparable regional CAGR for Asia Pacific within the supplied Mineral Wool Board Insulation Market dataset is not independently verified and is therefore not stated.
Latin America Mineral Wool Board Insulation Market
Latin America represents an emerging market supported by residential construction, commercial development, industrial facilities, infrastructure projects, and growing awareness of energy-efficient building materials. Demand for mineral wool boards is particularly relevant to projects where thermal performance must be combined with fire safety and acoustic control.
The region's growth potential is also linked to modernization of industrial buildings and increasing adoption of international construction standards. However, an exact 2025 market share and market value compatible with the supplied global dataset are not independently verified and are therefore not presented as confirmed figures.
Middle East & Africa Mineral Wool Board Insulation Market
The Middle East & Africa market is supported by commercial construction, industrial infrastructure, oil and gas facilities, hospitality projects, healthcare buildings, transportation infrastructure, and large-scale urban development. High ambient temperatures increase the importance of thermal insulation for building energy management, while fire resistance remains important in high-rise and industrial construction.
Mineral wool boards can address multiple requirements simultaneously through thermal insulation, acoustic control, and non-combustibility. However, an exact comparable 2025 market share and market value for the region could not be verified against the same dataset used for the supplied global market value.
Mineral Wool Board Insulation Market Competitive Landscape
The Mineral Wool Board Insulation Market is characterized by global insulation manufacturers competing through product performance, fire resistance, thermal efficiency, acoustic performance, sustainability credentials, recycled content, manufacturing capacity, geographic reach, and technical support. Major participants are increasingly investing in low-carbon production technologies and expanding manufacturing capacity to meet demand for energy-efficient construction materials.
ROCKWOOL is a leading global stone-wool manufacturer with operations across numerous countries and a broad portfolio covering building insulation, acoustic ceilings, external cladding systems, industrial insulation, and technical applications. In 2026, the company reported strong volume-driven revenue growth and continued investment in capacity expansion, electrification, automation, and digital initiatives.
Key Market Players
- ROCKWOOL International A/S
- Knauf Insulation
- Saint-Gobain ISOVER
- Owens Corning
- Johns Manville
- URSA Insulation
- Kingspan Group
- Beijing New Building Materials (Group) Co., Ltd.
- KCC Corporation
- TechnoNICOL
- Ravago Building Solutions
Mineral Wool Board Insulation Market Recent Developments
- September , 2026 Knauf invests €30 million in mineral wool recycling in Austria
Knauf Insulation received a building permit for a new recycling plant in Ferndorf, Austria. The facility is designed to recycle both glass wool and rock mineral wool, returning recovered material to the production cycle. This initiative could support circular construction practices and reduce mineral wool waste. - April 29, 2026 – ROCKWOOL begins construction of a $175 million US facility
ROCKWOOL broke ground on a new stone wool manufacturing facility in Wallula, Washington. The planned facility represents a $175 million investment and is expected to support 125 direct jobs. It will use electric melting technology, with commercial production expected to begin in 2028, strengthening supply capacity in the western United States.
Mineral Wool Board Insulation Market Segments
By Product Type
- Thermal Insulation
- Acoustic Insulation
- Fire Protection
By Application
- Residential Buildings
- Commercial Buildings
- Industrial Facilities
By End User
- Construction
- Industrial
- HVAC
- Others
By Distribution Channel
- Direct Sales
- Distributors
- Online Retail
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM