Mini Type Garbage Truck Market Size, Share & Trends Analysis Report By Vehicle Type (Rear Loader, Front Loader, Side Loader, Mini Compactor Garbage Truck, Electric Mini Garbage Truck), By Application (Municipal Waste Collection, Commercial Waste Collection, Residential Waste Collection, Industrial Waste Collection) and By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa) Forecasts, 2026–2034
USD 3950
Mini Type Garbage Truck Market Size
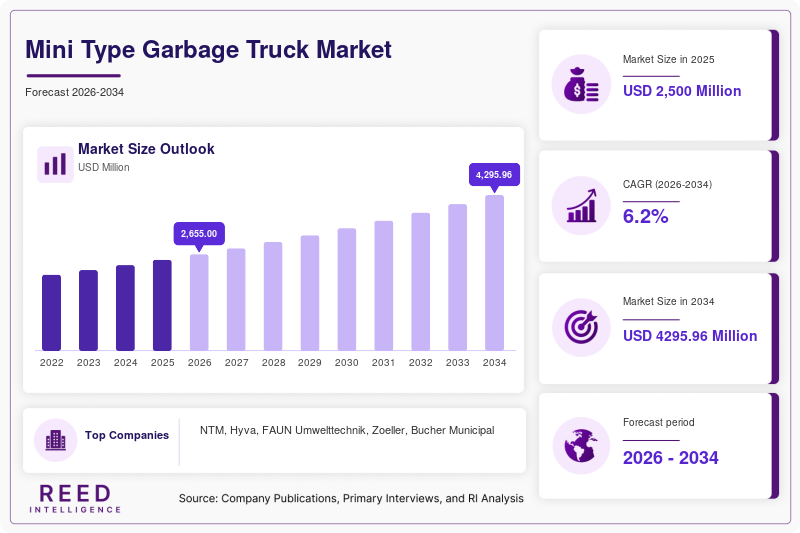
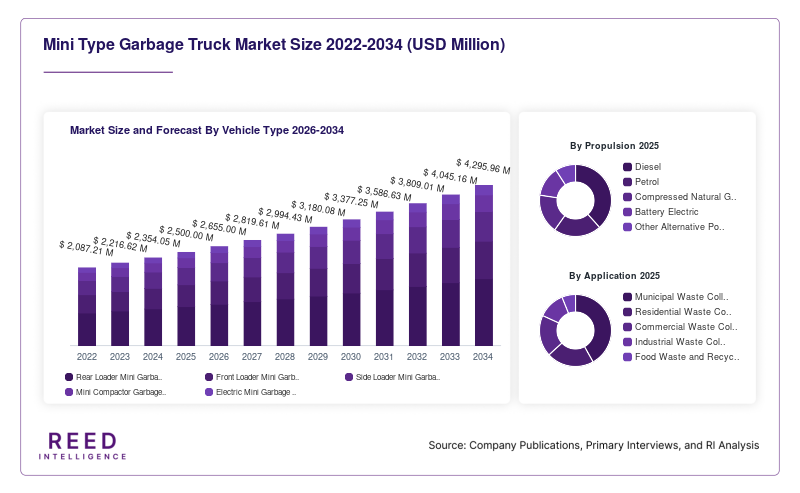
The global mini type garbage truck market was valued at USD 2,500 million in 2025 and is projected to grow from USD 2,655 million in 2026 to USD 4,295.96 million by 2034, registering a CAGR of 6.2% during the forecast period (2026–2034).
The Mini Type Garbage Truck Market includes compact waste collection vehicles designed to collect and transport municipal, residential, commercial, and selected industrial waste in areas where conventional large refuse trucks face access or manoeuvrability limitations. These vehicles are particularly useful on narrow streets, in densely populated neighbourhoods, historic city centres, gated communities, and locations with restricted turning space.
Demand is supported by urbanisation, municipal waste collection programmes, expanding door-to-door collection services, and the need to improve collection efficiency in densely populated areas. Compact vehicles can also support specialised waste streams, including food waste and recyclable materials, when fitted with suitable collection bodies and lifting equipment.
Mini Type Garbage Truck Market Drivers
Urbanisation and restricted road access: Increasing urban density creates demand for compact collection vehicles that can navigate narrow streets and congested neighbourhoods more easily than conventional heavy refuse trucks.
Expansion of municipal waste collection: Growing household waste volumes and wider door-to-door collection coverage encourage municipalities and waste management contractors to invest in specialised collection vehicles.
Food waste and recycling programmes: Separate collection of organic waste and recyclable materials creates opportunities for compact trucks configured for specific collection routes and smaller loads.
Fleet modernisation: Municipalities and private waste operators are replacing ageing vehicles with models designed to improve collection productivity, reliability, operator safety, and maintenance efficiency.
Mini Type Garbage Truck Market Restraints
Limited payload and storage capacity: Smaller vehicles generally carry less waste per trip than larger refuse trucks, potentially requiring additional journeys and increasing operating costs on high-volume routes.
High acquisition and customisation costs: Specialised bodies, compactors, lifting systems, safety equipment, and electric powertrains can increase upfront investment.
Maintenance and spare-parts availability: Hydraulic systems, compactors, vehicle electronics, and specialised components require dependable servicing and replacement parts to maintain fleet availability.
Electric vehicle infrastructure limitations: Electric mini garbage trucks can face operational constraints where depot charging, charging time, battery range, or local service support is insufficient.
Mini Type Garbage Truck Market Opportunities
Electric compact refuse vehicles: Battery-electric models create opportunities for low-noise, zero-tailpipe-emission collection in residential areas and low-emission urban zones.
Smart fleet management: GPS tracking, route optimisation, vehicle diagnostics, and collection monitoring can help operators improve route planning and vehicle utilisation.
Specialised waste collection: Demand for food waste, recyclables, and segregated household waste can support purpose-built compact vehicles with suitable body designs and lifting systems.
Emerging-market urban sanitation: Investments in municipal sanitation, door-to-door collection, and waste management infrastructure can create opportunities for compact vehicle manufacturers and local body builders.
Mini Type Garbage Truck Market Segmental Analysis
By Vehicle Type
Rear loader mini garbage trucks are an important vehicle category because their rear-loading configuration can support collection from residential streets and locations where workers load waste containers or bags at the rear of the vehicle. Compact rear loaders can be configured for municipal and commercial collection routes, subject to payload, body volume, and access requirements.
Mini compactor garbage trucks are also relevant where operators need to compress collected waste and increase the usable capacity of a compact vehicle. Their suitability depends on the waste stream, compaction requirements, and the operating environment. The dominant vehicle type and its exact market share are not reliably verifiable from a consistent public dataset for this specific market.
Electric mini garbage trucks represent a developing opportunity as municipalities explore lower-emission vehicles for stop-and-go routes and neighbourhood collection. Their suitability depends on daily distance, waste payload, energy consumption, charging access, and vehicle availability. The fastest-growing vehicle type and its CAGR cannot be confirmed reliably for the narrowly defined mini type garbage truck market.
By Propulsion
Diesel-powered vehicles remain relevant for operators that prioritise established refuelling infrastructure, range, and familiarity with conventional commercial vehicle maintenance. CNG vehicles may be considered where fuel infrastructure is available and local fleet policies support their use.
Battery-electric mini garbage trucks are particularly relevant to urban routes that involve frequent stops, lower operating speeds, and return-to-depot schedules. They can reduce tailpipe emissions and vehicle noise during collection, although the overall business case depends on vehicle purchase cost, charging arrangements, battery performance, and local electricity costs. A defensible numerical ranking of propulsion types by market share is not available from a consistent public source for this specific market.
By Application
Municipal waste collection is a core application because local authorities and their contractors are responsible for household waste collection, street-level sanitation, and neighbourhood service coverage. Compact trucks are useful where road width, traffic, or access restrictions make larger vehicles less practical.
Residential and commercial collection also create demand for smaller vehicles serving apartment complexes, business districts, hospitality facilities, and other locations with limited access. Food waste and recycling collection can support purpose-built vehicles with sealed bodies or specialised loading systems. The leading application by percentage share and the fastest-growing application by CAGR cannot be verified consistently for this market definition.
Mini Type Garbage Truck Market Regional Analysis
North America Mini Type Garbage Truck Market
Demand in North America is supported by municipal waste services, established private waste management operators, fleet replacement programmes, and interest in alternative-fuel and electric refuse vehicles. Compact collection vehicles can serve residential neighbourhoods, commercial properties, and locations where vehicle dimensions or route conditions affect collection efficiency.
Fleet decisions depend on vehicle durability, total cost of ownership, service support, local emissions policies, and the availability of suitable chassis and collection bodies. A reliable numeric market-share percentage for North America within the specifically defined Mini Type Garbage Truck Market is not publicly verified. Its share should not be inferred from the broader refuse truck or commercial vehicle markets.
Europe Mini Type Garbage Truck Market
European demand is influenced by urban density, narrow historic streets, municipal waste separation programmes, and environmental policies. Compact refuse collection vehicles can support residential collection and specialised organic waste routes. Electric and other lower-emission configurations may be attractive in urban areas where local air quality and noise reduction are priorities.
Asia Pacific Mini Type Garbage Truck Market
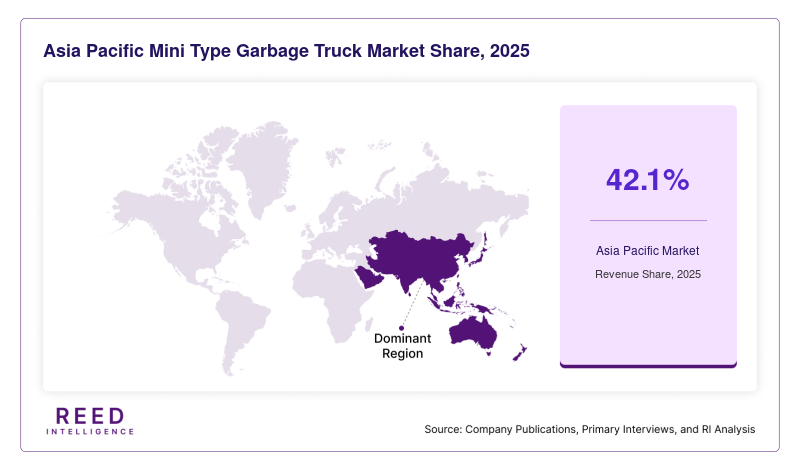
Asia Pacific dominated the global Mini Type Garbage Truck Market in 2025, accounting for approximately 42.1% of global market revenue. This position is associated with rapid urbanisation, expanding municipal waste collection services, and investments in sanitation infrastructure across countries including China, India, Vietnam, and Indonesia.Market conditions vary considerably between countries because of differences in municipal budgets, local manufacturing capacity, vehicle regulations, road infrastructure, and waste collection practices. Electric waste collection vehicles may gain relevance where local authorities support electrification and suitable charging systems are available. The exact Asia Pacific market-share percentage for the Mini Type Garbage Truck Market is not reliably verified in comparable public data, and a regional share should not be borrowed from the overall refuse truck market.
Latin America Mini Type Garbage Truck Market
Latin American demand is linked to urban growth, municipal sanitation needs, private waste collection services, and efforts to expand reliable household waste collection. Compact vehicles may be suitable for neighbourhood routes, smaller municipalities, and locations with limited road access or constrained collection infrastructure.
Adoption depends on vehicle affordability, financing, spare-parts availability, maintenance networks, road conditions, and municipal procurement priorities. Electric models may present opportunities in selected urban fleets, but charging access and acquisition cost remain important considerations.
Middle East & Africa Mini Type Garbage Truck Market
The Middle East & Africa market is influenced by urban development, municipal infrastructure investment, tourism and commercial property growth, and demand for improved sanitation services. Compact refuse trucks can serve residential communities, commercial districts, and locations where smaller vehicles are more practical than heavy collection trucks.
Market growth will depend on municipal procurement budgets, waste management partnerships, local road and service conditions, vehicle import costs, and the availability of technical support. Electric adoption will also depend on route requirements and charging infrastructure.
Mini Type Garbage Truck Market Competitive Landscape
The Mini Type Garbage Truck Market includes commercial vehicle manufacturers, refuse body manufacturers, and specialised waste collection vehicle suppliers. Competition is shaped by vehicle size, payload, compaction and lifting systems, chassis compatibility, fuel or electric powertrain options, service coverage, reliability, and customisation capability.
Specialist manufacturers may compete by designing compact collection bodies for narrow streets and specific waste streams, while larger commercial vehicle companies provide chassis platforms that can be adapted for refuse collection. Procurement decisions commonly consider the total cost of ownership, fleet uptime, spare-parts availability, safety features, and compliance with local vehicle and emissions requirements.
Key Market Players
- NTM
- Hyva
- FAUN Umwelttechnik
- Zoeller
- Bucher Municipal
- Heil Environmental
- Dennis Eagle
- Ros Roca
- Geesinknorba
- Labrie Environmental Group
- McNeilus Truck and Manufacturing
- BYD
Recent Market Developments
- May 2026, NTM presented its Mini-MAS compact refuse collection vehicle at IFAT Munich 2026. The vehicle is designed for food waste collection in dense urban environments, with compact dimensions and manoeuvrability for narrow streets and restricted-access locations. This development is directly relevant to the mini garbage truck segment because it demonstrates a purpose-built compact vehicle for specialised municipal collection routes.
- March 2026, NTM-GB announced that it would showcase the Mini-MAS at IFAT Munich from 4–7 May 2026, following the vehicle’s UK launch. The company highlighted the model’s compact design and suitability for food waste collection in urban locations. The planned European presentation illustrates manufacturers’ efforts to expand the reach of compact refuse collection vehicles across markets.
Mini Type Garbage Truck Market Segments
By Vehicle Type
- Rear Loader Mini Garbage Trucks
- Front Loader Mini Garbage Trucks
- Side Loader Mini Garbage Trucks
- Mini Compactor Garbage Trucks
- Electric Mini Garbage Trucks
By Propulsion
- Diesel
- Petrol
- Compressed Natural Gas (CNG)
- Battery Electric
- Other Alternative Powertrains
By Application
- Municipal Waste Collection
- Residential Waste Collection
- Commercial Waste Collection
- Industrial Waste Collection
- Food Waste and Recycling Collection
By End User
- Municipal Authorities
- Private Waste Management Companies
- Commercial and Industrial Operators
- Residential Communities and Property Managers
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM