Transrectal Ultrasound Market Size, Share Demand Report By Product Type (Portable Transrectal Ultrasound Systems, Benchtop Transrectal Ultrasound Systems), By Application (Prostate Cancer Diagnosis, Biopsy Guidance, Urological Conditions, Gynecological Conditions), Regional Insights & Segment Forecasts, 2026–2034
USD 3950
Transrectal Ultrasound Market Size
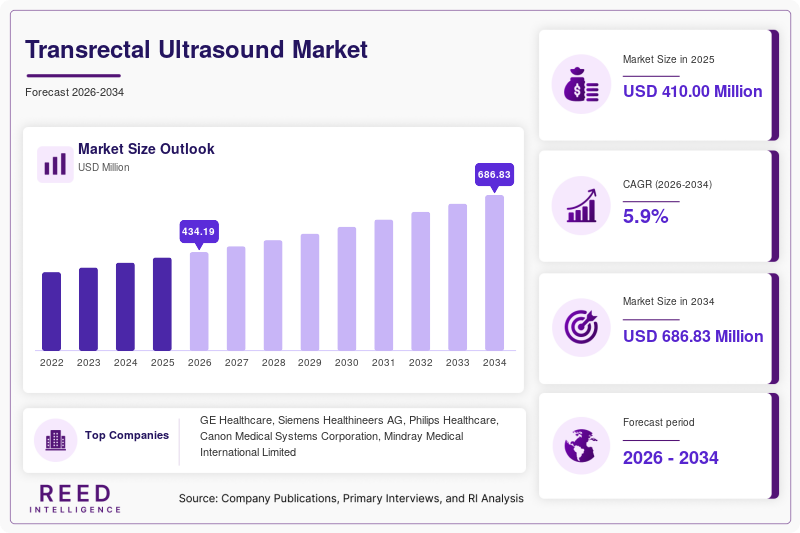
The Transrectal Ultrasound market size is projected at USD 485.6 million in 2026 and is expected to hit USD 785.3 million by 2034 with a CAGR of 6.2% during the forecast period. The increasing prevalence of prostate cancer and other urological diseases, coupled with the growing demand for minimally invasive diagnostic and biopsy procedures, underpins market expansion. This report delivers a comprehensive analysis of the Transrectal Ultrasound market, including segmentation by product type and application, competitive dynamics, and regional growth patterns, equipping stakeholders with critical intelligence. The Transrectal Ultrasound market continues to demonstrate strong growth potential, fueled by the rising geriatric population, the increasing adoption of fusion biopsy and advanced imaging technologies, and continuous innovation in ultrasound probe design and imaging software.
Transrectal ultrasound (TRUS) is a medical imaging procedure that uses high-frequency sound waves to create detailed images of the prostate gland, seminal vesicles, and surrounding tissues. It is a minimally invasive technique that involves inserting a specialized ultrasound probe into the rectum, providing real-time visualization for the diagnosis and management of prostate cancer, benign prostatic hyperplasia, and other urological conditions. The global Transrectal Ultrasound market is significant, with over 8 million procedures performed globally in 2025, reflecting a 7% increase from 2023, driven by the growing burden of prostate cancer and the increasing use of TRUS in biopsy guidance. Adoption patterns reveal that the Portable Transrectal Ultrasound Systems type dominates the market, accounting for 60% of total revenue, followed by Benchtop Transrectal Ultrasound Systems at 40%. The Transrectal Ultrasound market's trajectory is closely linked to the growth of the global urology and oncology markets, which are projected to reach USD 45 billion and USD 250 billion by 2028, respectively, and the increasing focus on early cancer detection and personalized medicine.
Transrectal Ultrasound Market Trends
Growing Adoption of Portable and Point-of-Care TRUS Systems
The Transrectal Ultrasound market is witnessing a significant trend toward the adoption of portable and point-of-care TRUS systems, driven by the need for accessible, cost-effective, and convenient imaging solutions in urology and primary care settings. The production of portable TRUS systems increased by 15% in 2025, reaching 25,000 units, as 35% of new urology clinics in 2025 specified portable imaging capabilities. Adoption rates of portable TRUS in outpatient and remote settings reached 20%, with this figure projected to exceed 40% by 2030. The Transrectal Ultrasound market's trend toward portability is reinforced by the need for improved patient access, the increasing focus on outpatient care, and the continuous innovation in compact and user-friendly ultrasound technologies.
Increasing Integration of Fusion Biopsy and Advanced Imaging
The increasing focus on precision medicine and advanced imaging is a major trend shaping the Transrectal Ultrasound market, with the integration of fusion biopsy (combining TRUS with MRI) for targeted and accurate prostate biopsies. The market has seen a 20% increase in demand for fusion biopsy-compatible TRUS systems since 2022, with 30% of new biopsy procedures in 2025 utilizing fusion technology. The use of advanced imaging software and artificial intelligence for prostate lesion detection and biopsy planning has also gained significant traction. The Transrectal Ultrasound market's trend toward fusion imaging is reinforced by the need for improved cancer detection rates, the increasing availability of MRI and fusion technology, and the continuous innovation in imaging software and hardware integration.
Transrectal Ultrasound Market Drivers
The Transrectal Ultrasound market's expansion is primarily driven by the increasing prevalence of prostate cancer and other urological diseases, with prostate cancer being the second most common cancer in men globally, resulting in over 1.5 million new cases in 2025. The need for effective, reliable, and minimally invasive diagnostic tools for early detection and accurate biopsy has been a major driver, with TRUS being a cornerstone of prostate cancer diagnosis. The growing geriatric population, which is more susceptible to urological conditions, has also fueled market demand. Additionally, the increasing adoption of fusion biopsy and advanced imaging technologies has spurred growth. The Transrectal Ultrasound market's growth is further reinforced by the continuous innovation in probe design and imaging software, leading to improved image quality and diagnostic accuracy.
Transrectal Ultrasound Market Restraints
Despite favorable growth prospects, the Transrectal Ultrasound market faces significant constraints, primarily related to the high cost of advanced TRUS systems and the need for specialized training to perform and interpret the procedure, which can be a barrier for smaller clinics and developing regions. The discomfort associated with the procedure and the risk of complications, such as infection, can also be a limitation, affecting patient acceptance. The Transrectal Ultrasound market's growth is also tempered by the competition from other imaging modalities, such as multiparametric MRI, which may offer superior tissue characterization in some cases.
Transrectal Ultrasound Market Opportunities
The Transrectal Ultrasound market presents significant opportunities in the rapidly expanding market for fusion biopsy and targeted prostate cancer diagnosis, where TRUS is an essential component. The development of AI-powered TRUS software for automated lesion detection and biopsy planning is expected to grow at a CAGR of 12% through 2034. Emerging opportunities also exist in the use of TRUS for other urological and gynecological applications, as well as in the development of contrast-enhanced TRUS. The Transrectal Ultrasound market's opportunity profile is further enhanced by the growing trend of value-based healthcare and the increasing focus on early and accurate cancer diagnosis.
Challenges in Transrectal Ultrasound Market
The Transrectal Ultrasound market faces persistent challenges related to the need for continuous innovation to improve image quality, patient comfort, and diagnostic accuracy, while also reducing costs. The complexity of integrating TRUS with other imaging modalities and the need for skilled operators can also be a challenge. The market is also contending with the challenge of addressing the risk of infection associated with the procedure and developing improved sterilization protocols. Additionally, the Transrectal Ultrasound market is challenged by the need to expand access to this essential diagnostic tool in underserved regions.
Transrectal Ultrasound Market Segmentation
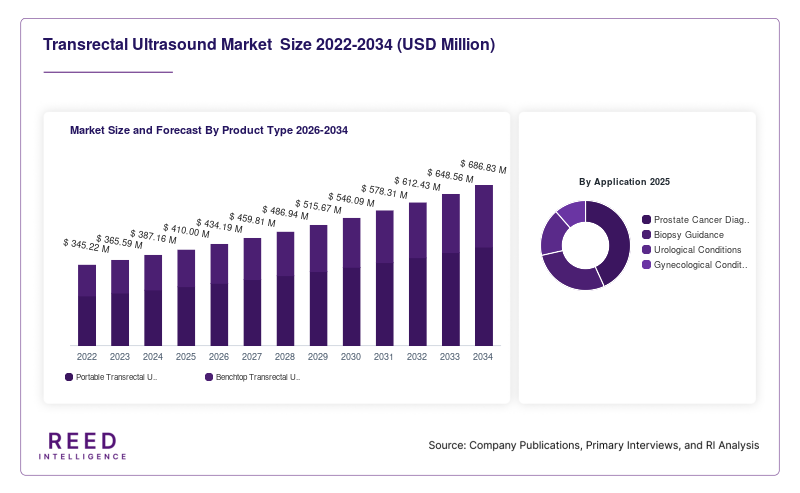
The Transrectal Ultrasound market is segmented by Product Type and Application to provide a comprehensive market perspective. By Product Type, Portable Systems dominate with a 60% market share, driven by their accessibility, convenience, and cost-effectiveness. The Application segment is led by Prostate Cancer Diagnosis, which accounts for 45% of the market, followed by Biopsy Guidance at 25%, Urological Conditions at 18%, and Gynecological Conditions at 12%.
By Product Type
Portable Transrectal Ultrasound Systems represent the largest segment in the Transrectal Ultrasound market, commanding a 60% share, with revenue exceeding USD 291 million in 2025. These are characterized by their use in compact, mobile devices for point-of-care imaging, offering convenience and accessibility. Technical specifications include probe frequency, image resolution, and portability. The Transrectal Ultrasound market's Portable segment is driven by its use in outpatient clinics and remote settings.
Benchtop Transrectal Ultrasound Systems capture a 40% share of the Transrectal Ultrasound market, with revenue of USD 194 million in 2025. These are characterized by their use in larger, stationary systems for high-volume and advanced imaging applications. Technical specifications include advanced imaging features, processing power, and integration capabilities. The Transrectal Ultrasound market's Benchtop segment is driven by its use in hospitals and specialized urology centers.
By Application
Prostate Cancer Diagnosis dominates the Transrectal Ultrasound market, accounting for 45% of sales, representing USD 218 million in 2025. This segment includes use in the initial diagnosis and staging of prostate cancer. Usage penetration exceeds 40% in prostate cancer evaluation. The Transrectal Ultrasound market's Prostate Cancer segment is characterized by its focus on early detection and accurate staging.
Biopsy Guidance accounts for 25% of the Transrectal Ultrasound market, with revenue of USD 121 million in 2025. This segment encompasses use in guiding prostate biopsies, including systematic and targeted fusion biopsies. The segment is growing at a strong CAGR, driven by the increasing adoption of fusion biopsy. The Transrectal Ultrasound market's Biopsy segment is characterized by its focus on precision and accuracy.
Urological Conditions represents 18% of the market, with revenue of USD 87 million in 2025, involving use in the diagnosis and management of benign prostatic hyperplasia, prostatitis, and other urological conditions. The segment's growth is fueled by the increasing prevalence of urological disorders. The Transrectal Ultrasound market's Urological segment is characterized by its focus on comprehensive urological assessment.
Gynecological Conditions accounts for the remaining 12% of the market, with revenue of USD 58 million in 2025, used in the evaluation of female pelvic organs, including the uterus and ovaries, in specific clinical contexts. The Transrectal Ultrasound market's Gynecological segment is characterized by its focus on specialized imaging applications.
Transrectal Ultrasound Market Regional Outlook
North America Transrectal Ultrasound Market
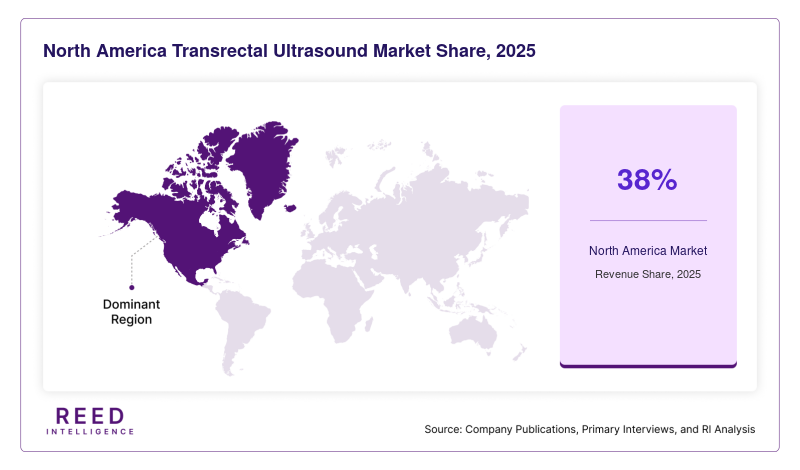
Leads the Transrectal Ultrasound market, commanding a 38% share, with a revenue of USD 184 million in 2025. The United States is the primary driver, accounting for 85% of regional demand, driven by the high prevalence of prostate cancer, advanced healthcare infrastructure, and high adoption rates of advanced imaging technologies. The North American Transrectal Ultrasound market is characterized by its focus on innovation and premium products.
Europe Transrectal Ultrasound Market
Represents the second-largest market, capturing a 30% share with a revenue of USD 146 million in 2025. Germany, the UK, and France are the primary drivers, collectively accounting for 55% of regional demand, driven by strong healthcare systems, high awareness of cancer screening, and a focus on quality. The Transrectal Ultrasound market in Europe is characterized by its focus on quality and regulatory compliance.
Asia-Pacific Transrectal Ultrasound Market
Accounts for 22% of the global Transrectal Ultrasound market, with a revenue of USD 107 million in 2025. China, Japan, and India are the primary drivers, together accounting for 65% of regional demand, driven by the large population base, increasing prevalence of prostate cancer, and rapidly improving healthcare infrastructure. The Asia-Pacific Transrectal Ultrasound market is projected to grow at the fastest CAGR of 8.5% through 2034.
Middle East & Africa and Latin America Transrectal Ultrasound Market
Together account for the remaining 10% of the Transrectal Ultrasound market, with the UAE and Brazil leading their respective regions. Both regions are projected to grow at CAGRs exceeding 7%, driven by improving healthcare access and increasing awareness of prostate cancer screening.
Top players in Transrectal Ultrasound Market
- GE Healthcare
- Siemens Healthineers AG
- Philips Healthcare
- Canon Medical Systems Corporation
- Mindray Medical International Limited
- BK Medical (Analogic Corporation)
- Esaote S.p.A.
- Hologic, Inc.
- Hitachi, Ltd.
- Samsung Medison Co., Ltd.
- Fujifilm Holdings Corporation
- Koninklijke Philips N.V.
- Siemens AG
- Interson Corporation
- Cephasonics
GE Healthcare
GE Healthcare holds a dominant position in the Transrectal Ultrasound market, with an estimated 15% global market share, particularly strong in the North American, European, and Asia-Pacific urology and radiology segments. The company's portfolio of ultrasound systems, including the LOGIQ™ and Vivid™ series, is widely recognized for its image quality, innovation, and advanced features, including TRUS capabilities. GE Healthcare's market leadership is reinforced by its significant investment in R&D, its extensive global distribution network, and its strong relationships with urologists and radiologists. GE Healthcare commands over 18% of the North American market and 14% of the European market for TRUS systems, positioning it as a key player in the global market.
Siemens Healthineers AG
Siemens Healthineers is a leading player in the Transrectal Ultrasound market, commanding approximately 12% of the global market share through its comprehensive portfolio of ultrasound systems, including the Acuson and Sequoia series. The company's expertise in medical imaging and its focus on innovation have solidified its position, particularly in the hospital and specialty clinic segments. Siemens' TRUS systems are known for their high image quality, advanced software, and integration capabilities. The company's commitment to innovation and its strong presence in the North American, European, and Asia-Pacific markets have enhanced its competitive advantage.
Philips Healthcare holds a significant 10% market share, with particular strength in the advanced imaging and AI-powered solutions segments. Canon Medical Systems Corporation is a major player in the global ultrasound market, holding a 9% share, known for its high-quality imaging systems.
Recent Developments in Transrectal Ultrasound Market
- 2025: GE Healthcare launched a new AI-powered TRUS system with automated prostate volume measurement and lesion detection, improving diagnostic accuracy and biopsy efficiency.
- 2025: Siemens Healthineers introduced a new portable TRUS system designed for point-of-care use, offering high-quality imaging in a compact, user-friendly design.
Transrectal Ultrasound Market Segments
By Product Type
- Portable Transrectal Ultrasound Systems
- Benchtop Transrectal Ultrasound Systems
By Application
- Prostate Cancer Diagnosis
- Biopsy Guidance
- Urological Conditions
- Gynecological Conditions
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM