3D Fashion Design Software Market Size, Share & Trends Analysis Report By Deployment (Cloud-Based, On-Premise), By Application (Apparel Design, Pattern Development, Virtual Sampling, Fashion Visualization, Others), By End User (Fashion Brands & Retailers, Apparel Manufacturers, Designers & Studios, Others) and By Region (North America, Europe, Asia-Pacific, Latin America, Middle East & Africa) Forecasts, 2026–2034
USD 3950
3D Fashion Design Software Market Size
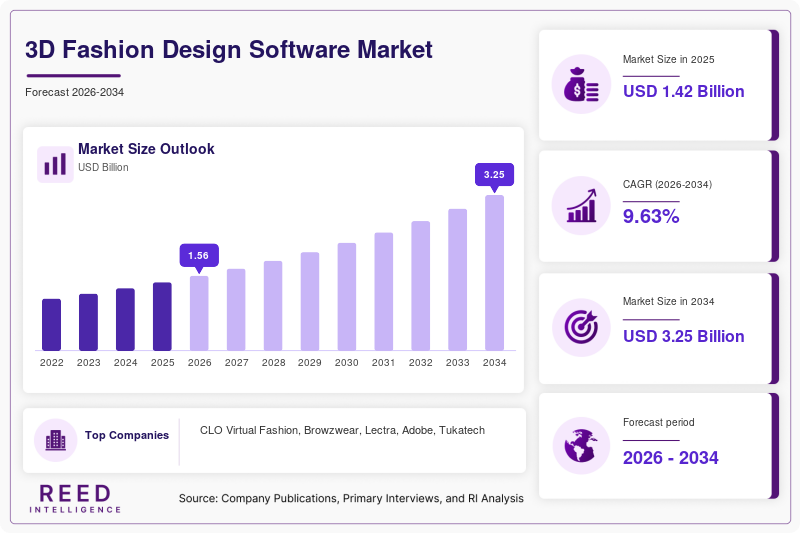
The global 3D fashion design software market was valued at USD 1.42 billion in 2025 and is projected to grow from USD 1.56 billion in 2026 to USD 2.97 billion by 2034, registering a CAGR of 9.63% during the forecast period from 2026 to 2034.
3D fashion design software is moving from a visualization tool toward a broader digital product-creation environment covering pattern development, virtual fitting, material simulation, digital sampling, collaboration and production preparation. Platforms such as CLO, Browzwear and Lectra's Modaris connect 2D pattern information with 3D garment visualization, allowing designers and technical teams to evaluate fit, materials and construction before producing physical samples. Lectra's Modaris, for example, supports the workflow from base-pattern creation through final pattern approval and 3D prototypes.
The principal commercial mechanism is the replacement or reduction of physical iterations with digital iterations. Adobe describes 3D fashion workflows as reducing reliance on physical samples while enabling realistic visualization of materials and garments. Browzwear similarly positions digital twins around design, fit validation, merchandising and production, with its platform integrating 3D garment creation and workflow collaboration.
3D Fashion Design Software Market Drivers
Digital Sampling Reduces the Number of Physical Development Iterations
Fashion companies traditionally require multiple physical samples to evaluate construction, fit, materials and appearance. 3D software creates a mechanism for shifting part of this iterative process into a digital environment, allowing teams to modify patterns, fabrics, colors and proportions before ordering another physical sample.
Browzwear states that its digital workflow can reduce physical samples and connect design, validation and production through a common digital garment. Adobe likewise identifies reduced reliance on physical samples and virtual sampling as important benefits of its fashion-focused 3D workflow.
The commercial effect is strongest for brands developing large numbers of styles and colorways, where every additional physical iteration creates material, labor, shipping and review costs. The counterbalance is that digital simulation cannot eliminate every physical validation requirement, particularly for complex fabrics, construction details and production-specific characteristics.
Digital Twins Connect Design, Merchandising and Production
The value proposition of 3D software is expanding beyond design departments. A digital garment can be shared with technical teams, suppliers, buyers and merchandising groups, allowing multiple stakeholders to review the same product representation.
Browzwear's platform is designed around this connected workflow, moving from digital garment creation to fit validation, collaboration, virtual selling and production. Adobe's fashion workflow similarly emphasizes digital twins, realistic materials and integration with other creative applications.
This creates demand for software that integrates with PLM, ERP, CAD and material-management systems. The competitive implication is that interoperability increasingly becomes part of the purchasing decision. Smaller standalone applications can face difficulty when brands seek one connected digital product-development environment.
AI Is Expanding 3D Software From Visualization Toward Automated Creation
AI is adding new functionality to established 3D fashion workflows. CLO's AI Studio provides AI Texture Generator, AI Graphic Generator, AI Render and AI Image Generator capabilities, while its newer AI functionality supports virtual try-on imagery.
The market mechanism is increased design throughput. Designers can generate visual concepts, graphics, materials and presentation imagery without manually producing every asset from scratch. AI therefore complements rather than completely replaces conventional 3D modeling and pattern development.
Adobe is also integrating generative AI into its 3D fashion workflow through Firefly while maintaining connections with CLO, Browzwear and other fashion-development tools. The constraint is that AI-generated outputs still require professional review for garment construction, technical accuracy, brand consistency and manufacturability.
3D Fashion Design Software Market Restraints
High Implementation and Training Requirements Can Slow Adoption
3D fashion software requires more than simply installing a design application. Users need knowledge of digital patterns, avatars, garment construction, fabric properties, rendering and technical workflows.
CLO's own documentation illustrates the range of activities involved in digital garment creation, including pattern preparation, avatar selection, stitching, arrangement and dressing of the avatar. Lectra similarly positions Modaris around specialized patternmaking and industrialization workflows.
For smaller manufacturers and design studios, training costs and workflow migration can therefore delay implementation. The constraint is particularly relevant where existing teams remain dependent on traditional 2D CAD and physical sampling.
Digital Accuracy Depends on Quality of Materials and Fit Data
The commercial value of 3D simulation depends on how closely the digital garment represents the physical product. Fabric behavior, stretch, weight, drape, construction and sizing need to be represented accurately.
Browzwear emphasizes accurate fabric data, fit simulation and digital twins as prerequisites for reliable digital product creation. Adobe also highlights the importance of realistic material properties for photorealistic garment visualization.
Poor material data can therefore reduce confidence in digital samples and force brands back toward physical validation. This makes digital material libraries, scanning capabilities and standardized data increasingly important to software vendors.
3D Fashion Design Software Market Opportunities
Integration With PLM and Enterprise Fashion Workflows Creates a Larger Software Opportunity
The integration of 3D design with PLM represents a specific opportunity because fashion companies increasingly need product information to move between design, merchandising, technical development and manufacturing.
A 2025 partnership between DeSL and Browzwear brought Browzwear's digital product-creation capabilities into DeSL's PLM environment, allowing users to visualize design variations and collaborate on 3D models directly within the product-development workflow.
This type of integration can increase software value because companies can use the same digital assets across multiple stages rather than operating separate design and product-information systems.
The opportunity is strongest among larger apparel organizations with complex supplier networks. Adoption may be slower among smaller companies that lack dedicated PLM infrastructure or technical resources.
AI-Enabled Virtual Merchandising Can Extend 3D Software Into Sales and Marketing
Once a garment exists as a digital asset, it can be used beyond product development. Browzwear supports virtual catalogs, presentations and digital merchandising from 3D garments. Adobe similarly positions 3D assets for realistic digital presentations and e-commerce-oriented experiences.
This creates an opportunity to connect product creation with virtual showrooms, e-commerce imagery, buyer presentations and virtual try-on.
CLO's newer AI image-generation and virtual try-on capabilities reinforce this convergence between design software and digital commerce. The adoption barrier is the need for accurate digital assets and sufficiently realistic visualization to meet brand and consumer expectations.
Deployment Analysis
By Deployment
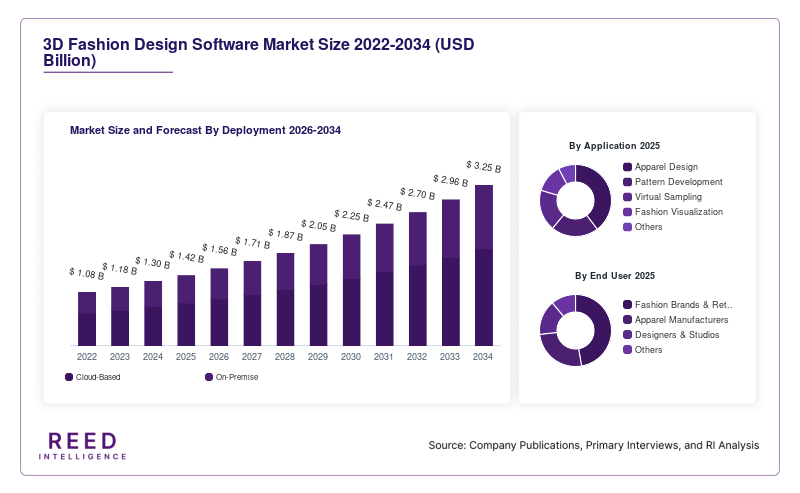
Cloud-Based deployment accounted for approximately 68% of the market in 2025, making it the dominant deployment segment. Cloud deployment fits fashion workflows that involve designers, suppliers, manufacturers and merchandising teams working across different locations.
Browzwear's platform emphasizes collaboration around shared digital garments, while its partner ecosystem includes technology, library, services and academic partners. This supports the use case for software that can connect multiple stakeholders around common digital assets.
On-Premise deployment accounted for approximately 32% of the market and is projected to grow at approximately 7.9% CAGR. It remains relevant where organizations prioritize direct control over software environments, data and existing enterprise infrastructure.
Cloud-based deployment is projected to grow at approximately 10.4% CAGR, supported by collaboration, subscription-based software models and integration with distributed product-development workflows.
Application Analysis
By Application
Apparel Design accounted for approximately 34% of the application segment in 2025. Designers use 3D platforms to evaluate silhouettes, colors, fabrics, proportions and garment construction before physical sampling.
Browzwear describes its design workflow as moving from concept and garment creation to a usable digital twin, while CLO enables pattern creation and digital garment development within the same environment.
The recurring nature of seasonal collection development creates repeated software usage across new styles and product variations. The segment's position is supported by the increasing integration of digital materials, rendering and AI-assisted creative tools.
Virtual Sampling accounted for approximately 23% of application demand and is the fastest-growing application, with a projected CAGR of approximately 12.1%. Its growth is linked directly to the economic value of reducing physical sample iterations.
Pattern Development accounted for approximately 21% and is projected to grow at 9.1% CAGR, while Fashion Visualization accounted for approximately 15% and is projected to grow at 9.8% CAGR. Other applications accounted for approximately 7% and are projected to grow at 7.5% CAGR.
End-User Analysis
By End User
Fashion Brands & Retailers accounted for approximately 45% of the end-user segment in 2025. These organizations have a direct economic incentive to reduce product-development cycles because they manage large collections, multiple colorways, seasonal launches and geographically distributed suppliers.
Browzwear identifies major fashion brands and retailers among its users and positions digital product creation across design, validation, selling and production.
Apparel Manufacturers accounted for approximately 29% and are projected to grow at 9.7% CAGR. Manufacturers benefit when 3D assets reduce ambiguity between brand specifications and factory execution.
Designers & Studios accounted for approximately 17% and are projected to grow at 9.4% CAGR, while Other end users represented approximately 9% and are projected to grow at 8.0% CAGR.
3D Fashion Design Software Market Regional Analysis
Asia-Pacific Holds the Largest Share as Apparel Manufacturing and Digital Product Development Expand Together
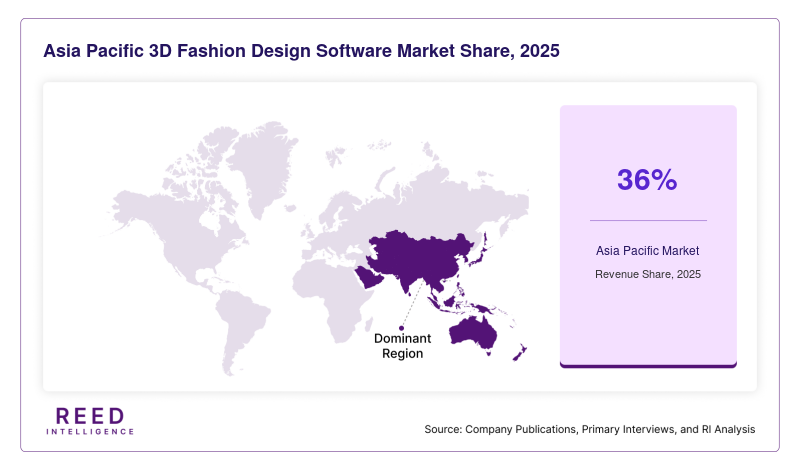
Asia-Pacific accounted for approximately 36% of the global market in 2025, making it the largest regional market. The region combines major apparel-production centers with expanding fashion-technology adoption.
The commercial mechanism is particularly strong because 3D tools can connect brands with geographically distributed suppliers and manufacturers. CLO's 2025 acquisition of swatchbook brought teams in Dongguan and Bengaluru into the CLO organization alongside its Los Angeles operations, reinforcing the importance of Asia within the company's digital-material ecosystem.
Asia-Pacific is projected to grow at approximately 10.2% CAGR, making it the fastest-growing region. Expansion is supported by apparel manufacturing, fashion exports, supplier digitization and growing use of digital product-development workflows.
North America Maintains a Large Market Through Enterprise Adoption and Software Innovation
North America accounted for approximately 27% of the global market in 2025 and is projected to grow at approximately 9.1% CAGR.
The region has a strong base of fashion brands, retailers, technology providers and software developers. CLO's swatchbook acquisition also strengthens its North American digital-material presence through the continued operation of the Los Angeles team.
Demand is increasingly linked to enterprise workflow integration rather than visualization alone. Partnerships connecting 3D design with PLM and other business systems provide a mechanism for larger organizations to embed digital product creation across multiple departments.
Europe Expands Through Established Fashion and Apparel Technology Ecosystems
Europe represented approximately 24% of the global market in 2025 and is projected to grow at approximately 8.9% CAGR.
The region has an established concentration of fashion brands, apparel manufacturers and luxury companies, creating demand for tools that improve product development and digital collaboration.
Lectra's continued development of Modaris illustrates the importance of technical patternmaking and industrialization within European fashion-technology ecosystems. The current Modaris platform integrates pattern creation, grading, industrialization and 3D prototyping.
Latin America Develops Through Apparel Manufacturing and Supplier Digitization
Latin America accounted for approximately 8% of the market in 2025 and is projected to grow at approximately 9.0% CAGR.
The region's opportunity is linked to apparel manufacturing and relationships with international brands. Digital garment development can reduce communication friction between brands and manufacturing partners by providing a common visual and technical reference.
Adoption is constrained by software costs, digital skills availability and differences in technology infrastructure across individual markets.
Middle East & Africa Represents an Emerging Market for Digital Fashion Development
Middle East & Africa accounted for approximately 5% of the market in 2025 and is projected to grow at approximately 8.0% CAGR.
Growth is supported by developing fashion, retail and luxury ecosystems and by increasing use of digital tools for design and visualization. The region's relatively smaller installed base means adoption depends heavily on software accessibility, training and local implementation partners.
3D Fashion Design Software Market Competitive Landscape
Competition is increasingly organized around the ability to provide an end-to-end digital product-development workflow, rather than simply rendering garments in three dimensions.
CLO Virtual Fashion has strengthened its position through garment simulation, digital materials and AI-related development. Its acquisition of swatchbook in July 2025 expanded its digital fabric database and brought additional material-management capabilities into the CLO ecosystem.
Browzwear competes through VStitcher, Stylezone and its broader integration ecosystem. Its technology-partner program supports integrations across PLM, DAM, merchandising, AI, rendering and automation, increasing the platform's relevance to enterprise workflows.
Key Market Players
3D Fashion Design Software Market Recent Developments
- July 2025 - CLO Virtual Fashion announced the acquisition of swatchbook, a digital-material solutions provider. CLO stated that the transaction would expand its fabric and material database and integrate swatchbook's material-sourcing and management capabilities into the CLO ecosystem. The swatchbook teams in Los Angeles, Dongguan and Bengaluru joined CLO's Materials division. The development strengthens the connection between garment simulation and digital material data. For the market, this increases the importance of comprehensive material libraries as a competitive feature of 3D fashion platforms.
- January 2025 - DeSL announced a partnership with Browzwear to deliver Browzwear's digital product-development technology directly within DeSL's PLM software. The integration allows teams to visualize color and material variations, annotate 3D models and collaborate within the product-development environment. The development expands the commercial role of 3D software from standalone design into enterprise product lifecycle management. It also reduces the separation between creative design and technical product-development data.
3D Fashion Design Software Market Segments
By Deployment
- Cloud-Based
- On-Premise
By Application
- Apparel Design
- Pattern Development
- Virtual Sampling
- Fashion Visualization
- Others
By End User
- Fashion Brands & Retailers
- Apparel Manufacturers
- Designers & Studios
- Others
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM