Aerospace Wire Harnesses Market Size, Share & Trends Analysis Report By Aircraft Type (Commercial Aircraft, Military Aircraft, Business & General Aviation and Helicopters), By Application (Avionics, Power Distribution, Lighting Systems, Flight Control Systems, Communication Systems and Others), By Material (Copper, Aluminum and Others), By Product Type (Standard Wire Harnesses, Customized Wire Harnesses and High-Temperature Wire Harnesses) and By Region (North America, Europe, Asia-Pacific, Lati
USD 3950
Aerospace Wire Harnesses Market Size
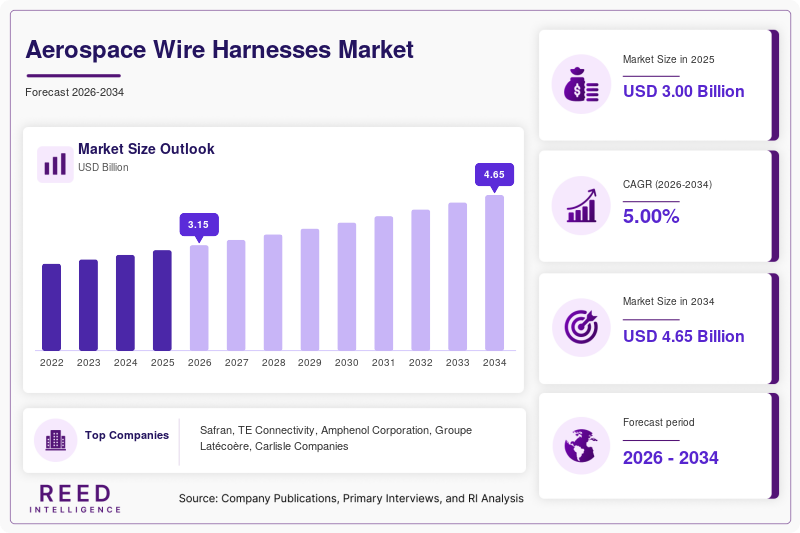
The global aerospace wire harnesses market was valued at USD 3.00 billion in 2025 and is projected to grow from USD 3.15 billion in 2026 to USD 4.65 billion by 2034, registering a CAGR of 5.00% during the forecast period from 2026 to 2034.
Aerospace wire harnesses are engineered assemblies of wires, cables, terminals, connectors, shielding and protective components used to distribute electrical power and transmit signals throughout aircraft. They form a critical part of aircraft electrical systems and support avionics, communications, navigation, lighting, propulsion controls, flight-control systems and cabin equipment.
The market is closely linked to aircraft production, fleet modernization, aircraft electrification, military aviation programs and the expansion of onboard electronics. Modern aircraft contain increasingly sophisticated electrical and electronic systems, increasing the complexity and quantity of wiring required.
Aerospace Wire Harnesses Market Drivers
Rising Aircraft Production Supports Wire Harness Demand
Increasing aircraft production directly drives demand for aerospace wire harnesses because every aircraft requires extensive electrical wiring across its airframe, engines, avionics and cabin systems.
Commercial aircraft programs account for a substantial portion of global wire-harness consumption, while military aircraft, helicopters and business jets provide additional demand.
As aircraft manufacturers increase production rates to address fleet replacement and passenger-air-travel growth, suppliers of aerospace electrical systems and harnesses are expected to benefit.
Increasing Aircraft Electrification Drives Market Growth
Aircraft manufacturers are increasingly replacing hydraulic, pneumatic and mechanical systems with electrically powered alternatives.
This trend toward more-electric aircraft increases electrical power requirements and consequently raises the need for power-distribution wiring, high-voltage cables, connectors and associated harness assemblies.
Electrification is particularly relevant to propulsion systems, environmental control, actuation, landing systems and auxiliary functions.
Growing Avionics Content Increases Wiring Complexity
Modern aircraft incorporate increasingly sophisticated avionics, communication, navigation, sensing and flight-management systems.
The expansion of electronic equipment creates demand for additional signal and power connections, while increasing requirements for electromagnetic compatibility, shielding and reliable routing.
As aircraft systems become more integrated, wire harnesses must accommodate higher data rates, power loads and increasingly constrained installation spaces.
Aerospace Wire Harnesses Market Restraints
High Aerospace Certification Requirements
Aerospace wire harnesses must meet stringent requirements relating to electrical performance, fire resistance, vibration, temperature, electromagnetic compatibility and mechanical durability.
Manufacturers must demonstrate consistent performance under demanding operating conditions. Qualification and certification can therefore require significant time and investment.
These requirements create barriers to entry and can increase product development costs.
Weight Reduction Creates Engineering Challenges
Aircraft manufacturers seek to minimize every unnecessary kilogram because lower weight can improve fuel efficiency and payload capability.
Traditional copper wiring provides excellent conductivity but can add substantial weight when used extensively.
Manufacturers therefore face the challenge of developing lighter harness assemblies without compromising conductivity, reliability, durability or safety.
Complex Assembly Processes Increase Manufacturing Costs
Aerospace harnesses often require highly customized configurations and extensive manual assembly.
Routing, connector termination, shielding, labeling and testing must meet detailed engineering specifications. As harness complexity increases, manufacturing labor and quality-control requirements also increase.
Aerospace Wire Harnesses Market Opportunities
Lightweight Wire Harnesses Create New Growth Opportunities
The aerospace industry's focus on fuel efficiency is encouraging manufacturers to adopt lightweight conductors, insulation materials and connectors.
Aluminum conductors, lightweight shielding and optimized routing can reduce harness weight while maintaining required electrical performance.
Suppliers capable of combining weight reduction with aerospace certification can benefit from increasing demand.
More-Electric Aircraft Create Demand for Advanced Harnesses
More-electric aircraft architectures require higher electrical power distribution capabilities.
This creates opportunities for harness manufacturers to develop systems designed for higher voltage, improved thermal performance and increased electromagnetic shielding.
The development of hybrid-electric and electric propulsion concepts could create additional long-term requirements for specialized electrical interconnect systems.
Defense Modernization Supports Demand for Customized Harnesses
Military aircraft increasingly incorporate sophisticated radar, electronic warfare, communication, surveillance and mission systems.
These systems require specialized wiring assemblies capable of operating under high vibration, temperature and electromagnetic-interference conditions.
Defense programs can therefore provide opportunities for customized, high-performance wire-harness manufacturers.
Aircraft Type Segment Analysis
Commercial Aircraft Hold the Largest Share
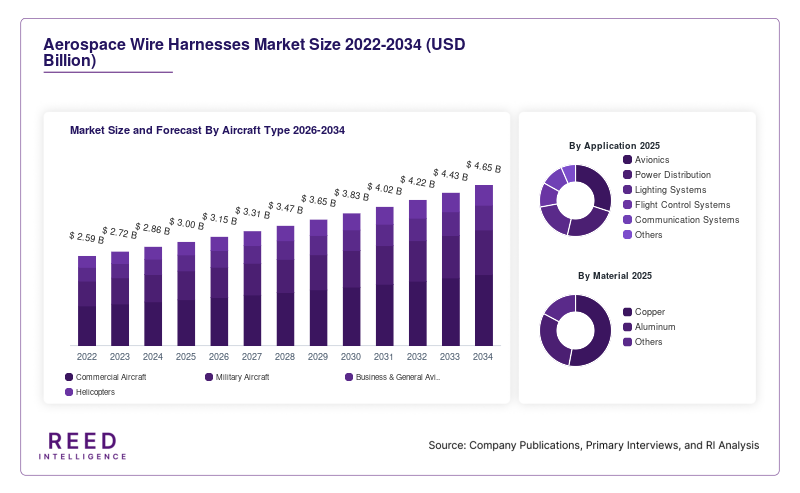
Commercial aircraft accounted for approximately 55% of the global aerospace wire harnesses market in 2025, making them the largest aircraft-type segment. Commercial aircraft contain extensive electrical networks supporting avionics, cabin systems, lighting, communications, flight controls and power distribution.
The expansion of commercial aircraft production and fleet modernization supports continued demand for wire-harness assemblies.
Military aircraft accounted for approximately 24% and are projected to grow at approximately 6.1% CAGR, making them the fastest-growing major aircraft-type segment. Defense modernization programs and the increasing electronic content of military platforms are supporting demand for advanced harness systems.
Business & general aviation represented approximately 13%, while helicopters accounted for approximately 8%.
Application Segment Analysis
Avionics Holds the Largest Share
Avionics accounted for approximately 29% of the market in 2025, making it the largest application segment. Avionics wiring supports navigation, flight management, communication, surveillance, sensing and other electronic systems.
The increasing number of onboard electronic systems is raising wiring requirements while also increasing demand for shielding and high-reliability interconnect solutions.
Power distribution accounted for approximately 23% and is projected to grow at approximately 6.3% CAGR, making it the fastest-growing major application segment. Increasing aircraft electrification is driving demand for power-distribution harnesses capable of supporting higher electrical loads.
Flight control systems represented approximately 18%, communication systems 14%, lighting systems 9%, and other applications approximately 7%.
Material Segment Analysis
Copper Holds the Largest Share
Copper accounted for approximately 72% of the aerospace wire-harness market in 2025, making it the dominant material. Copper provides high electrical conductivity, established aerospace qualification and compatibility with a wide range of connectors and electrical systems.
Its extensive installed base and well-established processing infrastructure continue to support its use.
Aluminum accounted for approximately 21% and is projected to grow at approximately 6.4% CAGR, making it the fastest-growing major material segment. Aluminum's lower density provides an attractive option for aircraft manufacturers seeking to reduce electrical-system weight.
Other materials represented approximately 7%.
Product Type Segment Analysis
Customized Wire Harnesses Hold the Largest Share
Customized wire harnesses accounted for approximately 49% of the market in 2025, making them the largest product segment. Aerospace platforms frequently require harness assemblies designed around aircraft-specific layouts, equipment configurations and electrical architectures.
Customization allows manufacturers to optimize routing, connectors, shielding and component integration for specific aircraft programs.
High-temperature wire harnesses accounted for approximately 22% and are projected to grow at approximately 6.6% CAGR, making them the fastest-growing major product segment. Increasing engine temperatures, electrification and demanding aerospace operating environments are driving demand for thermally resistant wiring solutions.
Standard wire harnesses represented approximately 29%.
Aerospace Wire Harnesses Market Regional Analysis
North America Holds the Largest Share
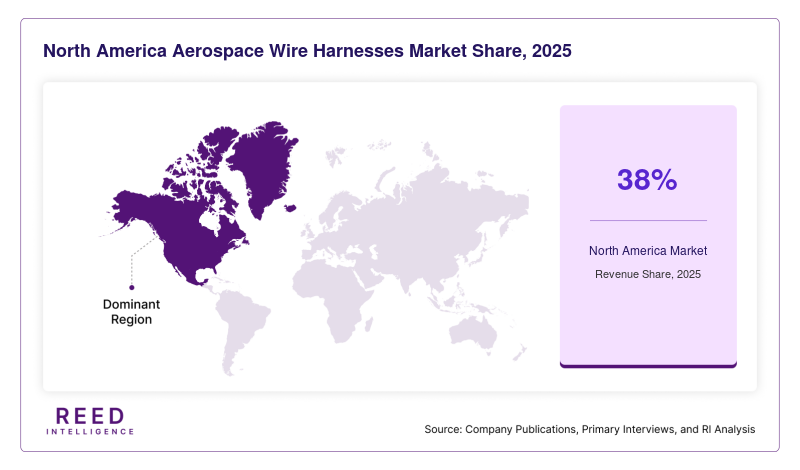
North America accounted for approximately 38% of the global aerospace wire harnesses market in 2025, making it the largest regional market. The region benefits from a large aerospace manufacturing ecosystem, extensive defense programs, major commercial aircraft production and a well-developed supplier base.
The United States represents a major center for aircraft electrical-system development and aerospace wire-harness manufacturing.
Asia-Pacific accounted for approximately 24% and is projected to grow at approximately 7.0% CAGR, making it the fastest-growing major region. Expanding commercial aviation fleets, aircraft production, defense modernization and aerospace supply-chain development are supporting regional demand.
Europe Maintains a Strong Aerospace Electrical Systems Industry
Europe accounted for approximately 29% of the market in 2025 and is projected to grow at approximately 4.8% CAGR.
The region has a well-established aerospace industry encompassing commercial aircraft, military aviation, helicopters and business aviation.
European manufacturers are also investing in electrification and lower-weight aircraft architectures, supporting demand for advanced wiring systems.
Asia-Pacific Is the Fastest-Growing Region
Asia-Pacific is projected to grow at approximately 7.0% CAGR through 2034. Rising air passenger traffic is encouraging fleet expansion, while domestic aerospace manufacturing capabilities are developing across China, India, Japan and other regional markets.
Defense spending and the modernization of military aircraft fleets are providing an additional source of demand.
The growth of regional aircraft manufacturing and MRO infrastructure is expected to strengthen the aerospace electrical-systems supply chain.
Latin America Shows Moderate Expansion
Latin America accounted for approximately 5% of the market in 2025 and is projected to grow at approximately 4.7% CAGR.
Commercial fleet renewal, regional aircraft operations and MRO activities support demand for replacement wire harnesses and electrical assemblies.
Middle East & Africa Represents an Emerging Market
Middle East & Africa accounted for approximately 4% of the market in 2025 and is projected to grow at approximately 5.6% CAGR.
Aircraft fleet expansion, airline investments, defense aviation programs and the development of regional MRO capabilities are supporting market opportunities.
Aerospace Wire Harnesses Market Competitive Landscape
Competition in the aerospace wire harnesses market is based on reliability, aerospace certification, customization capabilities, manufacturing quality, weight optimization, connector compatibility, delivery reliability and technical support.
Leading manufacturers are investing in automated harness assembly, lightweight materials, digital manufacturing systems and high-temperature electrical technologies.
Key Market Players
- Safran
- TE Connectivity
- Amphenol Corporation
- Groupe Latécoère
- Carlisle Companies
- Ametek
- Interconnect Systems International
- Glenair
- Radiall
- Nexans
Aerospace Wire Harnesses Market Recent Developments
- Safran continues to develop electrical and power-management technologies for aircraft as manufacturers transition toward more-electric architectures. The company's aerospace portfolio includes electrical systems, wiring and interconnection technologies supporting commercial and defense aircraft. The increasing electrification of aircraft systems is creating opportunities for suppliers that can provide lightweight and reliable electrical distribution solutions.
- TE Connectivity continues to introduce high-performance connectivity products designed for aerospace applications, including connectors, cable assemblies and high-reliability electrical interconnection components. The company's product development increasingly addresses weight reduction, harsh-environment performance and higher electrical and data requirements.
Aerospace Wire Harnesses Market Segments
By Aircraft Type
- Commercial Aircraft
- Military Aircraft
- Business & General Aviation
- Helicopters
By Application
- Avionics
- Power Distribution
- Lighting Systems
- Flight Control Systems
- Communication Systems
- Others
By Material
- Copper
- Aluminum
- Others
By Product Type
- Standard Wire Harnesses
- Customized Wire Harnesses
- High-Temperature Wire Harnesses
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM