Aluminum Nitride Ceramic Substrates Market Size, Share & Trends Analysis Report By Type (AlN-170, AlN-200 and Others), By Application (Power Electronics, RF/Microwave, LED Packaging, Automotive Electronics and Others), By Technology (Direct Bonded Copper, Direct Plated Copper, Active Metal Brazing and Others), By End User (Consumer Electronics, Automotive, Telecommunications, Industrial, Aerospace & Defense and Others) and By Region (North America, Europe, Asia-Pacific, Latin America, Middle Eas
USD 3950
Aluminum Nitride Ceramic Substrates Market Size
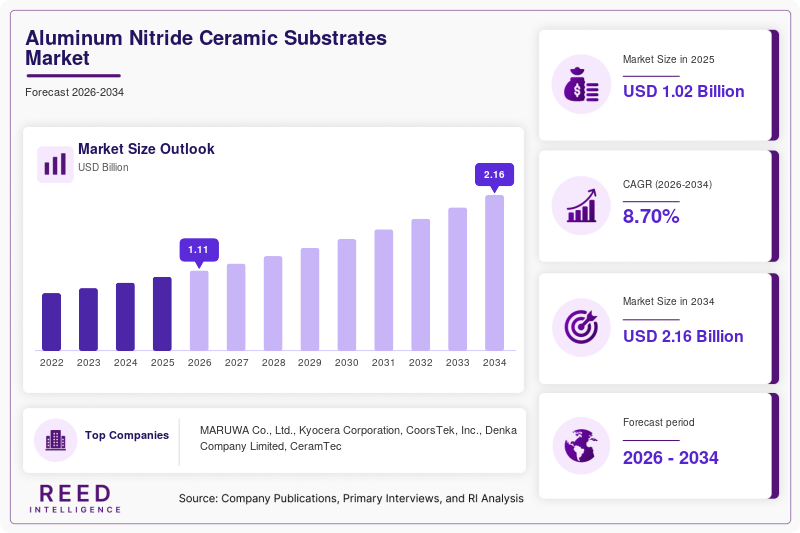
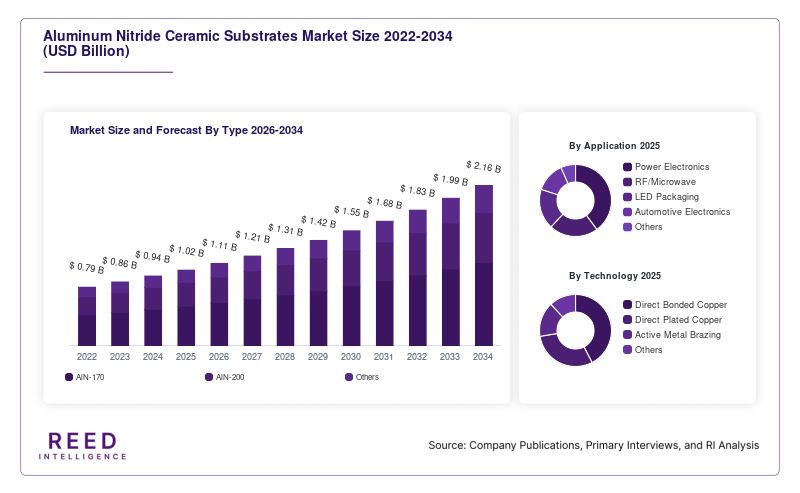
The global aluminum nitride ceramic substrates market was valued at USD 1.02 billion in 2025 and is projected to grow from USD 1.11 billion in 2026 to USD 2.16 billion by 2034, registering a CAGR of 8.70% during the forecast period from 2026 to 2034.
Aluminum nitride (AlN) ceramic substrates are advanced electronic substrate materials characterized by high thermal conductivity, electrical insulation, low thermal expansion and strong temperature stability. These properties make AlN suitable for high-power and high-frequency electronic systems where efficient heat dissipation and electrical isolation are required.
AlN substrates are increasingly used in power semiconductor modules, LED packaging, RF and microwave devices, automotive electronics and semiconductor manufacturing equipment. Demand is being supported by the increasing power density of electronic devices, electrification of vehicles, expansion of renewable-energy systems and adoption of wide-bandgap semiconductor technologies such as silicon carbide (SiC) and gallium nitride (GaN).
Aluminum Nitride Ceramic Substrates Market Drivers
Rising Demand for High-Performance Thermal Management
Increasing electronic power density is creating greater thermal-management requirements. AlN combines high thermal conductivity with electrical insulation, allowing manufacturers to dissipate heat while maintaining isolation between electrical components.
This makes AlN attractive for power modules, semiconductor packages, RF systems and other applications where conventional substrate materials may have thermal-performance limitations.
Growing Adoption of SiC and GaN Power Semiconductors
Wide-bandgap semiconductors such as SiC and GaN can operate at higher temperatures, voltages and switching frequencies than conventional silicon devices.
The resulting increase in thermal loads is supporting demand for advanced ceramic substrates capable of maintaining efficient heat transfer while providing electrical isolation.
Expansion of Electric Vehicles
Electric vehicles require power electronics for traction inverters, onboard chargers, DC-DC converters and other systems.
The growing use of high-power semiconductor modules in these systems is creating opportunities for AlN substrates, particularly where compact designs and efficient thermal dissipation are required. Automotive electronics is identified as one of the fastest-growing application areas in industry forecasts.
Increasing Demand for High-Power Electronics
Industrial motor drives, renewable-energy converters, grid equipment and high-power semiconductor systems increasingly require substrates that can handle high thermal loads.
AlN substrates provide a combination of thermal conductivity, electrical insulation and dimensional stability that supports these applications.
Aluminum Nitride Ceramic Substrates Market Restraints
High Manufacturing Costs
AlN substrates require specialized powder processing, forming, sintering and finishing technologies.
The strong covalent bonding of AlN can make densification difficult, while oxygen-related defects can negatively affect thermal and electrical performance. These manufacturing challenges increase processing complexity and costs.
Competition From Alternative Ceramic Substrates
AlN competes with alumina, silicon nitride and other ceramic substrate technologies.
Alumina benefits from lower cost and established high-volume manufacturing, while silicon nitride offers strong mechanical properties and thermal-cycling performance in demanding applications.
Supply Chain Concentration
High-performance AlN substrate manufacturing remains concentrated among specialized producers, particularly in Japan, North America, Europe and increasingly China.
The specialized nature of production and qualification requirements can create supply constraints for high-grade materials.
Aluminum Nitride Ceramic Substrates Market Opportunities
SiC-Based Power Module Expansion
The increasing adoption of SiC power devices is creating opportunities for AlN substrates in high-power automotive, industrial and renewable-energy applications.
AlN can support thermal management requirements associated with compact high-power modules.
AI and Data-Center Electronics
AI accelerators and advanced computing systems are increasing thermal-management requirements at the device and package level.
High-thermal-conductivity ceramic materials can provide opportunities in applications where heat dissipation and electrical isolation are both critical.
5G and RF Applications
RF and microwave systems require materials that can support high-frequency operation and thermal management.
AlN's thermal conductivity and electrical properties make it suitable for selected RF, microwave and communications packaging applications.
Development of Higher-Thermal-Conductivity Grades
Manufacturers are developing AlN materials with increasingly controlled microstructures and reduced defect concentrations.
Recent research has demonstrated improved thermal and mechanical properties through defect regulation and MgO modification, highlighting opportunities for higher-performance AlN substrates.
Type Segment Analysis
AlN-170 Holds the Largest Share
AlN-170 accounted for approximately 62% of the market in 2025, making it the dominant type segment. Its balance of thermal conductivity, electrical insulation, manufacturing maturity and cost makes it suitable for a broad range of electronic applications.
AlN-170 is widely used in power electronics, LED packaging and semiconductor-related applications.
AlN-200 accounted for approximately 28% and is projected to grow at approximately 9.8% CAGR, making it the fastest-growing major type segment. Higher thermal conductivity makes this grade increasingly relevant to high-power and high-density electronics.
Other grades represented approximately 10% of the market.
Application Segment Analysis
Power Electronics Holds the Largest Share
Power electronics accounted for approximately 42% of the market in 2025, making it the dominant application segment. AlN substrates are used in power modules and semiconductor packages because they combine thermal management with electrical insulation.
Demand is supported by electric vehicles, industrial drives, renewable-energy converters and increasingly sophisticated power-management systems.
Automotive electronics accounted for approximately 23% and is projected to grow at approximately 11.2% CAGR, making it the fastest-growing major application segment. Increasing electronic content per vehicle and the expansion of EV power electronics are supporting demand.
RF/microwave represented approximately 16%, LED packaging 12%, and other applications approximately 7%.
Technology Segment Analysis
Direct Bonded Copper Holds the Largest Share
Direct Bonded Copper (DBC) accounted for approximately 46% of the market in 2025, making it the leading technology segment. DBC provides a well-established approach for integrating ceramic substrates with copper layers in power electronic modules.
Direct Plated Copper accounted for approximately 25% and is projected to grow at approximately 10.1% CAGR, making it the fastest-growing major technology segment. DPC technology enables fine-pattern metallization and is increasingly relevant for miniaturized and high-density electronic packages.
Active Metal Brazing represented approximately 19%, while other technologies accounted for approximately 10%.
End-User Segment Analysis
Automotive Holds the Largest Share
Automotive accounted for approximately 29% of the market in 2025, making it the largest end-user segment. Increasing adoption of EVs, power inverters and advanced vehicle electronics is supporting AlN substrate demand.
Telecommunications accounted for approximately 17% and is projected to grow at approximately 9.6% CAGR, making it the fastest-growing major end-user segment. Expansion of high-frequency communications infrastructure and thermal requirements in RF systems are supporting demand.
Industrial users represented approximately 24%, consumer electronics 16%, aerospace & defense 9%, and other end users approximately 5%.
Aluminum Nitride Ceramic Substrates Market Regional Analysis
Asia-Pacific Holds the Largest Share
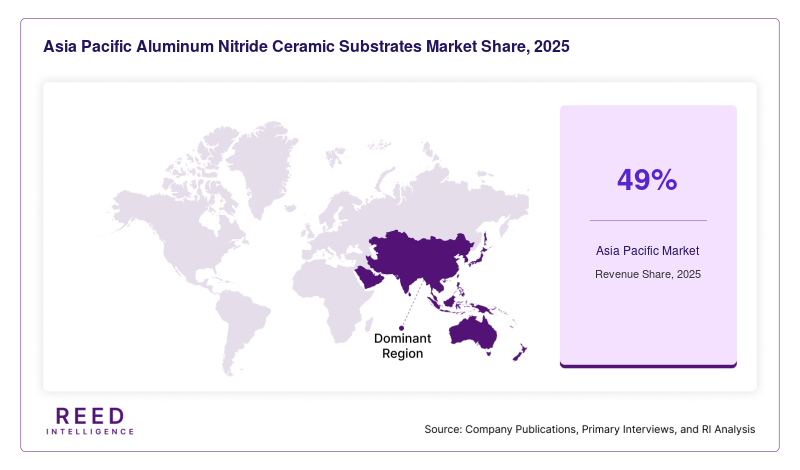
Asia-Pacific accounted for approximately 49% of the global aluminum nitride ceramic substrates market in 2025, making it the largest regional market.
The region benefits from a large semiconductor and electronics manufacturing base, substantial power-electronics production and the presence of major AlN substrate manufacturers. Japan is a particularly important market, while China is expanding its production capabilities and domestic demand. Industry sources identify Asia-Pacific as the leading region for AlN substrate demand.
Asia-Pacific is also the fastest-growing major region, with approximately 9.4% CAGR through 2034, supported by semiconductor manufacturing expansion, EV production, telecommunications infrastructure and investment in power electronics.
North America Maintains Strong Demand
North America accounted for approximately 22% of the market in 2025 and is projected to grow at approximately 8.1% CAGR.
Demand is supported by semiconductor manufacturing, aerospace and defense electronics, EV power systems, data-center infrastructure and advanced RF applications.
Europe Benefits From Automotive Electrification
Europe accounted for approximately 19% of the market in 2025 and is projected to grow at approximately 7.8% CAGR.
Automotive electronics, industrial power systems, renewable-energy equipment and high-reliability electronics are supporting demand. European ceramic manufacturers are also developing comprehensive substrate portfolios for power-electronics applications.
Latin America Shows Emerging Demand
Latin America accounted for approximately 6% of the market in 2025 and is projected to grow at approximately 6.7% CAGR.
Increasing adoption of industrial automation, telecommunications infrastructure and electric mobility is creating opportunities for advanced electronic substrates.
Middle East & Africa Represents an Emerging Market
Middle East & Africa accounted for approximately 4% of the market in 2025 and is projected to grow at approximately 6.3% CAGR.
Demand is supported by telecommunications infrastructure, industrial modernization, renewable-energy projects and increasing electronics deployment.
Aluminum Nitride Ceramic Substrates Market Competitive Landscape
Competition in the aluminum nitride ceramic substrates market is based on thermal conductivity, electrical insulation, mechanical strength, substrate flatness, metallization compatibility, reliability, manufacturing consistency, customization capabilities and cost.
The industry has significant technical entry barriers because manufacturers must maintain tight control over powder purity, sintering, microstructure, metallization and thermal performance. Industry sources identify Japanese manufacturers as particularly influential, with Chinese producers increasing capacity and competing on cost and regional supply.
Key Market Players
- MARUWA Co., Ltd.
- Kyocera Corporation
- CoorsTek, Inc.
- Denka Company Limited
- CeramTec
- Toshiba Materials Co., Ltd.
- Rogers Corporation
- TD Power Materials
- Ferrotec Holdings Corporation
- Fujian Huaqing Electronic Material Technology Co., Ltd.
Aluminum Nitride Ceramic Substrates Market Recent Developments
- In 2026, CeramTec highlighted its ceramic substrate portfolio for semiconductor manufacturing and power electronics at SEMICON India. The portfolio includes AlN alongside alumina, zirconia-toughened alumina and silicon nitride substrates, reflecting continued demand for high-performance thermal-management materials.
- HexaTech expanded its single-crystal AlN substrate portfolio in 2026, including a 3-inch substrate offering, targeting high-voltage and high-frequency electronic and power/RF applications.
Aluminum Nitride Ceramic Substrates Market Segments
By Type
- AlN-170
- AlN-200
- Others
By Application
- Power Electronics
- RF/Microwave
- LED Packaging
- Automotive Electronics
- Others
By Technology
- Direct Bonded Copper
- Direct Plated Copper
- Active Metal Brazing
- Others
By End User
- Consumer Electronics
- Automotive
- Telecommunications
- Industrial
- Aerospace & Defense
- Others
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM