Assisted Reproductive Technology Market Size, Share & Trends Analysis Report By Procedure (In Vitro Fertilization (IVF), Intracytoplasmic Sperm Injection (ICSI), Frozen Embryo Transfer, Cryopreservation, Donor & Other ART Procedures), By End User (Fertility Clinics, Hospitals, IVF Centers, Research & Academic Institutions) and By Region (North America, Europe, Asia-Pacific, Middle East and Africa, LATAM) Forecasts, 2026–2034
USD 3950
Assisted Reproductive Technology Market Size
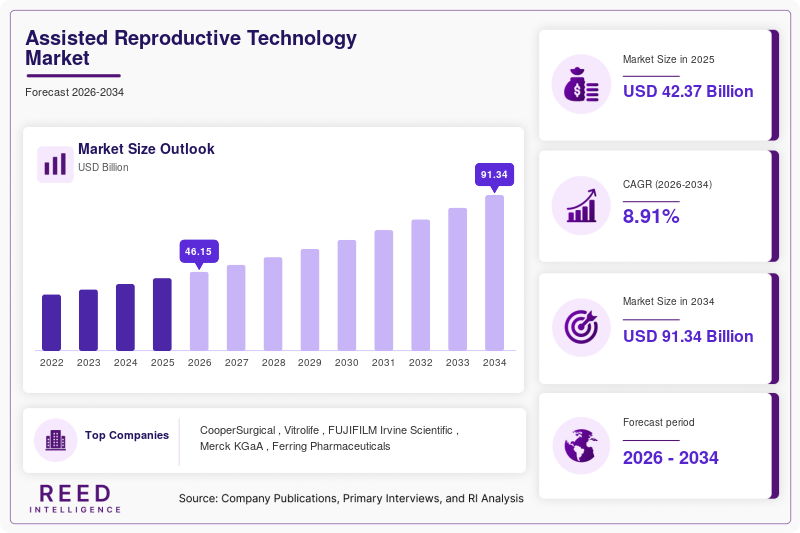
The Assisted Reproductive Technology Market was valued at USD 42.37 billion in 2025 and is estimated at USD 46.14 billion in 2026. The market is projected to reach USD 91.33 billion by 2034, expanding at a CAGR of 8.91% during 2026–2034.
Assisted reproductive technology is moving from a narrowly defined IVF service market toward a broader fertility-care ecosystem encompassing ovarian stimulation, oocyte retrieval, fertilization, embryo culture, genetic testing, cryopreservation, embryo transfer, donor programs and laboratory-management technologies. The commercial mechanism is therefore increasingly linked to the number of treatment cycles as well as the number and complexity of laboratory services attached to each cycle.
The underlying need remains substantial. The World Health Organization estimates that infertility affects approximately one in six people of reproductive age at some point, while also identifying affordability, limited access, shortages of trained personnel and inadequate equipment as persistent barriers to fertility care.
Assisted Reproductive Technology Market Drivers
Rising Demand for Infertility Diagnosis and Treatment
The fundamental driver is the large and persistent need for infertility care. WHO estimates that infertility affects about one in six people of reproductive age and identifies substantial gaps between demand and access to treatment.
As more patients enter fertility-care pathways, demand extends beyond IVF itself into ovarian stimulation, oocyte retrieval, embryo culture, genetic testing, cryopreservation and subsequent frozen transfers. The market therefore benefits from the cumulative nature of modern treatment pathways: a single clinical episode can generate demand for several laboratory and procedural services rather than only one intervention.
The commercial effect is particularly relevant for fertility clinics and specialized IVF centers because broader treatment pathways increase utilization of embryology laboratories, cryostorage infrastructure and reproductive-genetics services.
Expansion of Embryo Cryopreservation and Frozen Treatment Cycles
Cryopreservation has become an important component of ART because eggs and embryos can be preserved for later treatment. CDC explicitly includes egg and embryo freezing within the ART definition, while its U.S. surveillance system separately tracks egg and embryo banking.
This changes the economics of fertility treatment because demand does not necessarily end after an initial retrieval or fertilization cycle. Stored embryos can support later frozen-embryo-transfer procedures, while fertility preservation allows treatment demand to be deferred rather than lost.
The resulting opportunity extends to vitrification media, cryostorage systems, embryo-transfer products, laboratory software and monitoring infrastructure.
Increasing Use of Laboratory and Embryo-Selection Technologies
ART laboratories are becoming more technology intensive. ASRM identifies developments spanning genomics, transcriptomics, proteomics, metabolomics, time-lapse imaging and artificial intelligence in embryo evaluation.
Commercially, this creates a shift from basic IVF consumables toward integrated laboratory solutions. Time-lapse systems, embryo-analysis software, genetic testing and decision-support tools can become part of the clinic's workflow rather than standalone optional technologies. Vitrolife, for example, markets time-lapse incubation together with AI-based embryo-analysis tools such as iDAScore.
Assisted Reproductive Technology Market Restraints
High Treatment Costs and Unequal Access
Affordability remains one of the strongest constraints on ART adoption. WHO states that infertility treatment is frequently paid out-of-pocket and that in some settings even a single IVF cycle can represent a substantial share of household income.
This creates a gap between clinical need and addressable commercial demand. Patients may require ART but postpone treatment, select less expensive alternatives or discontinue treatment after unsuccessful cycles. Markets with stronger insurance or public financing can therefore convert underlying infertility prevalence into treatment volumes more effectively than markets where patients bear most costs directly.
Clinical, Regulatory and Laboratory Complexity
ART requires specialized reproductive endocrinologists, embryologists, laboratory infrastructure, controlled environments and regulated handling of reproductive material. WHO specifically identifies shortages of equipment and trained personnel as barriers to universal fertility-care access.
Regulatory requirements also vary between jurisdictions, particularly around embryo handling, genetic testing, donor gametes, cryostorage and treatment eligibility. These differences can increase operational costs and slow the introduction of new technologies.
Assisted Reproductive Technology Market Opportunities
Fertility Preservation and Cryostorage
Fertility preservation creates a longer-duration commercial relationship between patients and ART providers. Egg and embryo banking can generate recurring demand for vitrification products, cryogenic storage, monitoring and eventual thawing and transfer services. CDC's surveillance framework explicitly recognizes egg and embryo banking as part of ART activity.
AI-Enabled Embryo Assessment
AI-assisted embryo evaluation is an emerging technology opportunity within the laboratory segment. ASRM recognizes AI and other advanced technologies as part of the expanding toolkit for embryo selection, while commercial systems are being developed to automate image assessment and support embryologist decision-making.
The opportunity is not simply replacing embryologists; rather, it is improving workflow consistency, creating structured embryo-development data and integrating imaging with laboratory information systems.
Expansion of Fertility Care in Underserved Markets
WHO's 2025 infertility guideline calls for countries to integrate fertility care into health strategies and financing and emphasizes cost-effective approaches across the treatment pathway.
For ART companies, this creates an opportunity for lower-cost IVF protocols, scalable laboratory equipment, training, decentralized fertility services and technologies that reduce the infrastructure burden of establishing new IVF centers.
Assisted Reproductive Technology Market Segment Analysis
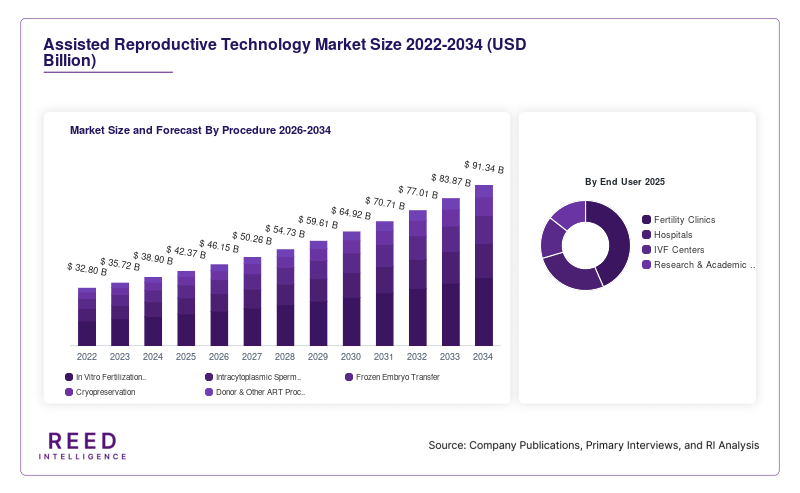
IVF is modelled as the largest procedure segment, accounting for approximately 46% of the 2025 market, equivalent to about USD 19.49 billion. The segment remains central because IVF is the most common ART procedure and provides the underlying clinical pathway for several associated services, including fertilization, embryo culture, embryo transfer and cryopreservation.
Using an internally modelled 8.5% CAGR, the IVF segment would reach approximately USD 40.61 billion by 2034 under the supplied global market framework.
ICSI Is Among the Faster-Growing Procedure Segments
ICSI is modelled at approximately 24% of the 2025 market, or USD 10.17 billion, with an internally assigned 9.5% CAGR. Its commercial relevance comes from its integration into IVF laboratory workflows, particularly where clinics use micromanipulation and specialized fertilization procedures.
The segment's growth is supported by continued development of specialized laboratory equipment, micro-tools, culture media and embryology expertise. CooperSurgical, for example, maintains products spanning ICSI, biopsy, holding and hatching applications.
Frozen Embryo Transfer Expands the Recurring Treatment Cycle
Frozen embryo transfer is modelled at 13% of the 2025 market, representing approximately USD 5.51 billion. Its importance is linked to the growing role of cryopreserved embryos in ART pathways, creating treatment demand beyond the initial retrieval and embryo-development cycle.
Cryopreservation Supports Long-Term ART Utilization
Cryopreservation is modelled at 10% of the 2025 market, or approximately USD 4.24 billion. It encompasses technologies and services used to preserve eggs and embryos for future treatment. CDC identifies egg and embryo cryopreservation as part of ART and separately tracks egg/embryo banking activity.
Donor and Other ART Procedures Form a Specialized Segment
Donor and other ART procedures are modelled at 7% of the 2025 market, equivalent to approximately USD 2.97 billion. This category includes treatment pathways involving donor eggs or embryos and other less prevalent ART approaches.
End-User Analysis
Fertility clinics represent the core end-user environment because they combine patient management with specialized embryology laboratories, reproductive endocrinology and embryo-transfer capabilities. The concentration of procedures in dedicated fertility centers also supports demand for integrated equipment, consumables, software and cryostorage.
Hospitals remain important where fertility services are integrated with reproductive medicine, gynecology and broader women's-health services. Hospital-based ART can be particularly relevant in markets where fertility care is connected to public healthcare systems or tertiary medical centers.
Specialized IVF centers have a strong incentive to invest in laboratory automation, embryo culture systems, cryopreservation and reproductive genetics because these technologies directly affect laboratory workflow and treatment capacity.
Academic institutions contribute to development and validation of embryo culture, reproductive genetics, cryobiology, imaging and AI-based assessment technologies. Their role is particularly important as newer technologies require clinical evidence before broad adoption.
Assisted Reproductive Technology Market Regional Analysis
North America Assisted Reproductive Technology Market
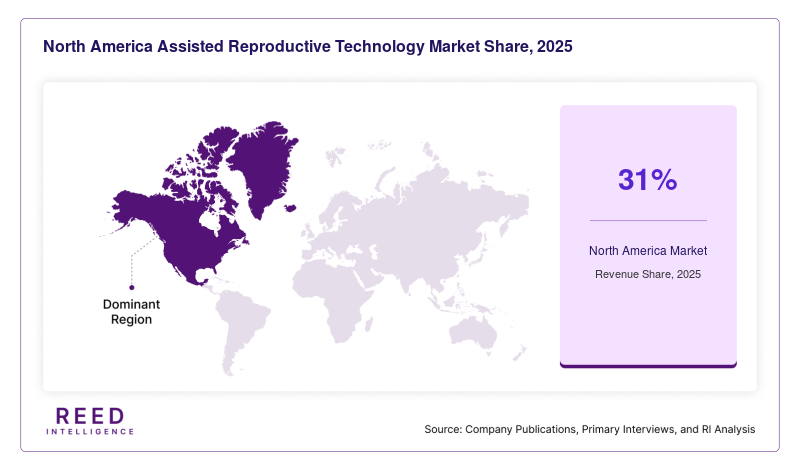
North America is modelled to account for approximately 31% of the 2025 market, equivalent to USD 13.13 billion. The region benefits from an established ART infrastructure, extensive fertility-clinic networks, sophisticated embryology laboratories and relatively strong adoption of reproductive-genetics and laboratory technologies. U.S. ART activity is systematically monitored through CDC's National ART Surveillance System, which reported 435,426 ART cycles in 2022 across 457 reporting clinics.
The U.S. market also demonstrates the increasing importance of frozen treatment and fertility preservation, while clinic-level success-rate reporting creates greater transparency around treatment outcomes.
Europe Assisted Reproductive Technology Market
Europe is modelled at approximately 26% of the 2025 market, representing USD 11.02 billion. The region has a mature fertility-care ecosystem and strong clinical and research infrastructure. European demand is supported by established IVF centers, reproductive genetics, cryopreservation and laboratory technologies, although reimbursement structures and ART regulations vary substantially between countries.
This regulatory diversity creates both market complexity and opportunities for suppliers capable of meeting different national clinical and compliance requirements.
Asia-Pacific Assisted Reproductive Technology Market
Asia-Pacific is modelled at approximately 28% of the 2025 market, or USD 11.86 billion, making it the fastest-growing regional allocation in the model at a 10.2% CAGR. Growth is supported by expanding fertility-clinic infrastructure, increasing awareness of infertility treatment and the development of specialized reproductive-health services.
The region is also becoming increasingly relevant for ART equipment and consumables suppliers. CooperSurgical, for example, markets fertility products across China, Australia and other Asia-Pacific markets and maintains a dedicated India operation covering products and services across the ART pathway.
Latin America Assisted Reproductive Technology Market
Latin America is modelled at approximately 8% of the 2025 market, equivalent to USD 3.39 billion. The region offers expansion potential as fertility services become more available through private clinics and specialist reproductive centers. Market development, however, remains dependent on treatment affordability, specialist availability, reimbursement and national regulatory frameworks.
Middle East and Africa Assisted Reproductive Technology Market
The Middle East and Africa are modelled at approximately 7% of the 2025 market, or USD 2.97 billion. Demand is concentrated in markets with established specialist fertility centers, while broader regional adoption is constrained by differences in healthcare infrastructure, affordability, regulation and availability of trained embryologists.
Assisted Reproductive Technology Market Competitive Landscape
The competitive structure of the ART market extends across fertility equipment, culture media, cryopreservation, laboratory systems, reproductive genetics, pharmaceuticals and clinical services, rather than being controlled by a single product category.
CooperSurgical has a broad fertility portfolio covering IVF media, laboratory equipment, micromanipulation, cryopreservation, genetic services and ART management. Its 2024 SEC filing identifies Vitrolife, FUJIFILM Irvine Scientific, Hamilton Thorne and other providers among its fertility-market competitors.
Vitrolife is particularly active in embryo-culture, time-lapse imaging and embryo-analysis technologies. Its portfolio combines incubation hardware with software-based embryo evaluation and AI-supported analysis.
Key Market Players
- CooperSurgical
- Vitrolife
- FUJIFILM Irvine Scientific
- Merck KGaA
- Ferring Pharmaceuticals
- Organon
- Cook Medical
- Hamilton Thorne
- Natera
- Sartorius
Assisted Reproductive Technology Recent Market Developments
- WHO issued its first global guideline on infertility in November 2025, providing 40 recommendations covering prevention, diagnosis and treatment and calling for stronger integration of fertility care into national health systems and financing.
- AI-supported embryo assessment is becoming commercially integrated into IVF laboratory workflows, with technologies such as Vitrolife's iDAScore designed to automate embryo-image analysis and support embryo prioritization.
Assisted Reproductive Technology Market Segments
By Procedure
- In Vitro Fertilization (IVF)
- Intracytoplasmic Sperm Injection (ICSI)
- Frozen Embryo Transfer
- Cryopreservation
- Donor & Other ART Procedures
By End User
- Fertility Clinics
- Hospitals
- IVF Centers
- Research & Academic Institutions
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM