CCS in Power Generation Market Size, Share Demand Report By Technology (Post-Combustion Capture, Pre-Combustion Capture, Oxy-Fuel Combustion Capture), By Application (Coal-Fired Power Plants, Natural Gas Power Plants, Biomass Power Plants), Regional Insights & Segment Forecasts, 2026–2034
USD 3950
CCS in Power Generation Market Size
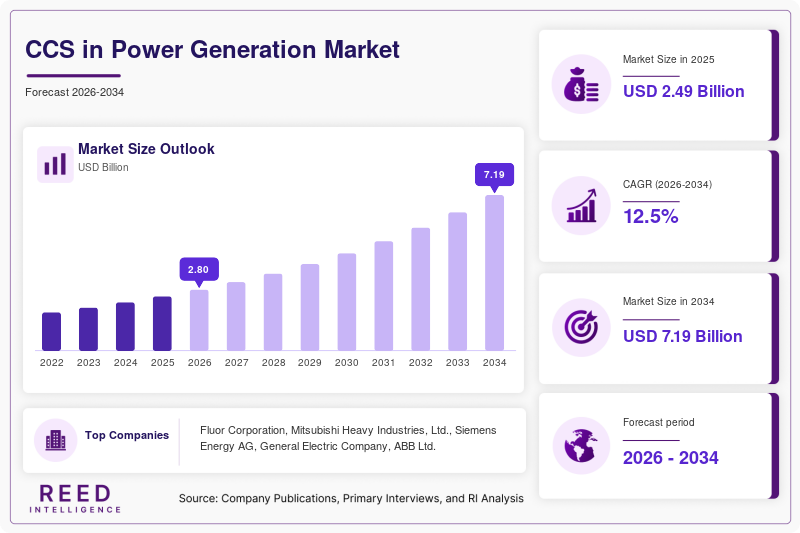
CCS in Power Generation market size is projected at USD 2.8 billion in 2026 and is expected to hit USD 6.5 billion by 2034 with a CAGR of 12.5% during the forecast period. The increasing global focus on carbon neutrality, stricter emission regulations, and the need to decarbonize existing fossil fuel power plants underpin market expansion. This report delivers a comprehensive analysis of the CCS in Power Generation market, including segmentation by technology and application, competitive dynamics, and regional growth patterns, equipping stakeholders with critical intelligence. The CCS in Power Generation market continues to demonstrate robust growth potential, fueled by the global transition toward low-carbon energy systems and the increasing deployment of carbon capture, utilization, and storage (CCUS) technologies as a critical tool for achieving net-zero emissions.
Carbon Capture and Storage (CCS) in power generation refers to the suite of technologies designed to capture carbon dioxide (CO2) emissions from power generation sources, transport the captured CO2, and securely store it underground or utilize it in various industrial processes. This market is a critical component of global climate change mitigation strategies, enabling the continued operation of fossil fuel-based power plants while significantly reducing their environmental impact. The global installed carbon capture capacity in the power sector reached 45 million tons per annum (Mtpa) in 2025, reflecting significant growth from 32 Mtpa in 2022. Adoption patterns reveal that the coal-fired power plant segment dominates CCS deployment, accounting for 52% of total capacity, followed by natural gas power plants at 28%, and biomass power plants at 20%. The CCS in Power Generation market's trajectory is closely linked to the global energy transition, with the International Energy Agency (IEA) projecting that CCS will need to contribute 15% of cumulative emissions reductions by 2050 to achieve climate goals.
CCS in Power Generation Market Trends
Increasing Integration of CCS with Renewable Energy Systems
The CCS in Power Generation market is witnessing a significant trend toward the integration of CCS with renewable energy systems, particularly in hybrid configurations that combine biomass power generation with carbon capture (BECCS). BECCS capacity grew to 9 Mtpa in 2025, a year-on-year increase of 20%, as 15% of new CCS projects announced in 2025 featured BECCS configurations. Adoption rates of CCS in biomass power plants reached 30% in Europe, with this figure projected to exceed 45% by 2030 as the technology matures. Sector-specific demand is particularly strong in countries with ambitious negative emissions targets, where 40% of new CCS projects specify BECCS applications. The CCS in Power Generation market's trend toward BECCS integration is reinforced by the growing recognition of the need for negative emissions technologies to achieve net-zero targets and the increasing availability of sustainable biomass feedstocks.
Technological Advancements in Capture Efficiency and Cost Reduction
Technological innovations in capture materials and process design are reshaping the CCS in Power Generation market, with advances in solvent chemistry, membrane technology, and sorbent materials leading to significant reductions in energy consumption and costs. The adoption rate of advanced solvents has grown to 35% of total capture capacity in 2025, up from 18% in 2022, driven by their ability to reduce regeneration energy by 20-30%. Overall capture costs for post-combustion technology have declined by 15% since 2022, from USD 60-80 per ton CO2 to USD 50-65 per ton CO2, with further reductions expected. The CCS in Power Generation market's innovation landscape is further characterized by the development of modular and scalable capture units, which can reduce installation costs by up to 25% and enable faster deployment, representing a growing segment projected to reach USD 1.5 billion by 2028.
CCS in Power Generation Market Drivers
The CCS in Power Generation market's expansion is primarily driven by the increasing stringency of global climate policies, with 75 countries having implemented or announced net-zero targets, creating a regulatory imperative for emissions reduction in the power sector. The global carbon market, valued at USD 95 billion in 2025 and growing at a CAGR of 15%, provides economic incentives for CCS deployment, with carbon prices in the EU ETS averaging USD 90 per ton CO2. The growing demand for dispatchable, low-carbon power, as renewable energy penetration increases, has made CCS a critical technology for providing reliable, on-demand electricity without emissions. Additionally, the significant investment in CCS infrastructure, with over USD 50 billion committed globally since 2023, is accelerating deployment. The CCS in Power Generation market's growth is further reinforced by the increasing availability of government subsidies and tax credits, such as the US 45Q tax credit, which provides up to USD 85 per ton CO2 stored, making many projects economically viable.
CCS in Power Generation Market Restraints
Despite favorable growth prospects, the CCS in Power Generation market faces significant constraints, primarily related to the high capital and operating costs of CCS technology, which can add 20-30% to the cost of electricity from a power plant. The energy penalty associated with CCS, which typically consumes 10-20% of a plant's output, reduces overall efficiency and economics. Technical challenges in CO2 transport and storage, including the need for extensive pipeline networks and the identification of suitable geological storage sites, create significant project complexity and risk. The CCS in Power Generation market's growth is also tempered by the long lead times (5-10 years) for project development and the limited public acceptance of CO2 storage in some regions.
CCS in Power Generation Market Opportunities
The CCS in Power Generation market presents significant opportunities in the rapidly expanding hydrogen economy, where CCS can be integrated with natural gas power plants to produce low-carbon hydrogen. The global hydrogen market is projected to reach USD 200 billion by 2030, with CCS-enabled hydrogen production expected to capture a 20-30% share. Emerging opportunities also exist in the development of CCS clusters and hubs, where multiple power plants share CO2 transport and storage infrastructure, significantly reducing costs through economies of scale. The CCS in Power Generation market's opportunity profile is further enhanced by the growing trend toward direct air capture (DAC) and carbon removal, which can utilize the same transport and storage infrastructure, creating synergies and additional revenue streams.
Challenges in CCS in Power Generation Market
The CCS in Power Generation market faces persistent challenges related to the financial viability of projects, particularly in regions without strong carbon pricing or regulatory support. The high upfront capital requirements, ranging from USD 500 million to over USD 2 billion for a large-scale project, create significant financial risk and require long-term revenue certainty. Securing project financing remains a significant challenge, with only 35% of announced CCS projects having reached a final investment decision (FID). Additionally, the CCS in Power Generation market is challenged by the complexity of integrating CCS with existing power plants, requiring significant plant modifications and potential downtime for installation, adding to project costs and timelines.
CCS in Power Generation Market Segmentation
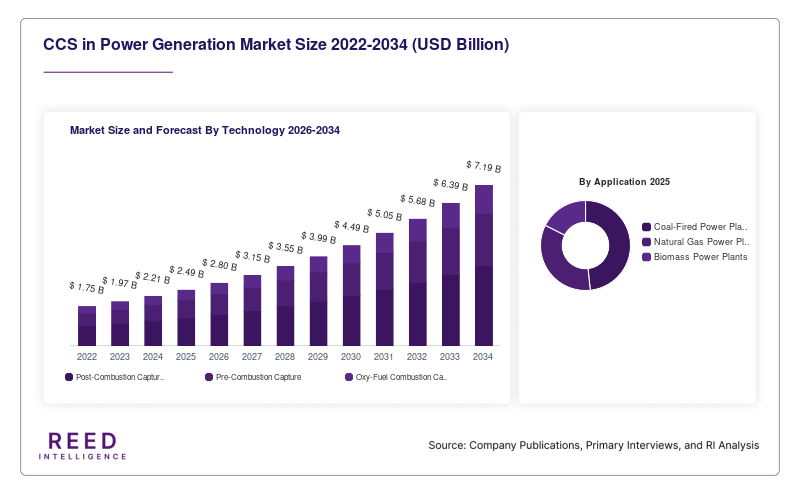
The CCS in Power Generation market is segmented by Technology and Application to provide a comprehensive market perspective. By Technology, Post-Combustion Capture dominates with a 58% market share, driven by its applicability to existing power plants. The Application segment is led by Coal-Fired Power Plants, which accounts for 52% of total capacity, followed by Natural Gas Power Plants at 28%, and Biomass Power Plants at 20%.
By Technology
Post-Combustion Capture represents the largest segment in the CCS in Power Generation market, commanding a 58% share, with an installed capacity of 26 Mtpa in 2025. This technology involves capturing CO2 from the flue gas after combustion using chemical solvents, typically amines. Technical specifications include capture rates of 85-95%, energy consumption of 3.0-4.5 GJ per ton CO2, and operating costs of USD 40-60 per ton CO2. The CCS in Power Generation market's post-combustion segment is driven by its ability to be retrofitted to existing power plants.
Pre-Combustion Capture captures a 24% share of the CCS in Power Generation market, with an installed capacity of 11 Mtpa in 2025. This technology involves converting fuel into a syngas before combustion, removing CO2 from the syngas stream. Technical specifications include capture rates of 85-90%, energy consumption of 2.5-3.5 GJ per ton CO2, and higher capital costs but lower operating costs. The CCS in Power Generation market's pre-combustion segment is characterized by its application in integrated gasification combined cycle (IGCC) plants.
Oxy-Fuel Combustion Capture represents the remaining 18% of the CCS in Power Generation market, with an installed capacity of 8 Mtpa in 2025. This technology involves burning fuel in oxygen rather than air, producing a flue gas rich in CO2 that can be easily captured. Technical specifications include capture rates of 90-98%, energy consumption of 4.0-5.5 GJ per ton CO2, and significant oxygen production costs. The CCS in Power Generation market's oxy-fuel segment is growing at a moderate CAGR, driven by its application in new-build power plants.
By Application
Coal-Fired Power Plants dominates the CCS in Power Generation market, accounting for 52% of total capacity, representing 23 Mtpa in 2025. This segment includes CCS retrofits to existing coal plants and new-build integrated gasification combined cycle (IGCC) facilities. Usage penetration in the global coal fleet exceeds 2%, with this figure projected to reach 5% by 2030 as more projects are deployed. The CCS in Power Generation market's coal segment is driven by the need to reduce emissions from the existing coal fleet, particularly in Asia.
Natural Gas Power Plants accounts for 28% of the CCS in Power Generation market, with a capacity of 13 Mtpa in 2025. This segment encompasses CCS on combined cycle gas turbine (CCGT) plants, where the lower CO2 concentration in flue gas presents technical challenges but also lower capture costs. The segment is growing at the fastest CAGR of 15%, driven by the increasing share of natural gas in the global power mix and the need to decarbonize existing gas plants. The CCS in Power Generation market's natural gas segment is characterized by its focus on cost-effective capture technologies.
Biomass Power Plants represents the remainder of the CCS in Power Generation market, accounting for 20% of total capacity, with a capacity of 9 Mtpa in 2025. This segment includes BECCS, which offers the potential for negative emissions. The segment is projected to grow at a CAGR of 18% through 2034, driven by the increasing focus on carbon removal and the availability of sustainable biomass. The CCS in Power Generation market's biomass segment is characterized by its focus on sustainability and negative emissions certification.
CCS in Power Generation Market Regional Outlook
North America CCS in Power Generation Market
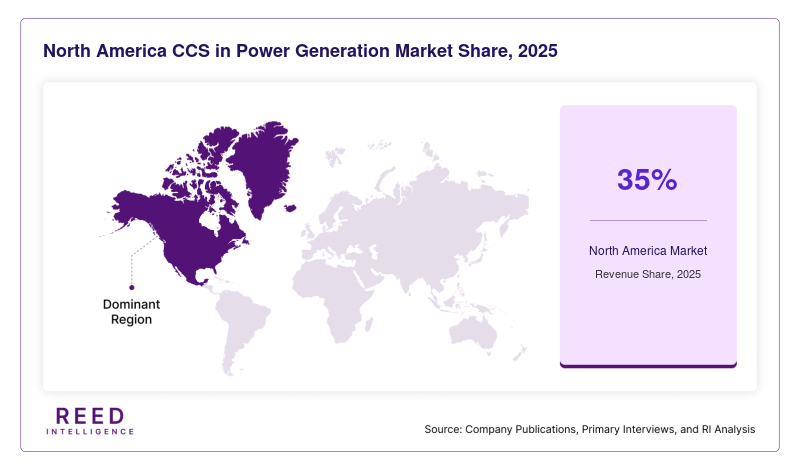
Leads the CCS in Power Generation market, commanding a 35% share, with an installed capacity of 16 Mtpa in 2025. The United States is the primary driver, accounting for 80% of regional capacity, driven by strong government support (45Q tax credits) and significant industrial activity. The North American CCS in Power Generation market is characterized by its focus on innovation and project development.
Europe CCS in Power Generation Market
Represents the second-largest market, capturing a 28% share with an installed capacity of 13 Mtpa in 2025. The UK, Norway, and the Netherlands collectively represent 60% of the regional capacity, driven by strong climate policies and access to offshore storage. The European CCS in Power Generation market is characterized by its focus on BECCS and negative emissions.
Asia-Pacific CCS in Power Generation Market
Accounts for 25% of the global CCS in Power Generation market, with an installed capacity of 11 Mtpa in 2025. China, Australia, and Japan are the primary drivers, accounting for 70% of regional capacity, driven by the large coal fleet and growing policy support. The Asia-Pacific CCS in Power Generation market is projected to grow at the fastest CAGR of 14% through 2034, presenting attractive opportunities for market expansion.
Middle East & Africa and Latin America CCS in Power Generation Market
Together account for the remaining 12% of the CCS in Power Generation market, with Saudi Arabia leading the Middle East market and Brazil leading the Latin American market. Both regions are projected to grow at CAGRs exceeding 12%, driven by increasing energy investments and decarbonization efforts.
Top players in CCS in Power Generation Market
- Fluor Corporation
- Mitsubishi Heavy Industries, Ltd.
- Siemens Energy AG
- General Electric Company
- ABB Ltd.
- Schlumberger Limited
- Shell plc
- Exxon Mobil Corporation
- Equinor ASA
- TotalEnergies SE
- Aker Solutions ASA
- Linde plc
- Honeywell International Inc.
- BASF SE
- Veolia Environnement S.A.
Fluor Corporation
Fluor holds a dominant position in the CCS in Power Generation market, with an estimated 18% share of the engineering, procurement, and construction (EPC) services for CCS projects. The company's expertise in amine-based capture technology and its experience with over 50 CCS projects globally have solidified its leadership position. Fluor's market leadership is reinforced by its proprietary Econamine FG PlusSM technology, which offers lower energy consumption and reduced operating costs. Fluor commands over 25% of the North American EPC market and 15% of the European market for CCS in power generation.
Mitsubishi Heavy Industries, Ltd.
Mitsubishi Heavy Industries (MHI) is a leading technology provider in the CCS in Power Generation market, commanding approximately 15% of the global capture technology market. The company's portfolio includes its proprietary KS-1 solvent technology, which offers high capture efficiency and low degradation. MHI's market share is particularly strong in the Asian market, where it holds a 20% share, driven by the large coal fleet. The company's recent focus on modular and standardized capture units has strengthened its position in the growing retrofit market.
Siemens Energy AG holds a significant 10% share of the CCS technology market, with particular strength in the natural gas power plant segment, where it commands a 12% share. The company's focus on integrated power and CCS solutions is a key differentiator. Shell plc is a major player in the CCS project development and operation segment, holding a 9% global share, with a strong position in the European and North American storage and transport markets.
Recent Developments in CCS in Power Generation Market
- 2025: Fluor Corporation announced a strategic partnership with a leading power utility to develop a 1 Mtpa CCS project at a coal-fired plant in the US Midwest, utilizing its advanced Econamine FG PlusSM technology.
- 2025: Mitsubishi Heavy Industries launched a new modular CCS unit designed specifically for natural gas power plants, offering a 20% reduction in installation costs and a 15% improvement in energy efficiency compared to previous designs.
CCS in Power Generation Market Segments
By Technology
- Post-Combustion Capture
- Pre-Combustion Capture
- Oxy-Fuel Combustion Capture
By Application
- Coal-Fired Power Plants
- Natural Gas Power Plants
- Biomass Power Plants
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM