Laser Energy Detectors Market Size, Share Demand Report By Type (Thermopile Detectors, Pyroelectric Detectors, Photodiode Detectors), By Application (Industrial, Medical, Scientific Research) By Region & Segment Forecasts, 2026–2034
USD 3950
Laser Energy Detectors Market Size
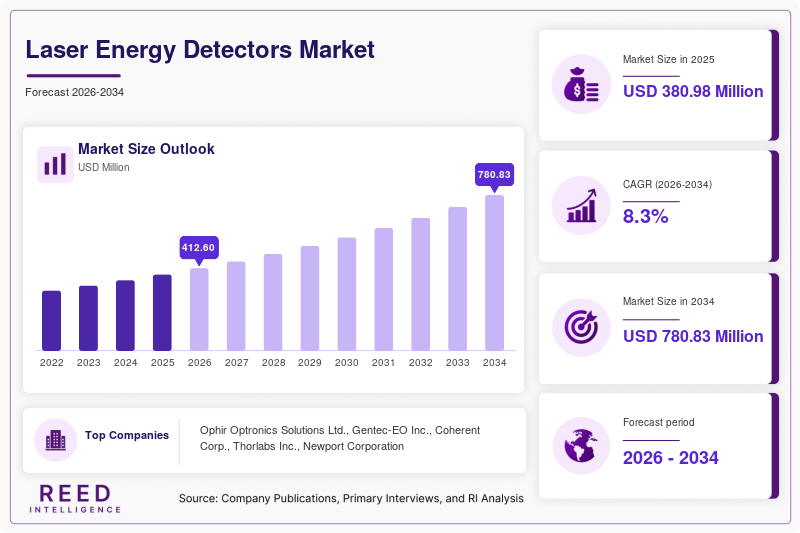
Laser Energy Detectors market size is projected at USD 412.6 million in 2026 and is expected to hit USD 782.4 million by 2034 with a CAGR of 8.3%. The market expansion is supported by increasing laser deployment across manufacturing, healthcare, defense, and scientific laboratories. Growing requirements for accurate laser power measurement, detailed performance benchmarking, and enhanced quality assurance are strengthening investments across the competitive landscape. Market participants are focusing on advanced sensing technologies, calibration accuracy, and high-power laser compatibility to improve industry penetration.
Laser energy detectors are precision instruments designed to measure laser pulse energy, average power, and beam characteristics. In 2025, global production exceeded 1.9 million units, with industrial applications accounting for approximately 46% of total consumption. Medical applications contributed nearly 24%, while scientific research represented 18% of market demand. Adoption rates in advanced manufacturing facilities surpassed 58%, supported by increasing automation and precision laser processing requirements. The growing integration of laser systems across semiconductor fabrication and materials processing continues to reinforce Laser Energy Detectors Market Share.
Laser Energy Detectors Market Trends
Rising Adoption of High-Power Laser Measurement Technologies
The deployment of high-power fiber lasers and ultrafast laser systems has increased significantly, creating demand for advanced laser energy detectors capable of measuring outputs exceeding 100 kW. More than 62% of newly installed industrial laser systems now incorporate integrated energy monitoring solutions. Manufacturers produced over 720,000 high-precision detector units in 2025, compared with 560,000 units in 2022. Enhanced thermal stability, digital calibration capabilities, and real-time monitoring features are becoming standard across the Laser Energy Detectors Market Trend.
The integration of Industry 4.0 platforms and IoT-enabled laser monitoring systems is transforming detector functionality. Nearly 54% of industrial facilities utilizing laser processing have adopted smart energy detection systems with automated diagnostics. Scientific laboratories increased investments in laser measurement equipment by 11.7% during 2025, while medical laser equipment installations rose by 9.8%. These developments continue to support Laser Energy Detectors Market Demand.
Laser Energy Detectors Market Drivers
Expansion of Industrial Laser Processing Applications
Industrial laser processing systems surpassed 8.5 million operational units globally in 2025. More than 68% of automotive component manufacturers utilize laser-based cutting and welding systems requiring energy monitoring. Semiconductor manufacturing facilities increased laser equipment investments by 14.2%, while electronics production recorded a 10.4% rise in laser-assisted processes. The growing requirement for process accuracy and quality control supports Laser Energy Detectors Market Growth.
Laser Energy Detectors Market Restraints
High Cost of Precision Measurement Equipment
Advanced laser energy detectors capable of measuring ultra-short pulses and high-energy beams often cost 25%–40% more than conventional detectors. Calibration and maintenance expenses can represent 12%–18% of annual operating budgets for research facilities. Small-scale users and educational laboratories face budget constraints, limiting broader adoption despite increasing demand across multiple industries. This factor moderately impacts Laser Energy Detectors Market Growth.
Laser Energy Detectors Market Opportunities
Increasing Investments in Medical Laser Technologies
Global installations of medical laser systems exceeded 680,000 units in 2025, increasing by 13.5% year-over-year. Dermatology, ophthalmology, and cosmetic treatment centers accounted for nearly 57% of medical laser deployments. Growing healthcare expenditure and precision treatment requirements are generating opportunities for detector manufacturers. This expanding ecosystem creates favorable Laser Energy Detectors Market Insights.
Challenges in Laser Energy Detectors Market
Calibration Complexity Across Diverse Laser Platforms
Laser systems operate across wavelengths ranging from 190 nm to over 10,600 nm, creating calibration challenges. Nearly 34% of users report difficulties maintaining consistent measurement accuracy across multiple laser types. Variations in pulse duration, beam profile, and environmental conditions can influence detector performance. Manufacturers continue investing in universal calibration technologies to address these operational challenges within the Laser Energy Detectors Market.
Laser Energy Detectors Market Segmentation
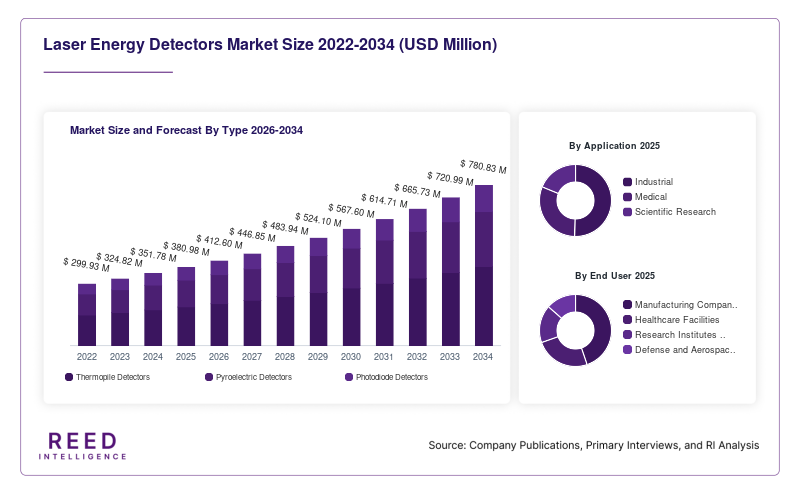
The market is segmented based on type and application. Thermopile detectors account for approximately 42% of revenue, while industrial applications contribute nearly 46% of total market demand.
By Type
Thermopile detectors represent approximately 42% of market revenue. Production exceeded 800,000 units in 2025. These detectors support measurement ranges from milliwatts to kilowatts and provide broad wavelength compatibility for industrial and research applications.
Pyroelectric detectors account for nearly 31% market share. Annual production surpassed 590,000 units. They offer nanosecond pulse measurement capability and are widely utilized in pulsed laser energy monitoring systems.
Photodiode detectors hold approximately 27% share and recorded production above 510,000 units in 2025. These detectors provide high-speed response, compact form factors, and sensitivity across visible and near-infrared wavelengths.
By Application
Industrial applications contribute around 46% of total demand, with more than 870,000 detector units installed annually. Laser cutting, welding, engraving, additive manufacturing, and semiconductor processing rely heavily on precise energy monitoring.
Medical applications account for nearly 24% market share. More than 450,000 detector units support surgical lasers, dermatology systems, ophthalmic equipment, and aesthetic treatment platforms. Usage penetration exceeds 61% among advanced laser treatment centers.
Scientific research represents approximately 18% of market demand. Universities, national laboratories, and photonics institutes collectively deploy over 340,000 detector units for spectroscopy, quantum research, and optical experimentation.
Laser Energy Detectors Market Regional Outlook
North America Laser Energy Detectors Market
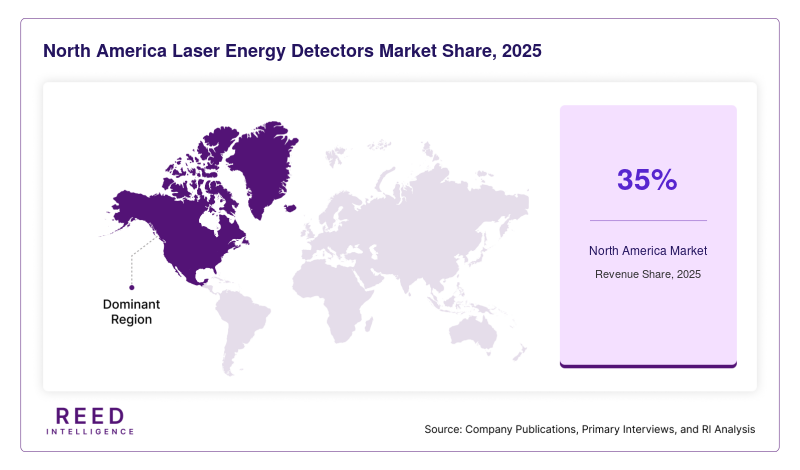
North America accounts for approximately 35% of global revenue. The United States contributes nearly 81% of regional demand, supported by defense programs, semiconductor manufacturing, and advanced medical technology adoption. Annual production exceeds 650,000 detector units.
Europe Laser Energy Detectors Market
Europe holds around 28% market share. Germany, France, and the United Kingdom collectively contribute over 67% of regional demand. Industrial laser manufacturing and scientific research investments remain key growth drivers.
Asia-Pacific Laser Energy Detectors Market
Asia-Pacific represents approximately 29% of global demand. China accounts for nearly 44% of regional consumption, followed by Japan and South Korea. Production volumes exceeded 780,000 units during 2025 due to expanding electronics and semiconductor industries.
Latin America Laser Energy Detectors Market
Latin America contributes about 5% of global revenue. Brazil and Mexico account for more than 62% of regional demand, supported by industrial modernization and medical technology adoption.
Middle East & Africa Laser Energy Detectors Market
The Middle East & Africa region represents approximately 3% market share. Increasing investments in healthcare infrastructure and industrial automation are supporting gradual market expansion.
Top players in Laser Energy Detectors Market
- Ophir Optronics Solutions Ltd.
- Gentec-EO Inc.
- Coherent Corp.
- Thorlabs Inc.
- Newport Corporation
- MKS Instruments Inc.
- Laser Components GmbH
- Hamamatsu Photonics K.K.
- Scientech Inc.
- Edmund Optics Inc.
- OZ Optics Ltd.
- DataRay Inc.
- Photonis Technologies
- Primes GmbH
- LASERPOINT Srl
Ophir Optronics Solutions Ltd.
- Estimated market share of approximately 18%.
- Maintains a strong portfolio across thermopile, photodiode, and pyroelectric detector technologies.
- Operates extensive calibration facilities supporting industrial, medical, and defense sectors.
- Strong presence in North America, Europe, and Asia-Pacific with advanced measurement solutions for high-power laser systems.
- Focuses on digital connectivity, automation integration, and high-precision energy monitoring applications.
Gentec-EO Inc.
- Estimated market share of approximately 14%.
- Recognized for high-performance laser measurement instruments and beam diagnostics systems.
- Supplies detectors covering ultraviolet, visible, infrared, and high-energy laser applications.
- Maintains significant penetration in research laboratories, semiconductor facilities, and industrial manufacturing environments.
- Expands product capabilities through advanced calibration technologies and smart monitoring solutions.
Recent Developments in Laser Energy Detectors Market
- 2025: Gentec-EO launched enhanced high-power thermopile detectors supporting industrial laser applications above 100 kW.
- 2025: Coherent expanded its laser measurement portfolio with integrated digital monitoring capabilities.
Laser Energy Detectors Market Segments
By Type
- Thermopile Detectors
- Pyroelectric Detectors
- Photodiode Detectors
By Application
- Industrial
- Medical
- Scientific Research
By End User
- Manufacturing Companies
- Healthcare Facilities
- Research Institutes and Universities
- Defense and Aerospace Organizations
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM