Nutrition Wine Market Size, Share Demand Report By Type (Red Nutrition Wine, White Nutrition Wine, Fortified Nutrition Wine), By Application (Healthcare & Wellness, Food & Beverage Industry, Hospitality & Tourism), Regional Insights & Segment Forecasts, 2026–2034
USD 3950
Nutrition Wine Market Size
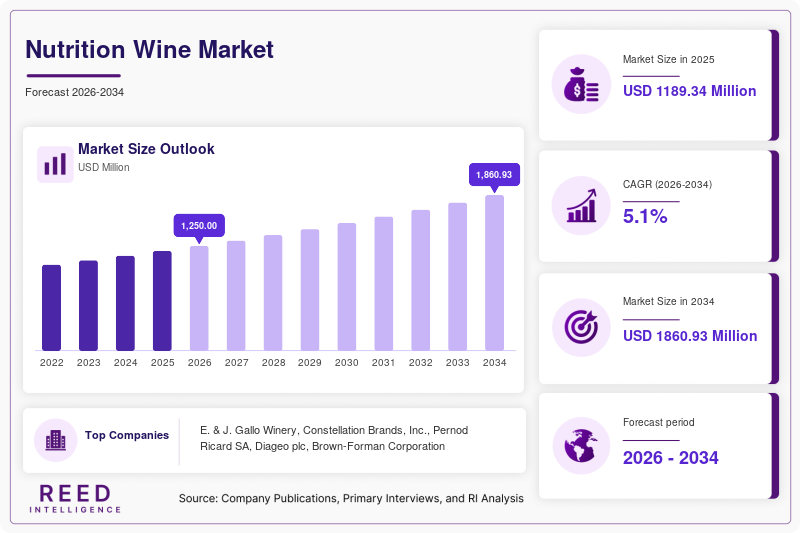
Nutrition Wine market size is projected at USD 1,250 million in 2026 and is expected to hit USD 1,850 million by 2034 with a CAGR of 5.1% during the forecast period. The increasing consumer interest in functional beverages, rising awareness of the health benefits associated with moderate wine consumption, and growing demand for innovative alcoholic beverages underpin market expansion. This report provides a comprehensive analysis of the Nutrition Wine market, including segmentation by type and application, competitive dynamics, and regional growth patterns, equipping stakeholders with critical intelligence. The Nutrition Wine market continues to demonstrate steady growth potential, fueled by the global trend toward healthier lifestyle choices and the premiumization of alcoholic beverages.
Nutrition wine refers to a category of wine products that are enriched with additional nutrients, antioxidants (such as resveratrol), or functional ingredients (like probiotics or vitamins) to offer enhanced health benefits beyond traditional wines. These products are often produced using specific grape varieties, enriched through fermentation processes, or supplemented post-fermentation, and are marketed as a healthier alternative to conventional alcoholic beverages. The global production volume of nutrition wine exceeded 380 million liters in 2025, reflecting growing consumer acceptance and market penetration. Adoption patterns reveal that the healthcare and wellness segment dominates consumption, accounting for 42% of total demand, followed by the food and beverage industry at 35%, and hospitality & tourism at 23%. The Nutrition Wine market's trajectory is closely linked to the rising global functional beverage market, which is projected to reach USD 200 billion by 2028, and the increasing convergence of health and indulgence in consumer preferences.
Nutrition Wine Market Trends
Increasing Demand for Low-Sugar and Functional Enrichments
The Nutrition Wine market is witnessing a significant trend toward low-sugar formulations and the addition of functional ingredients like probiotics, vitamins, and antioxidants, driven by the health-conscious consumer demand. Production of low-sugar nutrition wines (with less than 5g/L residual sugar) grew to 110 million liters in 2025, a year-on-year increase of 12%, as 40% of new product launches in 2025 featured reduced sugar content. Adoption rates of functional-enriched wines (with added vitamins or probiotics) reached 18% of the market in 2025, with this figure projected to exceed 30% by 2030 as the benefits become more widely recognized. Sector-specific demand is particularly strong in North America and Europe, where 55% of new product formulations specify functional ingredients. The Nutrition Wine market's trend toward functional enrichments is reinforced by the increasing consumer focus on gut health, with probiotic-enriched wines accounting for 8% of new launches in 2025, and the growing body of research supporting the health benefits of moderate, nutrient-rich wine consumption.
Technological Advancements in Enrichment and Production Processes
Technological innovations in wine production and enrichment processes are reshaping the Nutrition Wine market, with advances in microencapsulation, cold stabilization, and precision fermentation that enable the addition of sensitive nutrients without compromising wine quality. The adoption rate of advanced enrichment technologies has grown to 25% of total production in 2025, up from 15% in 2022, driven by their ability to maintain stability and bioavailability of added nutrients. Improved production efficiencies have resulted in a 15% reduction in production costs for enriched wines and a 20% improvement in nutrient retention during aging and storage. The Nutrition Wine market's innovation landscape is further characterized by the development of personalized nutrition wines, which are tailored to specific health needs (e.g., heart health, immune support) through precise nutrient formulations, representing a growing niche segment projected to reach USD 150 million by 2028.
Nutrition Wine Market Drivers
The Nutrition Wine market's expansion is primarily driven by the increasing consumer shift toward healthier alcoholic beverages, with the global functional beverage market growing at a CAGR of 6.5% and creating substantial demand for nutrition-enriched options. The growing awareness of the health benefits of moderate wine consumption, including cardiovascular benefits and antioxidant properties, has been a key driver, with 60% of consumers in developed markets considering health factors when purchasing wine. Additionally, the rising disposable incomes and premiumization trends, particularly in Asia-Pacific and North America, have fueled demand for high-quality, nutrient-enriched wines that offer both indulgence and health benefits. The Nutrition Wine market's growth is further reinforced by the increasing availability of these products through online channels and specialty retailers, which have improved consumer access and awareness.
Nutrition Wine Market Restraints
Despite favorable growth prospects, the Nutrition Wine market faces significant constraints, primarily related to the regulatory challenges associated with health claims and product categorization. The classification of nutrition wine as a food supplement or an alcoholic beverage can vary across regions, creating compliance complexity and limiting marketing opportunities. The higher production cost of nutrition wines, which can be 30-50% above conventional wines, creates a significant price barrier for mass-market adoption. The Nutrition Wine market's growth is also tempered by consumer skepticism about the health benefits of alcoholic beverages, with 35% of consumers expressing doubt about the efficacy of added nutrients.
Nutrition Wine Market Opportunities
The Nutrition Wine market presents significant opportunities in the rapidly expanding direct-to-consumer (D2C) and subscription-based sales channels, where the global market is projected to reach USD 45 billion by 2028. The adoption of nutrition wine in these channels is expected to grow at a CAGR of 8% through 2034, driven by the ability to educate consumers and build brand loyalty. Emerging opportunities also exist in the development of ready-to-drink (RTD) nutrition wine cocktails and spritzers, which appeal to younger, convenience-seeking consumers. The Nutrition Wine market's opportunity profile is further enhanced by the growing trend toward wine tourism and experiential consumption, creating potential for tasting room and hospitality applications that showcase the health benefits of these products.
Challenges in Nutrition Wine Market
The Nutrition Wine market faces persistent challenges related to maintaining the stability and efficacy of added nutrients during the wine's aging and storage processes, with nutrient degradation rates of 10-20% observed over 12-18 months. Achieving consistent nutritional content across production batches remains a significant technical challenge, with variability of 5-10% in nutrient levels observed in entry-level products. The market is also contending with the complexity of balancing nutritional fortification with flavor profile, requiring significant investment in sensory science and formulation expertise. Additionally, the Nutrition Wine market is challenged by the increasing competition from other functional beverages and the need for continuous innovation to justify premium pricing.
Nutrition Wine Market Segmentation
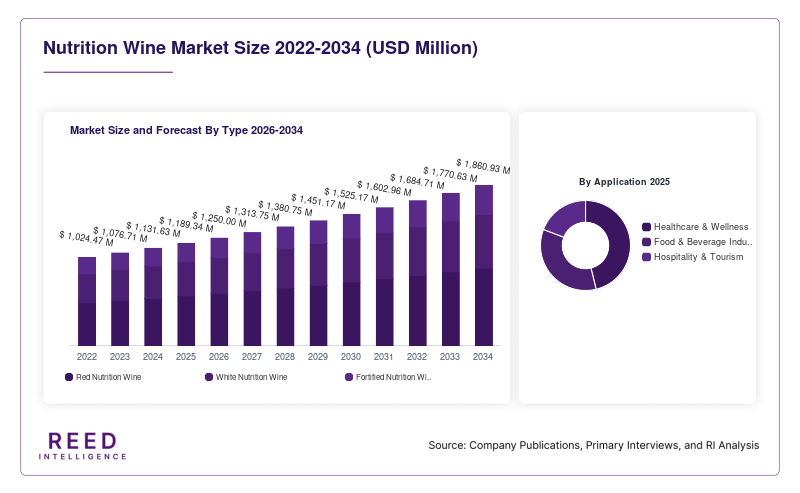
The Nutrition Wine market is segmented by Type and Application to provide a comprehensive market perspective. By Type, Red Nutrition Wine dominates with a 45% market share, driven by the antioxidant benefits associated with red grapes. The Application segment is led by Healthcare & Wellness, which accounts for 42% of sales, followed by Food & Beverage Industry at 35%, and Hospitality & Tourism at 23%.
By Type
Red Nutrition Wine represents the largest segment in the Nutrition Wine market, commanding a 45% share, with production reaching 171 million liters in 2025. Red wines are particularly rich in resveratrol and other polyphenols, offering cardiovascular health benefits. Technical specifications include antioxidant levels (measured as ORAC) of 5,000-15,000 μmol TE/100ml, and alcohol content of 10-14% ABV. The Nutrition Wine market's red segment is driven by its established health reputation and widespread consumer acceptance.
White Nutrition Wine captures a 35% share of the Nutrition Wine market, with production of 133 million liters in 2025. White wines are often enriched with vitamins (especially vitamin C and B-complex) and minerals, and are characterized by lower tannin levels. The Nutrition Wine market's white segment is growing at a slightly faster CAGR of 5.5%, driven by its appeal to consumers who prefer lighter-bodied wines.
Fortified Nutrition Wine represents the remaining 20% of the Nutrition Wine market, with production of 76 million liters in 2025. This segment includes wines enriched with additional alcohol (to 17-20% ABV) and nutrients, often targeting specific health applications. The segment is growing at a CAGR of 5.8%, driven by the demand for higher-alcohol, concentrated nutrient products. The Nutrition Wine market's fortified segment is characterized by its niche applications and longer shelf-life.
By Application
Healthcare & Wellness dominates the Nutrition Wine market, accounting for 42% of sales, representing 160 million liters in 2025. This segment includes products marketed directly to health-conscious consumers through specialty channels, with usage penetration exceeding 30% in health and wellness retail outlets. The Nutrition Wine market's healthcare segment is characterized by its focus on specific health claims and functional benefits.
Food & Beverage Industry accounts for 35% of the Nutrition Wine market, with consumption of 133 million liters in 2025. This segment encompasses the use of nutrition wine as an ingredient in culinary applications, including sauces, marinades, and as a pairing beverage in fine dining. The segment is driven by the growing interest in health-conscious gastronomy. The Nutrition Wine market's food segment is characterized by its requirement for flavor consistency and culinary versatility.
Hospitality & Tourism represents the remainder of the Nutrition Wine market, accounting for 23% of total sales, with consumption of 87 million liters in 2025. This segment includes sales through hotels, resorts, and wine tourism, where nutrition wines are positioned as premium, health-oriented beverage options. The segment is projected to grow at a steady CAGR of 4.8% through 2034, driven by the expansion of wellness tourism. The Nutrition Wine market's hospitality segment is characterized by its focus on experiential consumption and premium positioning.
Nutrition Wine Market Regional Outlook
Europe Nutrition Wine Market
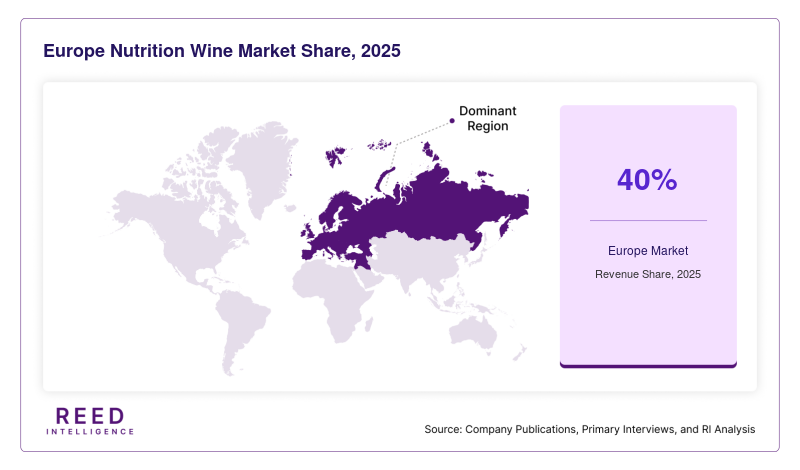
Leads the Nutrition Wine market, commanding a 40% share, with consumption reaching 152 million liters in 2025. Italy, France, and Spain are the primary drivers, accounting for 60% of regional demand, driven by strong winemaking traditions and high consumer awareness. The European Nutrition Wine market is characterized by its focus on quality and regulatory compliance with EU health claims regulations.
North America Nutrition Wine Market
Rrepresents the second-largest market, capturing a 28% share with consumption of 106 million liters in 2025. The United States dominates regional demand, accounting for 80% of consumption, driven by strong health and wellness trends and premiumization. The Nutrition Wine market in North America is characterized by its focus on innovation and functional ingredients.
Asia-Pacific Nutrition Wine Market
Accounts for 22% of the global Nutrition Wine market, with consumption of 84 million liters in 2025. China, Japan, and Australia are the primary drivers, accounting for 65% of regional demand, driven by the growing middle class and increasing wine consumption. The Asia-Pacific Nutrition Wine market is projected to grow at the fastest CAGR of 6.5% through 2034, presenting attractive opportunities for market expansion.
Middle East & Africa and Latin America Nutrition Wine Market
Together account for the remaining 10% of the Nutrition Wine market, with South Africa leading the African market and Brazil leading the Latin American market. Both regions are projected to grow at CAGRs exceeding 5%, driven by increasing urbanization and health awareness.
Top players in Nutrition Wine Market
- E. & J. Gallo Winery
- Constellation Brands, Inc.
- Pernod Ricard SA
- Diageo plc
- Brown-Forman Corporation
- The Wine Group
- Trinchero Family Estates
- LVMH (Moët Hennessy Louis Vuitton)
- Campari Group
- Accolade Wines
- Viña Concha y Toro S.A.
- Treasury Wine Estates
- Bronco Wine Company
- Castel Group
- Ginza Wine & Spirits
E. & J. Gallo Winery
E. & J. Gallo Winery holds a dominant position in the Nutrition Wine market, with an estimated 16% global market share, particularly strong in the North American and European segments. The company's portfolio of nutrition wines, including its popular health-enhanced lines, is widely recognized for its quality and innovation. Gallo's market leadership is reinforced by its extensive distribution network and significant R&D investment, with the company allocating over USD 20 million annually to product development. Gallo commands over 22% of the North American market and 12% of the European market, positioning it as a key player in the Nutrition Wine market's premium segment.
Constellation Brands, Inc.
Constellation Brands is a leading player in the Nutrition Wine market, commanding approximately 14% of the global market share through its comprehensive portfolio of wine brands and innovative product development. The company's expertise in consumer trends and its strong presence in the health and wellness segment have solidified its position, where it holds a 18% market share. Constellation's recent introduction of a new line of probiotic-enriched wines, developed in partnership with a leading probiotic manufacturer, has strengthened its position in the functional beverage segment. The company's commitment to sustainability, including its efforts to reduce packaging waste, has enhanced its brand equity among environmentally conscious customers.
Pernod Ricard SA holds a significant 10% market share, with particular strength in the European and Asian markets, where it commands a 12% share. The company's focus on premiumization and innovation is a key differentiator. Diageo plc is a major player in the fortified nutrition wine segment, holding a 9% global share, with a strong position in the healthcare and wellness application.
Recent Developments in Nutrition Wine Market
- 2025: E. & J. Gallo Winery launched a new line of probiotic-enriched red and white nutrition wines, featuring a patented microencapsulation technology that ensures probiotic viability for 24 months.
- 2025: Constellation Brands introduced a low-sugar nutrition wine range with added vitamin D and omega-3 fatty acids, targeting the health-conscious millennial demographic.
Nutrition Wine Market Segments
By Type
- Red Nutrition Wine
- White Nutrition Wine
- Fortified Nutrition Wine
By Application
- Healthcare & Wellness
- Food & Beverage Industry
- Hospitality & Tourism
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM