Laser Mask Writer Market Size, Share & Trends Analysis Report By Type, By Application, By End User and By Region, Forecasts 2026–2034
USD 3950
Laser Mask Writer Market Size
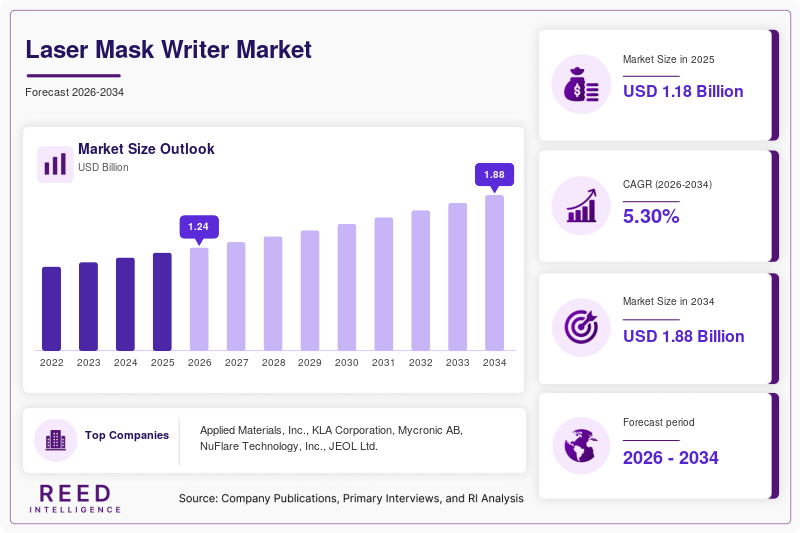
The global laser mask writer market was valued at USD 1.18 billion in 2025 and is projected to grow from USD 1.25 billion in 2026 to USD 1.89 billion by 2034, registering a CAGR of 5.30% during the forecast period from 2026 to 2034.
Laser mask writers are precision lithography systems used to create patterns on photomasks and reticles for semiconductor manufacturing and other microfabrication applications. These systems use focused laser beams to write highly detailed patterns onto mask substrates, enabling the transfer of circuit designs during photolithography.
The market is supported by continued semiconductor manufacturing expansion, increasing demand for advanced integrated circuits, growth in display manufacturing and the increasing complexity of electronic devices. Semiconductor manufacturers and mask shops require increasingly precise pattern-generation equipment as feature dimensions become smaller and circuit designs become more sophisticated.
Laser Mask Writer Market Drivers
Growth of Semiconductor Manufacturing
The expansion of semiconductor manufacturing capacity is a major factor supporting demand for mask-writing equipment.
New fabrication facilities and capacity expansions require photomask infrastructure and associated pattern-generation technologies.
Increasing Complexity of Integrated Circuits
Modern chips contain increasingly complex circuit patterns and require highly accurate mask production.
This is supporting investment in precision writing systems capable of producing detailed patterns with stringent overlay and resolution requirements.
Expansion of Advanced Electronics
Artificial intelligence, high-performance computing, automotive electronics, 5G infrastructure and advanced consumer devices are increasing semiconductor content across multiple industries.
Growing semiconductor demand indirectly supports the photomask and mask-writing equipment ecosystem.
Growth of Display Manufacturing
Photomasks are also used in display manufacturing processes.
Demand for advanced displays, including high-resolution panels and sophisticated semiconductor-based display technologies, creates additional applications for mask-writing systems.
Semiconductor Supply Chain Localization
Governments and semiconductor companies are investing in domestic and regional semiconductor manufacturing capabilities.
The expansion of fabrication plants and supporting semiconductor infrastructure is generating demand for equipment across the semiconductor production ecosystem.
Laser Mask Writer Market Restraints
High Equipment Cost
Laser mask writers are highly specialized precision systems involving sophisticated optical, mechanical and control technologies.
Their high acquisition cost can restrict adoption, particularly among smaller mask manufacturers.
Complex Technology Requirements
Developing and operating advanced mask-writing systems requires specialized engineering expertise.
Manufacturers must continuously improve optical precision, beam control, pattern accuracy and system reliability.
Competition From Alternative Writing Technologies
Electron-beam mask writers and other pattern-generation technologies compete with laser-based systems in selected applications.
Technology selection depends on resolution requirements, mask complexity, throughput and production economics.
Long Equipment Replacement Cycles
Mask-writing systems represent significant capital investments and can remain operational for extended periods.
Long replacement cycles can limit the frequency of new equipment purchases.
Laser Mask Writer Market Opportunities
Advanced Semiconductor Nodes
The continued development of advanced semiconductor technologies creates opportunities for increasingly precise mask-writing equipment.
Higher pattern complexity and demanding lithography requirements can increase the need for sophisticated mask production capabilities.
Growth of Semiconductor Foundries
Expansion of foundry capacity across Asia, North America and Europe is creating opportunities for equipment suppliers.
New fabrication capacity can increase demand for supporting photomask production and inspection infrastructure.
Automotive Semiconductor Growth
Electric vehicles, autonomous-driving systems, advanced driver-assistance systems and vehicle connectivity are increasing semiconductor content in automobiles.
This creates additional demand throughout the semiconductor manufacturing supply chain.
AI and High-Performance Computing
AI accelerators, processors and high-performance computing systems require advanced semiconductor technologies.
Increasing investment in these applications can support long-term demand for sophisticated mask and lithography infrastructure.
Emerging Semiconductor Manufacturing Regions
New semiconductor manufacturing investments in regions seeking greater supply-chain resilience create opportunities for equipment suppliers to expand their presence.
Type Segment Analysis
By Type
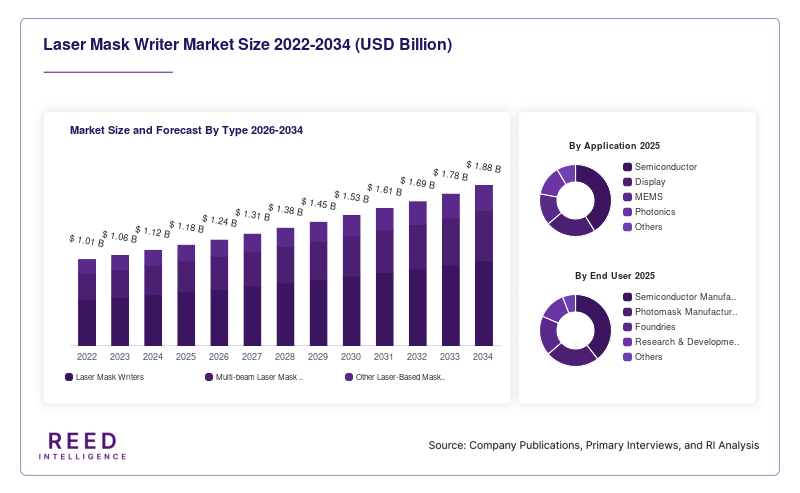
Laser mask writers accounted for approximately 71% of the laser mask writer market in 2025, making them the dominant type segment. Their established use in photomask production and broad applicability across semiconductor and display manufacturing support their position.
Multi-beam laser mask writers accounted for approximately 18% and are projected to grow at approximately 7.2% CAGR, making them the fastest-growing major type segment. Increasing demand for higher throughput and advanced pattern-writing capabilities is supporting adoption.
Other laser-based mask-writing systems represented approximately 11% of the market.
Application Segment Analysis
By Application
Semiconductor applications accounted for approximately 64% of the market in 2025, making them the dominant application segment. Growing semiconductor production and increasing circuit complexity are supporting demand for precision photomask manufacturing.
Photonics accounted for approximately 9% and is projected to grow at approximately 7.0% CAGR, making it the fastest-growing major application segment. Increasing adoption of optical communication, sensing and photonic technologies is supporting demand for precision patterning.
Display applications represented approximately 21%, MEMS approximately 7%, and other applications approximately 8%.
End-User Segment Analysis
By End User
Photomask manufacturers accounted for approximately 43% of the market in 2025, making them the largest end-user segment. Mask shops require specialized writing systems to manufacture photomasks used in semiconductor and display lithography.
Foundries accounted for approximately 24% and are projected to grow at approximately 6.5% CAGR, making them the fastest-growing major end-user segment. Increasing foundry capacity and semiconductor localization initiatives are supporting investment.
Semiconductor manufacturers represented approximately 23%, research and development institutions approximately 6%, and other end users approximately 4%.
Laser Mask Writer Market Regional Analysis
Asia-Pacific Holds the Largest Share
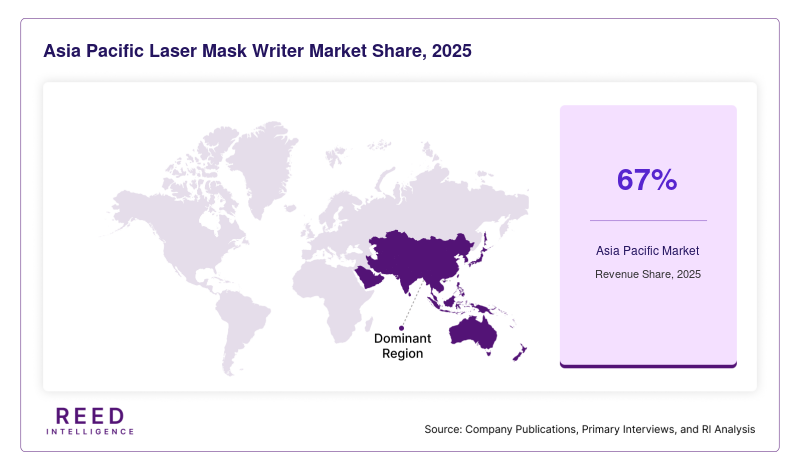
Asia-Pacific accounted for approximately 67% of the global laser mask writer market in 2025, making it the dominant regional market. The region has a large concentration of semiconductor manufacturers, foundries, photomask producers and display manufacturers.
North America accounted for approximately 17% and is projected to grow at approximately 6.4% CAGR, making it the fastest-growing major region. Semiconductor manufacturing investments, government-supported capacity expansion and increasing domestic semiconductor production are supporting regional demand.
Europe Maintains Specialized Demand
Europe accounted for approximately 11% of the market in 2025 and is projected to grow at approximately 4.5% CAGR.
The region benefits from semiconductor equipment expertise, automotive semiconductor demand and investments in strengthening regional semiconductor capabilities.
Latin America Represents an Emerging Opportunity
Latin America accounted for approximately 3% of the market in 2025 and is projected to grow at approximately 4.8% CAGR.
Growing electronics manufacturing and increasing investment in technology infrastructure provide opportunities for market development.
Middle East & Africa Shows Early-Stage Adoption
Middle East & Africa accounted for approximately 2% of the market in 2025 and is projected to grow at approximately 5.0% CAGR.
Technology diversification, electronics investments and emerging semiconductor-related initiatives are supporting gradual market development.
Laser Mask Writer Market Competitive Landscape
Competition in the laser mask writer market is based on patterning accuracy, writing speed, resolution, system reliability, technology integration, service capabilities and installed-base support.
The market is characterized by specialized equipment suppliers with strong expertise in lithography, optics, precision motion systems and semiconductor manufacturing technologies.
Key Market Players
- Applied Materials, Inc.
- KLA Corporation
- Mycronic AB
- NuFlare Technology, Inc.
- JEOL Ltd.
- SUSS MicroTec SE
- Heidelberg Instruments
- Raith GmbH
- Vistec Electron Beam GmbH
- SVG Optronics
Laser Mask Writer Market Recent Developments
- Semiconductor manufacturers continue expanding fabrication capacity across major production regions. The development of new fabs and expansion of existing facilities is increasing demand for supporting photomask and lithography infrastructure.
- Equipment suppliers are improving writing accuracy, throughput and pattern-generation capabilities to address increasingly complex mask requirements. Higher-performance systems are particularly relevant to advanced semiconductor and high-resolution display applications.
Laser Mask Writer Market Segments
By Type
- Laser Mask Writers
- Multi-beam Laser Mask Writers
- Other Laser-Based Mask Writing Systems
By Application
- Semiconductor
- Display
- MEMS
- Photonics
- Others
By End User
- Semiconductor Manufacturers
- Photomask Manufacturers
- Foundries
- Research & Development Institutions
- Others
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM